BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$1.28
S$2.05
60.2%
S$2.10
Analyst
Highlights
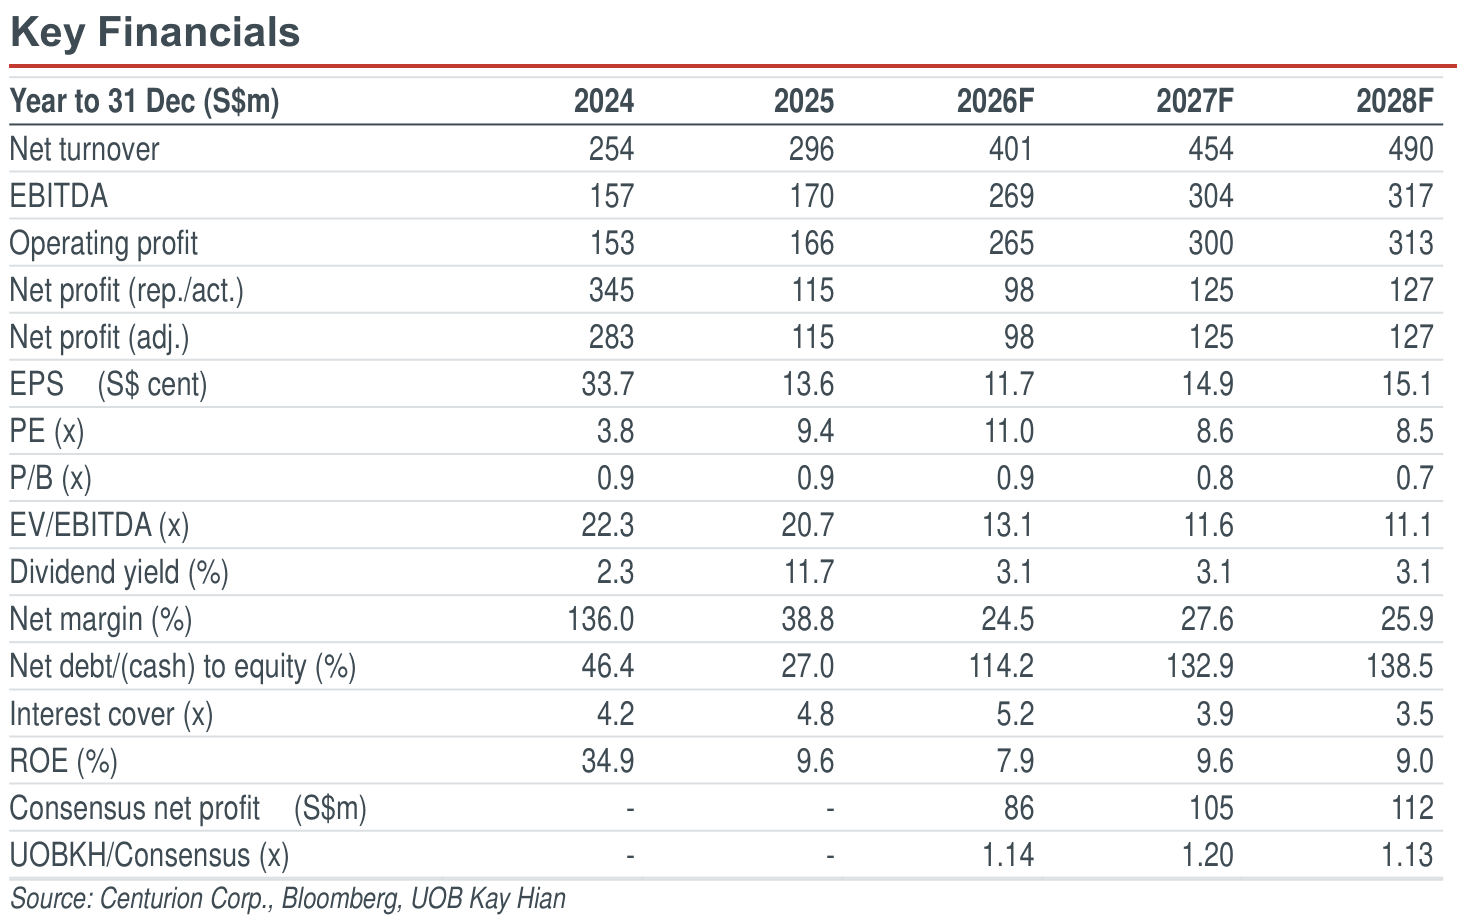
- Reinvesting for growth. Following the successful listing of Centurion Accommodation REIT (CAREIT), CENT’s balance sheet had strengthened significantly with end-25 net gearing at decade-lows and high net cash balances, embarking on a significant reinvestment growth path. YTD 2026, it had acquired over S$750m worth of projects, of which 70% are development land in Singapore and the remaining 30% in completed and income-generating buildings in Australia, Malaysia and Hong Kong SAR.
- Potential addition of 22,684 beds between 2H26-1Q29. In all, these new investments, coupled with development projects currently in the pipeline, could add 22,684 beds to CENT’s portfolio, or about 41% of its current ex-CAREIT portfolio between 2H26-1Q29. These include two purpose-built workers accommodation (PBWA) development sites in Singapore, with a capacity of 12,000 beds when fully operational and a completed 7,974-bed dormitory in Pasir Gudang as well as maiden foray into income generating properties catering to the under-supplied key worker accommodation (KWA) market in Australia and rental assets in Hong Kong SAR.
Analysis
- S$2b in attributable GDV… We estimate these developments could generate around S$2b in attributable gross development value, assuming a yield on cost of 3.5-6.9%, once stabilised. The bulk of this value creation exercise is derived from the two PBWA projects in Singapore (~S$1.3b), four new purpose-built student accommodation (PBSA) developments in Melbourne and Perth in Australia (total 1,973 beds), one PBSA project in the UK (225 beds) as well as its conversion projects in Hong Kong SAR. Our estimates have not included any accretion from the newly acquired mixed-use development site at 200 North Terrace property in Adelaide and its 65% stake in Kim Chuan Place, pending more development details.
Highlights
- Reinvesting for growth. Following the successful listing of Centurion Accommodation REIT (CAREIT), CENT’s balance sheet had strengthened significantly with end-25 net gearing at decade-lows and high net cash balances, embarking on a significant reinvestment growth path. YTD 2026, it had acquired over S$750m worth of projects, of which 70% are development land in Singapore and the remaining 30% in completed and income-generating buildings in Australia, Malaysia and Hong Kong SAR.
- Potential addition of 22,684 beds between 2H26-1Q29. In all, these new investments, coupled with development projects currently in the pipeline, could add 22,684 beds to CENT’s portfolio, or about 41% of its current ex-CAREIT portfolio between 2H26-1Q29. These include two purpose-built workers accommodation (PBWA) development sites in Singapore, with a capacity of 12,000 beds when fully operational and a completed 7,974-bed dormitory in Pasir Gudang as well as maiden foray into income generating properties catering to the under-supplied key worker accommodation (KWA) market in Australia and rental assets in Hong Kong SAR.
Analysis
- S$2b in attributable GDV… We estimate these developments could generate around S$2b in attributable gross development value, assuming a yield on cost of 3.5-6.9%, once stabilised. The bulk of this value creation exercise is derived from the two PBWA projects in Singapore (~S$1.3b), four new purpose-built student accommodation (PBSA) developments in Melbourne and Perth in Australia (total 1,973 beds), one PBSA project in the UK (225 beds) as well as its conversion projects in Hong Kong SAR. Our estimates have not included any accretion from the newly acquired mixed-use development site at 200 North Terrace property in Adelaide and its 65% stake in Kim Chuan Place, pending more development details.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$1.28
S$2.05
60.2%
S$2.10
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

23 Sept 2026
LHN (LHN SP): Resilient Core Operations; Growth Pipeline Intact

24 Aug 2026
NTT DC REIT (NTTDCR SP): 1QFY27: A Journey Of A Thousand Miles Begins With A Single Step

21 Sept 2026
Mapletree Pan Asia Commercial Trust (MPACT SP): Green Shoots In Hong Kong And Japan
Our latest research

21 Oct 2026
Keppel REIT (KREIT SP): Refocusing On Home Base Singapore

21 Oct 2026
CapitaLand Integrated Commercial Trust (CICT SP): Retail Upside From Acquisition; Office Upside From Positive Reversion

19 Oct 2026