
Company Coverage
CapitaLand Ascendas REIT (CLAR SP) - 3Q26: Uptick In Occupancy From Singapore And The US
BUY (Maintained)
Current price:
Target price:
Upside:
S$2.21
S$3.25
+47.1%
Analyst
Highlights
- Singapore occupancy rose 0.8ppt qoq to 90.9%, supported by acquisitions of 5 Tuas Avenue 5 and 25 Loyang Crescent, which are fully occupied. Occupancy for the US increased 1.4ppt qoq to 82.3%, driven by leasing at 13144 South Pulaski Road in Chicago and North Topping in Kansas City.
- Completed redevelopment projects are leasing up steadily. Occupancy at 5 Toh Guan Road East reached 64.8% as of Sep 26 and management expects to lease up the remaining logistics space by end-26. Occupancy at 27 IBP stood at 19.0% and is expected to reach 40-50% by end-26.
- Maintain BUY. Target price: S$3.25.
Analysis
- CapitaLand Ascendas REIT (CLAR) provided a 3Q26 business update:
- Higher occupancies in Singapore and the US. Portfolio occupancy recovered 1.0ppt qoq to 90.1% as of Sep 26. Singapore occupancy rose 0.8ppt qoq to 90.9%, supported by fully occupied acquisitions and higher logistics occupancy. US occupancy increased 1.4ppt qoq to 82.3%, driven by leasing at 13144 South Pulaski Road in Chicago and North Topping in Kansas City. Japan remained fully occupied.
- Stronger rental reversions led by Australia. Renewals at multi-tenanted buildings achieved positive rental reversion of 9.9% in 3Q26 (2Q26: 5.2%), bringing 9M26 reversion to 9.0%. Australia recorded 32.5%, including 39.1% for logistics and 13.8% for business space. Singapore and the US achieved 4.3% and 6.4%, respectively. Management expects positive high single-digit rental reversion for 2026. Lifestyle & consumer products and government & NGO accounted for 24.6% and 23.5% of new demand by gross rental income respectively in Singapore. Logistics & supply chain management led overseas demand at 39.9%. Portfolio WALE was 4.1 years.
- Lower debt costs but higher leverage following acquisitions. Weighted average all-in debt cost eased 0.2ppt yoy to 3.4% for 9M26. Aggregate leverage increased 2.1ppt qoq to 41.8%, mainly from acquisition funding. Interest coverage remains healthy at 3.4x. Fixed-rate debt represented 70.1% of borrowings, with an average fixed-debt tenure of 2.9 years. CLAR retained its Moody's A3 credit rating. Applying estimated net divestment proceeds of S$255m to debt repayment would lower leverage to 41%.
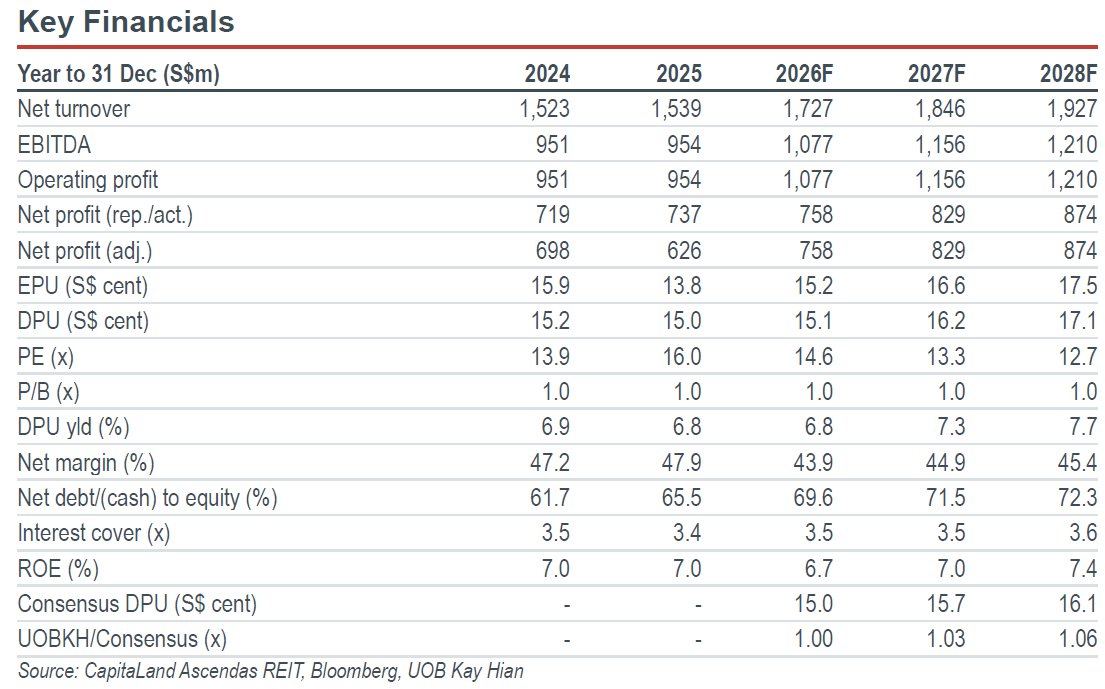
Highlights
- Singapore occupancy rose 0.8ppt qoq to 90.9%, supported by acquisitions of 5 Tuas Avenue 5 and 25 Loyang Crescent, which are fully occupied. Occupancy for the US increased 1.4ppt qoq to 82.3%, driven by leasing at 13144 South Pulaski Road in Chicago and North Topping in Kansas City.
- Completed redevelopment projects are leasing up steadily. Occupancy at 5 Toh Guan Road East reached 64.8% as of Sep 26 and management expects to lease up the remaining logistics space by end-26. Occupancy at 27 IBP stood at 19.0% and is expected to reach 40-50% by end-26.
- Maintain BUY. Target price: S$3.25.
Analysis
- CapitaLand Ascendas REIT (CLAR) provided a 3Q26 business update:
- Higher occupancies in Singapore and the US. Portfolio occupancy recovered 1.0ppt qoq to 90.1% as of Sep 26. Singapore occupancy rose 0.8ppt qoq to 90.9%, supported by fully occupied acquisitions and higher logistics occupancy. US occupancy increased 1.4ppt qoq to 82.3%, driven by leasing at 13144 South Pulaski Road in Chicago and North Topping in Kansas City. Japan remained fully occupied.
- Stronger rental reversions led by Australia. Renewals at multi-tenanted buildings achieved positive rental reversion of 9.9% in 3Q26 (2Q26: 5.2%), bringing 9M26 reversion to 9.0%. Australia recorded 32.5%, including 39.1% for logistics and 13.8% for business space. Singapore and the US achieved 4.3% and 6.4%, respectively. Management expects positive high single-digit rental reversion for 2026. Lifestyle & consumer products and government & NGO accounted for 24.6% and 23.5% of new demand by gross rental income respectively in Singapore. Logistics & supply chain management led overseas demand at 39.9%. Portfolio WALE was 4.1 years.
- Lower debt costs but higher leverage following acquisitions. Weighted average all-in debt cost eased 0.2ppt yoy to 3.4% for 9M26. Aggregate leverage increased 2.1ppt qoq to 41.8%, mainly from acquisition funding. Interest coverage remains healthy at 3.4x. Fixed-rate debt represented 70.1% of borrowings, with an average fixed-debt tenure of 2.9 years. CLAR retained its Moody's A3 credit rating. Applying estimated net divestment proceeds of S$255m to debt repayment would lower leverage to 41%.
BUY (Maintained)
Current price:
Target price:
Upside:
S$2.21
S$3.25
+47.1%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

30 Oct 2026
CapitaLand Integrated Commercial Trust (CICT SP): 3Q26: Uptick For Office Occupancy; Firmer Reversion For Retail

28 Oct 2026
CapitaLand Ascott Trust (CLAS SP): Sturdy Recovery From Student Accommodation In 3Q26; Strong Reversion From Rental Housing

26 Oct 2026
Keppel DC REIT (KDCREIT SP): 3Q26: Completes Acquisition Ahead Of AI Funding Squeeze
Our latest research

2 Nov 2026
NetLink NBN Trust (NETLINK SP) - 1HFY27: EBITDA In Line; Higher Depreciation A Drag To Earnings

30 Oct 2026
Keppel (KEP SP): Decent Headline Earnings Growth But Slower-than-expected Core Earnings Growth In 3Q26
30 Oct 2026