

Periodic/Sector reports
Banking: 3Q26 Results Preview: NIM Bottoming, While Net Interest Income Turns Around
OVERWEIGHT (Upgraded)
Analyst
Highlights
- We expect 3Q26 to be characterised by stabilisation of NIM and resilient loan growth, which enable banks to record growth in net interest income. Growth from wealth management has moderated but maintains its uptrend. Asset quality remains stable. Credit costs are projected at the lower end of guidance. We expect a net profit of S$3,079m for DBS (flat yoy, -4% qoq) and S$2,054m for OCBC (+4% yoy, -8% qoq).
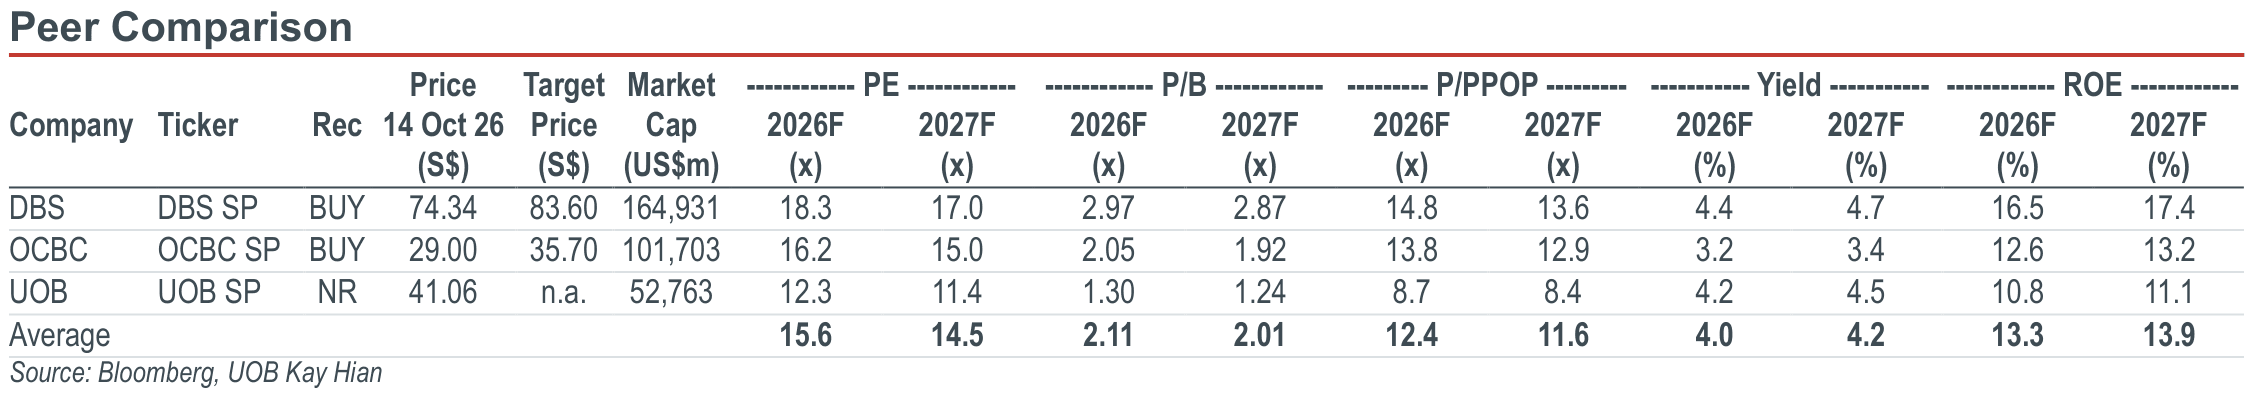
- Upgrade to OVERWEIGHT. A prolonged conflict in the Middle East would cause sustained and elevated inflation, leading to interest rates and bond yields staying much higher for much longer. Our preferred stock pick is OCBC (BUY/Target: S$35.70) given its strategic shift to accelerate growth. OCBC is more sensitive to growth in wealth management fees, which accounted for 63% of its fee income. We also like DBS (BUY/Target: S$83.60) due to its leadership in wealth management and attractive 2027 dividend yield of 4.7%.
Analysis
- 3Q26 results season kicks off with United Overseas Bank (UOB) reporting on 4 November, followed by DBS Group Holdings (DBS) on 5 November and Oversea-Chinese Banking Corporation (OCBC) on the 6 November.
- DBS Group Holdings (DBS SP/BUY/Target: S$83.60)
- We forecast that net profit will be flat yoy but decline 4% qoq to S$3,079m in 3Q26.
- Net interest income boosted by loan growth and stable NIM. We estimate loan growth of 8.3% yoy and 1.0% qoq in 3Q26 with continued expansion in corporate loans and residential mortgages. We expect NIM to arrest its decline and stay flattish at 1.88% in 3Q26 due to: a) higher SGD and USD interest rates with one-month compounded SORA and SOFR gaining 16bp and 12bp respectively to 1.25% and 3.75%, offset by: b) re-pricing of fixed-rate assets at lower interest rates. We forecast net interest income growing 4.8% yoy in 3Q26 (2Q26: -1.8% yoy).
- Wealth management moderating from seasonal peak in 2Q26. Financial markets were affected by the resumption of skirmishes between the US and Iran. Higher bond yields could also have affected appetite to invest in yield plays and fixed income funds. We expect contribution from wealth management to ease 4% qoq but rise 11% yoy to S$880m in 3Q26. Transaction services and loans related fees are likely to remain stable. Overall, fee income could expand at a single-digit rate of 6% yoy in 3Q26 due to the high base last year.
- Stable treasury customer sales. We foresee steady net trading income of S$850m in 3Q26 due to healthy growth in treasury customer sales.
- Maintaining cost discipline. We have factored in a 3% yoy increase in operating expenses. We expect cost-to-income ratio (CIR) to be healthy at 40.1% in 3Q26 (2Q26: 38.6%), in line with guidance of low-40%.
- Resilient asset quality. We project that asset quality will be stable. We expect total provisions of S$204m and credit cost of 17bp in 3Q26 (2Q26: 10bp). Management guided specific provisions of 17-20bp. DBS has ample management overlay for general provisions of S$2.4b.
Highlights
- We expect 3Q26 to be characterised by stabilisation of NIM and resilient loan growth, which enable banks to record growth in net interest income. Growth from wealth management has moderated but maintains its uptrend. Asset quality remains stable. Credit costs are projected at the lower end of guidance. We expect a net profit of S$3,079m for DBS (flat yoy, -4% qoq) and S$2,054m for OCBC (+4% yoy, -8% qoq).
- Upgrade to OVERWEIGHT. A prolonged conflict in the Middle East would cause sustained and elevated inflation, leading to interest rates and bond yields staying much higher for much longer. Our preferred stock pick is OCBC (BUY/Target: S$35.70) given its strategic shift to accelerate growth. OCBC is more sensitive to growth in wealth management fees, which accounted for 63% of its fee income. We also like DBS (BUY/Target: S$83.60) due to its leadership in wealth management and attractive 2027 dividend yield of 4.7%.
Analysis
- 3Q26 results season kicks off with United Overseas Bank (UOB) reporting on 4 November, followed by DBS Group Holdings (DBS) on 5 November and Oversea-Chinese Banking Corporation (OCBC) on the 6 November.
- DBS Group Holdings (DBS SP/BUY/Target: S$83.60)
- We forecast that net profit will be flat yoy but decline 4% qoq to S$3,079m in 3Q26.
- Net interest income boosted by loan growth and stable NIM. We estimate loan growth of 8.3% yoy and 1.0% qoq in 3Q26 with continued expansion in corporate loans and residential mortgages. We expect NIM to arrest its decline and stay flattish at 1.88% in 3Q26 due to: a) higher SGD and USD interest rates with one-month compounded SORA and SOFR gaining 16bp and 12bp respectively to 1.25% and 3.75%, offset by: b) re-pricing of fixed-rate assets at lower interest rates. We forecast net interest income growing 4.8% yoy in 3Q26 (2Q26: -1.8% yoy).
- Wealth management moderating from seasonal peak in 2Q26. Financial markets were affected by the resumption of skirmishes between the US and Iran. Higher bond yields could also have affected appetite to invest in yield plays and fixed income funds. We expect contribution from wealth management to ease 4% qoq but rise 11% yoy to S$880m in 3Q26. Transaction services and loans related fees are likely to remain stable. Overall, fee income could expand at a single-digit rate of 6% yoy in 3Q26 due to the high base last year.
- Stable treasury customer sales. We foresee steady net trading income of S$850m in 3Q26 due to healthy growth in treasury customer sales.
- Maintaining cost discipline. We have factored in a 3% yoy increase in operating expenses. We expect cost-to-income ratio (CIR) to be healthy at 40.1% in 3Q26 (2Q26: 38.6%), in line with guidance of low-40%.
- Resilient asset quality. We project that asset quality will be stable. We expect total provisions of S$204m and credit cost of 17bp in 3Q26 (2Q26: 10bp). Management guided specific provisions of 17-20bp. DBS has ample management overlay for general provisions of S$2.4b.
OVERWEIGHT (Upgraded)
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

12 Oct 2026
Banking: Benefitting From Structural Tailwinds; Healthy Competition For Customer Relationships

24 Sept 2026
Banking: Benefitting From Higher For Longer Bond Yields And Interest Rates

4 Sept 2026
REITs - 2Q26 Round-Up: Soldiering On With Resilient Yield
Our latest research
12 Oct 2026
Banking: Benefitting From Structural Tailwinds; Healthy Competition For Customer Relationships

1 Oct 2026
REITs: S-REITs Monthly Update (Sep 26)

30 Sept 2026