
OVERWEIGHT (Maintained)
Analyst
Highlights
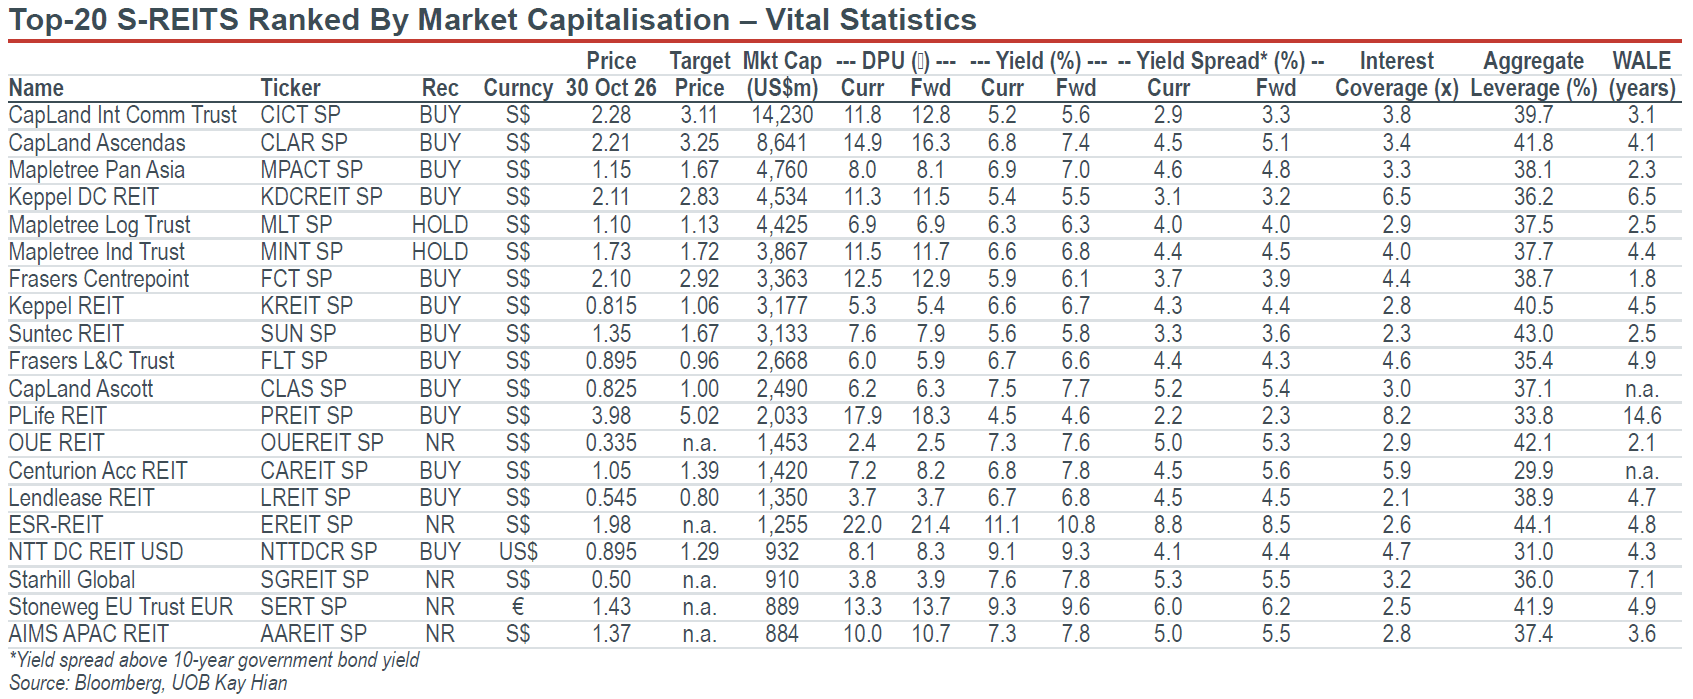
- An influx of safe-haven liquidity and low domestic interest rates have led to a record volume of transaction for commercial properties. Thus, S-REITs are supported by firm asset valuation and relatively low cost of debt.
- Maintain OVERWEIGHT. The S-REIT sector is a major laggard, and is thus likely to be more resilient and defensive. BUY CICT (Target: S$3.11), LREIT (Target: S$0.80), NTTDCR (Target: US$1.29) and UIBREIT (Target: S$1.16).
Analysis
- The FSTREI eased 1.1% in Oct 26, outperforming the STI's steep correction of 5.3%. Yield for 10-year Singapore government bonds dipped 23bp to 2.24%. US core PCE inflation rose 0.1ppt mom to 3.1% yoy in Sep 26.
- KREIT has agreed to acquire a 51% interest in Keppel South Central from its sponsor, Keppel Ltd, for S$626.2m, equivalent to S$2,350psf, and 3-4% below independent valuations. The acquisition provides an initial net property yield of 4.3% and is accretive to DPU by 2%. Sponsor Keppel Ltd will provide a guaranteed monthly income of S$2.23m for a period of five years. The guaranteed amount is based on 95% stabilised occupancy, average rent of S$11.15psf and an operating margin of 79%.
- KORE’s spec-suite strategy continues to support leasing momentum, with three of the six suites at The Post within The Plaza Buildings at Bellevue, Washington leased before completion and strong interest reported in the remaining units. The 15,400sf development follows three earlier full-floor spec-suite projects that achieved full occupancy, demonstrating demand for high-quality, move-in-ready offices among small and mid-sized occupiers. More than 35,000sf of additional spec suites are under development, providing further opportunities to improve occupancy.
- PREIT is acquiring three freehold nursing homes in Marseille and Velaux, France, from DomusVi for €38.8m (S$56.5m), with completion expected by Dec 26. Comprising 265 beds, the properties will be leased back to DomusVi under new 12-year leases with indexed rental escalations, strengthening income visibility and supporting organic rental growth. The acquisition will expand its French portfolio to 14 properties valued at S$234.3m, deepening its presence in its third key market. Management expects the transaction to be DPU-accretive. The total outlay of €43.4m (S$63.3m) will be fully debt-funded, lifting aggregate leverage from 33.8% to 35.3%.
Highlights
- An influx of safe-haven liquidity and low domestic interest rates have led to a record volume of transaction for commercial properties. Thus, S-REITs are supported by firm asset valuation and relatively low cost of debt.
- Maintain OVERWEIGHT. The S-REIT sector is a major laggard, and is thus likely to be more resilient and defensive. BUY CICT (Target: S$3.11), LREIT (Target: S$0.80), NTTDCR (Target: US$1.29) and UIBREIT (Target: S$1.16).
Analysis
- The FSTREI eased 1.1% in Oct 26, outperforming the STI's steep correction of 5.3%. Yield for 10-year Singapore government bonds dipped 23bp to 2.24%. US core PCE inflation rose 0.1ppt mom to 3.1% yoy in Sep 26.
- KREIT has agreed to acquire a 51% interest in Keppel South Central from its sponsor, Keppel Ltd, for S$626.2m, equivalent to S$2,350psf, and 3-4% below independent valuations. The acquisition provides an initial net property yield of 4.3% and is accretive to DPU by 2%. Sponsor Keppel Ltd will provide a guaranteed monthly income of S$2.23m for a period of five years. The guaranteed amount is based on 95% stabilised occupancy, average rent of S$11.15psf and an operating margin of 79%.
- KORE’s spec-suite strategy continues to support leasing momentum, with three of the six suites at The Post within The Plaza Buildings at Bellevue, Washington leased before completion and strong interest reported in the remaining units. The 15,400sf development follows three earlier full-floor spec-suite projects that achieved full occupancy, demonstrating demand for high-quality, move-in-ready offices among small and mid-sized occupiers. More than 35,000sf of additional spec suites are under development, providing further opportunities to improve occupancy.
- PREIT is acquiring three freehold nursing homes in Marseille and Velaux, France, from DomusVi for €38.8m (S$56.5m), with completion expected by Dec 26. Comprising 265 beds, the properties will be leased back to DomusVi under new 12-year leases with indexed rental escalations, strengthening income visibility and supporting organic rental growth. The acquisition will expand its French portfolio to 14 properties valued at S$234.3m, deepening its presence in its third key market. Management expects the transaction to be DPU-accretive. The total outlay of €43.4m (S$63.3m) will be fully debt-funded, lifting aggregate leverage from 33.8% to 35.3%.
OVERWEIGHT (Maintained)
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


Our latest research

26 Oct 2026
REITs: Data Centre REITs: Value Emerges After The Carnage

22 Oct 2026
REITs: Value Emerges With Expanded Yield Spread

20 Oct 2026