
Wealth Daily
Accenture Surges; Nike Slides After Results
Today’s Must-Know News
Overnight Markets
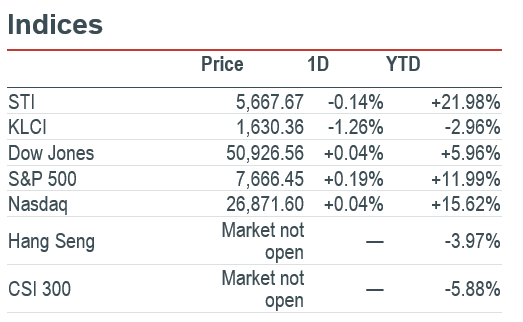
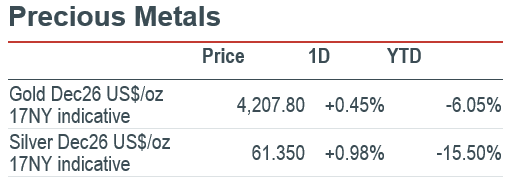
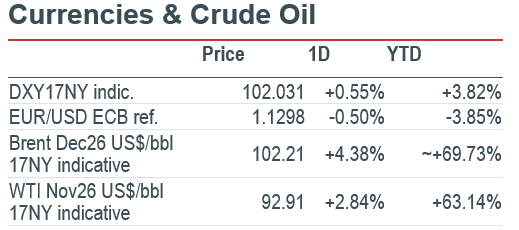
Market Movers: The S&P 500 rose 0.19% in the 1 Oct. US regular session as yields eased. Accenture (ACN US) jumped about 15.8% after forecasting FY27 revenue growth of 3–6% in local currency; the midpoint exceeded consensus of 3.9%. Quarterly bookings of US$22.17bn suggest clients still need help deploying AI, although pricing pressure persists. Mattel (MAT US) gained about 18.8% after Reuters confirmed reported takeover interest from Authentic Brands, potentially valuing it around US$6bn or more; no transaction is assured. After the close, Nike (NKE US) reported revenue of US$11.21bn against US$11.32bn expected and forecast a high-single-digit FY27 revenue decline. Its shares fell about 8.5% in after-hours trading by 07:05 SGT on 2 October, highlighting continued turnaround risk. (Accenture / Reuters / Reuters)
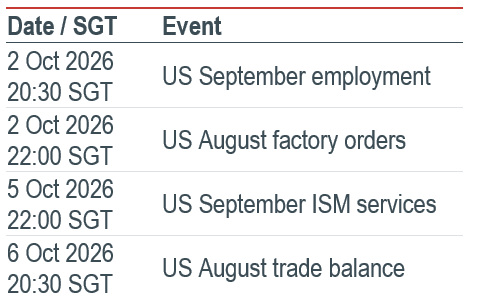
Macro: US manufacturing growth held up while input-cost pressure intensified. September's ISM manufacturing index was 54.5 versus 54.6 in August, but prices paid climbed to 77.9 from 71.1. Initial jobless claims fell 1,000 to 197,000 for the week ended 26 September, below the 200,000 consensus. Low layoffs support household income, while higher factory costs complicate the inflation outlook. The next test is September employment at 20:30 SGT on 2 October: Reuters' survey expects 90,000 payroll gains and unemployment of 4.1%. (ISM / Reuters)
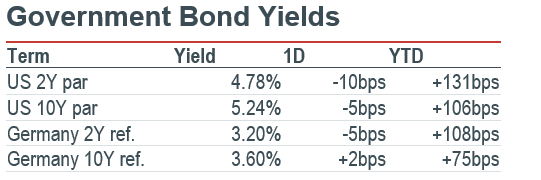
FICC: China's fuel-export halt lifted oil despite easing US yields. At the 1 October 17:00 New York indicative snapshot, equivalent to 05:00 SGT on 2 October, December Brent rose 4.38% to US$102.21/bbl and November WTI gained 2.84% to US$92.91/bbl versus the previous day's matched snapshots. At the 1 October official daily Treasury reference, the US 2-year par yield fell 10bps from 4.88% to 4.78%, while the 10-year fell 5bps from 5.29% to 5.24%. Higher fuel costs remain a risk to margins and purchasing power. (Reuters / US Treasury)
AI
Micron strengthens the AI memory demand signal. Micron Technology (MU US) gained about 3.0% versus Wednesday at the October 1 US close, its first session after September 30 results. Revenue reached US$54.23bn; next-quarter guidance is US$61.5bn, plus or minus US$1.5bn. Reuters highlighted US$32bn in customer commitments. Demand visibility supports expansion, although US$10.77bn of quarterly net capital expenditure raises execution requirements. (Micron / Reuters) Micron Technology (MU US) is our Trading Buy.
Accenture's outlook challenges AI disruption fears. Accenture (ACN US) rose about 15.8% versus Wednesday at the October 1 US close. Quarterly revenue of US$18.68bn exceeded its US$18.40bn guidance ceiling. Fiscal 2027 local-currency growth of 3–6% compares with roughly 3.9% expected. US$22.17bn in bookings supports the outlook, although pricing pressure persists. The results support consulting demand as enterprises implement AI. (Accenture / Reuters)
Google begins testing AI computing in orbit. Alphabet's Google (GOOGL US) launched its first Project Suncatcher prototype on October 1, advancing beyond the earlier announcement. NPR reported four TPU chips aboard, running Gemma in 15-minute bursts to manage heat, with testing intended for a year. This establishes a hardware milestone, but radiation, cooling and communications remain barriers to commercially useful space-based computing. (NPR / Google) Alphabet (GOOGL US) is our Trading Buy.
Americas
Nike's outlook extends the turnaround timetable. Nike (NKE US) fell about 8.5% after hours at 07:05 SGT on October 2 versus its October 1 regular close. Quarterly revenue of US$11.21bn missed US$11.32bn consensus; fiscal 2027 guidance implies a high-single-digit decline versus roughly 2% expected. China sales fell 26% in constant currency. Restructuring and distribution changes threaten recovery despite improved gross margin. (Nike / Reuters)
Tesla's European recovery remains uneven across markets. Tesla (TSLA US) posted September registration gains of 61.9% YoY in France, 38.4% in Sweden and 2.2% in Norway, Reuters reported on October 1 using national figures. Higher fuel prices, incentives and favourable comparisons helped demand. These country-level gains support volumes, but their uneven pace leaves uncertainty over the breadth and durability of a European recovery. (Reuters)
Mattel attracts a conditional takeover premium. Mattel (MAT US) gained 18.80% versus Wednesday at the October 1 US close after Reuters reported Authentic Brands Group's takeover interest. An approach above US$20 per share implies about US$6bn or more, versus the US$15.04 closing share price. Reported interest has not become a formal sale process; acceptance, financing and any eventual premium remain uncertain. (Reuters)
Paramount's financing raises the cash-flow hurdle. Paramount Skydance (PSKY US) priced US$41.4bn and EUR885mn of notes, plus US$8.5bn and EUR850mn of loans, at 09:02 SGT on October 1 for its Warner Bros. Discovery (WBD US) deal. Second-lien dollar coupons reach 9.125%. Shares fell about 9.6% versus Wednesday at the October 1 US close. Funding improves certainty but raises cash-generation requirements. (Paramount)
Constellation's Amazon contract supports nuclear reinvestment. Constellation Energy (CEG US) gained about 1.9% versus Wednesday at the October 1 US close following September 30's Amazon (AMZN US) agreement. The 20-year contract covers 690MW, including a planned 190MW uprate, at Calvert Cliffs and supports over US$3bn of investment. Revenue visibility improves funding, although licensing and construction remain important delivery risks. (Constellation / Reuters) Amazon (AMZN US) is our Core Recommendation.
RTX secures multi-year SM-6 production visibility. RTX (RTX US) announced at 05:20 SGT on October 2 an SM-6 interceptor contract worth up to US$24.4bn for Raytheon, spanning five years plus two option years. The company is expanding workforce, supplier capacity and automation to increase output. The award extends production visibility, but includes options and requires deliveries before becoming recognised revenue. (RTX / Cision)
Regeneron and Sanofi share immunology development risk. Regeneron (REGN US) and Sanofi (SAN.PA) announced four long-acting antibody programmes on October 1, with US$1bn upfront and up to US$7bn of milestones payable to Regeneron. Development costs and profits will be split equally. One asset is in Phase 1; three remain preclinical. Shared costs reduce risk, but the value depends on clinical and commercial progress. (Regeneron / Reuters)
McCormick's headline growth masks weak volumes. McCormick (MKC US) fell about 4.9% versus Wednesday at the October 1 US close after results. Sales rose 17.4% to US$2.02bn, but organic growth was 1.9%; pricing rose 2.2% while volumes slipped 0.3%. Adjusted EPS reached US$0.86; full-year guidance remained US$3.05–3.13. Acquisitions and pricing support growth, while subdued volumes limit evidence of a broader recovery. (McCormick / Reuters)
Rocket Lab extends its launch backlog. Rocket Lab (RKLB US) gained about 1.1% versus Wednesday at the October 1 US close following September 30's contract announcement. A Japanese radar-imaging customer ordered 20 further Electron launches for 2028–2031, taking its total to 47 and overall backlog above 100. The commitment supports long-term utilisation, although undisclosed terms limit assessment of future margins. (Rocket Lab)
Greater China
China’s export halt tightens fuel availability. Chinese refiners suspended October fuel exports beyond Hong Kong and Macau, Reuters reported on October 1, citing four sources. Beijing had not authorised shipments as the holiday began, despite relaxing restrictions in July. The duration remains unclear. The halt constrains replacement diesel and jet-fuel supply, exposing importing markets to tight inventories and stronger refining margins. (Reuters)
BYD’s overseas expansion offsets domestic pressure. BYD (1211.HK) reported September vehicle sales of 463,561 on October 1, up about 17.0% YoY. Overseas passenger-vehicle and pickup shipments rose about 153.9% to 179,877, according to Reuters. Nine-month sales reached 3,131,576. Exports support volume recovery, but profitability increasingly depends on overseas distribution costs and market access while competition continues to constrain domestic demand. (Reuters / CnEVPost)
Geely’s recovery still depends on exports. Geely Automobile (0175.HK) released September sales of 292,168 on October 1, up about 7.0% YoY. Exports rose about 162.4% to 106,685 but fell about 3.1% from August, while domestic sales declined about 20.2% YoY to 185,483. Headline growth masks continued pressure in China; sustaining overseas momentum matters as the domestic contraction gradually narrows. (CnEVPost / GMT Eight) Geely Automobile (0175.HK) is our Core Recommendation.
NIO’s brand mix tempers delivery growth. NIO (9866.HK) reported 37,408 September deliveries on October 1, up about 7.7% YoY, taking 3Q26 volume to 109,178, up about 25.4%. The NIO brand contributed 21,318 vehicles, while ONVO deliveries fell about 42.5% YoY to 8,763. Premium-brand demand supports volumes, but ONVO weakness shows expansion across price segments has yet to deliver uniformly stronger demand. (NIO / Benzinga)
XPeng’s quarterly recovery needs sustained volume. XPeng (9868.HK) announced 41,256 September deliveries on October 1, a reported 5% above August, taking 3Q26 deliveries to 118,390, a reported 15% rise QoQ. The L03 exceeded 10,000 monthly deliveries. Its charging network exceeded 4,000 stations across over 430 Chinese cities. Improving volumes support utilisation, while infrastructure returns depend on sustained demand across the vehicle range. (XPeng / RTTNews)
Asia ex. China
Korean memory demand strengthens the export case. Samsung Electronics (005930.KS) and SK Hynix (000660.KS) rose about 2.8% and 3.2% at Seoul’s October 1 close. September exports increased 83.5% YoY to US$120.94bn, with semiconductor shipments up 262.8% to US$60.30bn. The data reinforce memory demand; SK Hynix separately said no decision had been made on a Solidigm IPO, leaving financing structure and shareholder protection unresolved. (Reuters / MOTIR / Yonhap) SK Hynix (SKHY US) is our Trading Buy.
Jardine adds a healthcare earnings platform. Jardine Matheson (J36.SI) completed its I-MED Radiology acquisition on October 1. The Australian and New Zealand business operates 215 clinics, performs about 7mn procedures annually and supports over 2mn teleradiology patients. Shares closed Singapore’s October 1 session at US$54.88, up 2.93%. The deal adds a healthcare earnings platform whose contribution depends on integration and expansion. (Jardines / Stock Analysis)
Japan’s survey shows an uneven expansion. Japan’s October 1 Tankan showed large manufacturers’ sentiment rising to +24 from +22 in June, while the non-manufacturing index fell to +35 from +37. Both forecast softer December conditions. Companies’ three-year inflation expectation remained 2.6%. Manufacturing resilience supports policy normalisation, but weaker services confidence and stable inflation expectations reduce the urgency for another immediate rate increase. (BoJ / Reuters)
Temasek remains constructive on AI investment. Temasek’s North America head Jane Atherton reaffirmed its positive AI-spending outlook at an October 1 Reuters event, citing infrastructure funders’ strong balance sheets. Its earlier plan envisages AI exposure rising to as much as 15% of its portfolio over five years from about 6%. Higher financing costs increase the importance of realised investment returns. (Reuters)
Jardine distribution creates a shareholder election. Jardine Matheson Southeast Asia (C07.SI), formerly Jardine Cycle & Carriage, confirmed its new name and Toyota Motor (7203.T) share-distribution timetable on October 1. The record date is October 9 at 17:30 SGT. Eligible holders can elect shares or cash from selling entitlements; ordinary eligible holders giving no valid instruction retain shares held on their behalf. (Company / Company)
EMEA and Others
Capgemini gains on a stronger demand signal. Capgemini (CAP.PA) rose about 7.4% at the October 1 European close, leading the STOXX 600 after Accenture’s (ACN US) stronger annual revenue-growth outlook. European technology outperformed the broader selloff, highlighting stronger sentiment toward IT-services providers. Translating clients’ AI spending into durable bookings and margins remains the next company-specific test for sustaining the demand recovery. (Reuters / Stock Analysis)
UK banks face a fiscal-risk discount. At London’s October 1 close, NatWest (NWG.L) fell about 5.4%, HSBC (HSBA.L) lost about 4.0%, Barclays (BARC.L) declined about 4.1% and Lloyds (LLOY.L) dropped about 4.5%. Reuters linked the selloff to surging sovereign yields and budget concerns, including possible bank taxes. Higher lending yields offer limited protection if funding costs, credit stress or taxation weaken earnings. (Reuters / Reuters) HSBC (0005.HK) is our Core Recommendation.
Kone’s disposal plan defines the antitrust trade-off. Kone (KNEBV.HE) is preparing to sell most of TK Elevator’s European operations to address competition concerns, Reuters reported on October 1. The business generated about €2.5bn, or 27%, of TKE’s sales last year. Kone reaffirmed €700mn annual synergies for its previously agreed €29.4bn acquisition. Disposal terms will determine how much of those benefits survives regulatory remedies. (Reuters)
Bull expands Europe’s computing capacity. France’s state-owned Bull reopened its expanded Angers factory on October 1 after an €80mn investment, doubling monthly output from six to 12 supercomputer racks. Executives told Reuters capacity could reach 24 next year if demand warrants. Bull has won 15 of 18 EuroHPC tenders. Europe’s computing ambitions support expansion, but demand conversion remains central to utilisation. (Reuters)
Gamma loses a potential competing bidder. Waterland said on October 1 it would not bid for Gamma Communications (GAMA.L), ending discussions disclosed in August. Gamma fell about 2.3% at London’s October 1 close. The Rule 2.8 announcement restricts Waterland’s return, subject to stated exceptions including another bidder or changed circumstances. Reduced competitive tension narrows shareholders’ opportunity to capture a higher takeover price. (RNS / Stock Analysis)
Traders’ corner
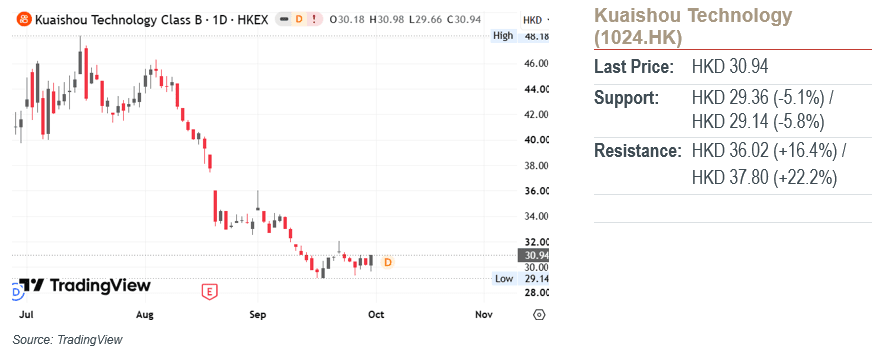
Our Technical View
Price executed a foundational bottoming sequence validated by the printing of a higher low, signaling early-stage trend reversal dynamics.
The RSI displays a bullish divergence warning and is sloping steeply upward out of deep oversold territory, confirming severe momentum exhaustion among sellers and a sharp reacceleration of buyer velocity.
- As long as price maintains its higher-low structural floor, we could expect a decisive upside penetration of the recent swing high, opening structural expansion toward higher supply targets.
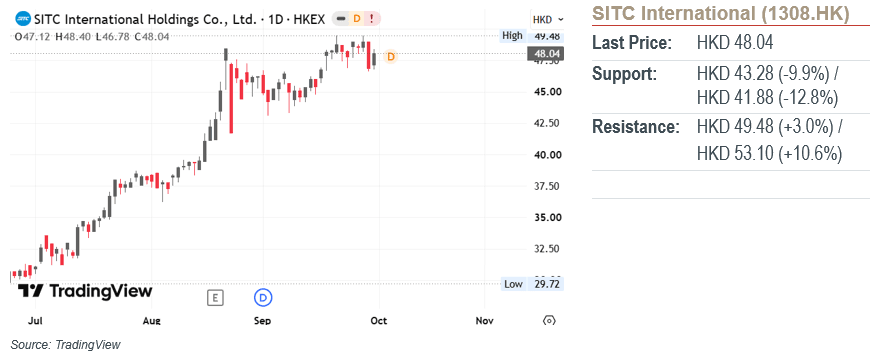
Our Technical View
Price executed a structural rejection and potential topping process capped along the primary overhead supply ceiling at HK$49.48, failing to establish continued upward acceptance and disrupting prior bullish swing sequence dynamics.
The RSI displays a pronounced bearish divergence warning and is sloping downward toward its neutral 50-midline, confirming a severe deceleration in trend velocity and decaying buy-side initiative.
The HK$46.60 threshold represents the key lower structural demand anchor; a decisive breach and daily close below HK$46.60 will confirm a complete structural pivot validation, confirming the macro peak at HK$49.48 and opening path-of-least-resistance dynamics for an accelerated bearish expansion toward lower support targets.
Market Movers: The S&P 500 rose 0.19% in the 1 Oct. US regular session as yields eased. Accenture (ACN US) jumped about 15.8% after forecasting FY27 revenue growth of 3–6% in local currency; the midpoint exceeded consensus of 3.9%. Quarterly bookings of US$22.17bn suggest clients still need help deploying AI, although pricing pressure persists. Mattel (MAT US) gained about 18.8% after Reuters confirmed reported takeover interest from Authentic Brands, potentially valuing it around US$6bn or more; no transaction is assured. After the close, Nike (NKE US) reported revenue of US$11.21bn against US$11.32bn expected and forecast a high-single-digit FY27 revenue decline. Its shares fell about 8.5% in after-hours trading by 07:05 SGT on 2 October, highlighting continued turnaround risk. (Accenture / Reuters / Reuters)
Macro: US manufacturing growth held up while input-cost pressure intensified. September's ISM manufacturing index was 54.5 versus 54.6 in August, but prices paid climbed to 77.9 from 71.1. Initial jobless claims fell 1,000 to 197,000 for the week ended 26 September, below the 200,000 consensus. Low layoffs support household income, while higher factory costs complicate the inflation outlook. The next test is September employment at 20:30 SGT on 2 October: Reuters' survey expects 90,000 payroll gains and unemployment of 4.1%. (ISM / Reuters)
FICC: China's fuel-export halt lifted oil despite easing US yields. At the 1 October 17:00 New York indicative snapshot, equivalent to 05:00 SGT on 2 October, December Brent rose 4.38% to US$102.21/bbl and November WTI gained 2.84% to US$92.91/bbl versus the previous day's matched snapshots. At the 1 October official daily Treasury reference, the US 2-year par yield fell 10bps from 4.88% to 4.78%, while the 10-year fell 5bps from 5.29% to 5.24%. Higher fuel costs remain a risk to margins and purchasing power. (Reuters / US Treasury)
AI
Micron strengthens the AI memory demand signal. Micron Technology (MU US) gained about 3.0% versus Wednesday at the October 1 US close, its first session after September 30 results. Revenue reached US$54.23bn; next-quarter guidance is US$61.5bn, plus or minus US$1.5bn. Reuters highlighted US$32bn in customer commitments. Demand visibility supports expansion, although US$10.77bn of quarterly net capital expenditure raises execution requirements. (Micron / Reuters) Micron Technology (MU US) is our Trading Buy.
Accenture's outlook challenges AI disruption fears. Accenture (ACN US) rose about 15.8% versus Wednesday at the October 1 US close. Quarterly revenue of US$18.68bn exceeded its US$18.40bn guidance ceiling. Fiscal 2027 local-currency growth of 3–6% compares with roughly 3.9% expected. US$22.17bn in bookings supports the outlook, although pricing pressure persists. The results support consulting demand as enterprises implement AI. (Accenture / Reuters)
Google begins testing AI computing in orbit. Alphabet's Google (GOOGL US) launched its first Project Suncatcher prototype on October 1, advancing beyond the earlier announcement. NPR reported four TPU chips aboard, running Gemma in 15-minute bursts to manage heat, with testing intended for a year. This establishes a hardware milestone, but radiation, cooling and communications remain barriers to commercially useful space-based computing. (NPR / Google) Alphabet (GOOGL US) is our Trading Buy.
Americas
Nike's outlook extends the turnaround timetable. Nike (NKE US) fell about 8.5% after hours at 07:05 SGT on October 2 versus its October 1 regular close. Quarterly revenue of US$11.21bn missed US$11.32bn consensus; fiscal 2027 guidance implies a high-single-digit decline versus roughly 2% expected. China sales fell 26% in constant currency. Restructuring and distribution changes threaten recovery despite improved gross margin. (Nike / Reuters)
Tesla's European recovery remains uneven across markets. Tesla (TSLA US) posted September registration gains of 61.9% YoY in France, 38.4% in Sweden and 2.2% in Norway, Reuters reported on October 1 using national figures. Higher fuel prices, incentives and favourable comparisons helped demand. These country-level gains support volumes, but their uneven pace leaves uncertainty over the breadth and durability of a European recovery. (Reuters)
Mattel attracts a conditional takeover premium. Mattel (MAT US) gained 18.80% versus Wednesday at the October 1 US close after Reuters reported Authentic Brands Group's takeover interest. An approach above US$20 per share implies about US$6bn or more, versus the US$15.04 closing share price. Reported interest has not become a formal sale process; acceptance, financing and any eventual premium remain uncertain. (Reuters)
Paramount's financing raises the cash-flow hurdle. Paramount Skydance (PSKY US) priced US$41.4bn and EUR885mn of notes, plus US$8.5bn and EUR850mn of loans, at 09:02 SGT on October 1 for its Warner Bros. Discovery (WBD US) deal. Second-lien dollar coupons reach 9.125%. Shares fell about 9.6% versus Wednesday at the October 1 US close. Funding improves certainty but raises cash-generation requirements. (Paramount)
Constellation's Amazon contract supports nuclear reinvestment. Constellation Energy (CEG US) gained about 1.9% versus Wednesday at the October 1 US close following September 30's Amazon (AMZN US) agreement. The 20-year contract covers 690MW, including a planned 190MW uprate, at Calvert Cliffs and supports over US$3bn of investment. Revenue visibility improves funding, although licensing and construction remain important delivery risks. (Constellation / Reuters) Amazon (AMZN US) is our Core Recommendation.
RTX secures multi-year SM-6 production visibility. RTX (RTX US) announced at 05:20 SGT on October 2 an SM-6 interceptor contract worth up to US$24.4bn for Raytheon, spanning five years plus two option years. The company is expanding workforce, supplier capacity and automation to increase output. The award extends production visibility, but includes options and requires deliveries before becoming recognised revenue. (RTX / Cision)
Regeneron and Sanofi share immunology development risk. Regeneron (REGN US) and Sanofi (SAN.PA) announced four long-acting antibody programmes on October 1, with US$1bn upfront and up to US$7bn of milestones payable to Regeneron. Development costs and profits will be split equally. One asset is in Phase 1; three remain preclinical. Shared costs reduce risk, but the value depends on clinical and commercial progress. (Regeneron / Reuters)
McCormick's headline growth masks weak volumes. McCormick (MKC US) fell about 4.9% versus Wednesday at the October 1 US close after results. Sales rose 17.4% to US$2.02bn, but organic growth was 1.9%; pricing rose 2.2% while volumes slipped 0.3%. Adjusted EPS reached US$0.86; full-year guidance remained US$3.05–3.13. Acquisitions and pricing support growth, while subdued volumes limit evidence of a broader recovery. (McCormick / Reuters)
Rocket Lab extends its launch backlog. Rocket Lab (RKLB US) gained about 1.1% versus Wednesday at the October 1 US close following September 30's contract announcement. A Japanese radar-imaging customer ordered 20 further Electron launches for 2028–2031, taking its total to 47 and overall backlog above 100. The commitment supports long-term utilisation, although undisclosed terms limit assessment of future margins. (Rocket Lab)
Greater China
China’s export halt tightens fuel availability. Chinese refiners suspended October fuel exports beyond Hong Kong and Macau, Reuters reported on October 1, citing four sources. Beijing had not authorised shipments as the holiday began, despite relaxing restrictions in July. The duration remains unclear. The halt constrains replacement diesel and jet-fuel supply, exposing importing markets to tight inventories and stronger refining margins. (Reuters)
BYD’s overseas expansion offsets domestic pressure. BYD (1211.HK) reported September vehicle sales of 463,561 on October 1, up about 17.0% YoY. Overseas passenger-vehicle and pickup shipments rose about 153.9% to 179,877, according to Reuters. Nine-month sales reached 3,131,576. Exports support volume recovery, but profitability increasingly depends on overseas distribution costs and market access while competition continues to constrain domestic demand. (Reuters / CnEVPost)
Geely’s recovery still depends on exports. Geely Automobile (0175.HK) released September sales of 292,168 on October 1, up about 7.0% YoY. Exports rose about 162.4% to 106,685 but fell about 3.1% from August, while domestic sales declined about 20.2% YoY to 185,483. Headline growth masks continued pressure in China; sustaining overseas momentum matters as the domestic contraction gradually narrows. (CnEVPost / GMT Eight) Geely Automobile (0175.HK) is our Core Recommendation.
NIO’s brand mix tempers delivery growth. NIO (9866.HK) reported 37,408 September deliveries on October 1, up about 7.7% YoY, taking 3Q26 volume to 109,178, up about 25.4%. The NIO brand contributed 21,318 vehicles, while ONVO deliveries fell about 42.5% YoY to 8,763. Premium-brand demand supports volumes, but ONVO weakness shows expansion across price segments has yet to deliver uniformly stronger demand. (NIO / Benzinga)
XPeng’s quarterly recovery needs sustained volume. XPeng (9868.HK) announced 41,256 September deliveries on October 1, a reported 5% above August, taking 3Q26 deliveries to 118,390, a reported 15% rise QoQ. The L03 exceeded 10,000 monthly deliveries. Its charging network exceeded 4,000 stations across over 430 Chinese cities. Improving volumes support utilisation, while infrastructure returns depend on sustained demand across the vehicle range. (XPeng / RTTNews)
Asia ex. China
Korean memory demand strengthens the export case. Samsung Electronics (005930.KS) and SK Hynix (000660.KS) rose about 2.8% and 3.2% at Seoul’s October 1 close. September exports increased 83.5% YoY to US$120.94bn, with semiconductor shipments up 262.8% to US$60.30bn. The data reinforce memory demand; SK Hynix separately said no decision had been made on a Solidigm IPO, leaving financing structure and shareholder protection unresolved. (Reuters / MOTIR / Yonhap) SK Hynix (SKHY US) is our Trading Buy.
Jardine adds a healthcare earnings platform. Jardine Matheson (J36.SI) completed its I-MED Radiology acquisition on October 1. The Australian and New Zealand business operates 215 clinics, performs about 7mn procedures annually and supports over 2mn teleradiology patients. Shares closed Singapore’s October 1 session at US$54.88, up 2.93%. The deal adds a healthcare earnings platform whose contribution depends on integration and expansion. (Jardines / Stock Analysis)
Japan’s survey shows an uneven expansion. Japan’s October 1 Tankan showed large manufacturers’ sentiment rising to +24 from +22 in June, while the non-manufacturing index fell to +35 from +37. Both forecast softer December conditions. Companies’ three-year inflation expectation remained 2.6%. Manufacturing resilience supports policy normalisation, but weaker services confidence and stable inflation expectations reduce the urgency for another immediate rate increase. (BoJ / Reuters)
Temasek remains constructive on AI investment. Temasek’s North America head Jane Atherton reaffirmed its positive AI-spending outlook at an October 1 Reuters event, citing infrastructure funders’ strong balance sheets. Its earlier plan envisages AI exposure rising to as much as 15% of its portfolio over five years from about 6%. Higher financing costs increase the importance of realised investment returns. (Reuters)
Jardine distribution creates a shareholder election. Jardine Matheson Southeast Asia (C07.SI), formerly Jardine Cycle & Carriage, confirmed its new name and Toyota Motor (7203.T) share-distribution timetable on October 1. The record date is October 9 at 17:30 SGT. Eligible holders can elect shares or cash from selling entitlements; ordinary eligible holders giving no valid instruction retain shares held on their behalf. (Company / Company)
EMEA and Others
Capgemini gains on a stronger demand signal. Capgemini (CAP.PA) rose about 7.4% at the October 1 European close, leading the STOXX 600 after Accenture’s (ACN US) stronger annual revenue-growth outlook. European technology outperformed the broader selloff, highlighting stronger sentiment toward IT-services providers. Translating clients’ AI spending into durable bookings and margins remains the next company-specific test for sustaining the demand recovery. (Reuters / Stock Analysis)
UK banks face a fiscal-risk discount. At London’s October 1 close, NatWest (NWG.L) fell about 5.4%, HSBC (HSBA.L) lost about 4.0%, Barclays (BARC.L) declined about 4.1% and Lloyds (LLOY.L) dropped about 4.5%. Reuters linked the selloff to surging sovereign yields and budget concerns, including possible bank taxes. Higher lending yields offer limited protection if funding costs, credit stress or taxation weaken earnings. (Reuters / Reuters) HSBC (0005.HK) is our Core Recommendation.
Kone’s disposal plan defines the antitrust trade-off. Kone (KNEBV.HE) is preparing to sell most of TK Elevator’s European operations to address competition concerns, Reuters reported on October 1. The business generated about €2.5bn, or 27%, of TKE’s sales last year. Kone reaffirmed €700mn annual synergies for its previously agreed €29.4bn acquisition. Disposal terms will determine how much of those benefits survives regulatory remedies. (Reuters)
Bull expands Europe’s computing capacity. France’s state-owned Bull reopened its expanded Angers factory on October 1 after an €80mn investment, doubling monthly output from six to 12 supercomputer racks. Executives told Reuters capacity could reach 24 next year if demand warrants. Bull has won 15 of 18 EuroHPC tenders. Europe’s computing ambitions support expansion, but demand conversion remains central to utilisation. (Reuters)
Gamma loses a potential competing bidder. Waterland said on October 1 it would not bid for Gamma Communications (GAMA.L), ending discussions disclosed in August. Gamma fell about 2.3% at London’s October 1 close. The Rule 2.8 announcement restricts Waterland’s return, subject to stated exceptions including another bidder or changed circumstances. Reduced competitive tension narrows shareholders’ opportunity to capture a higher takeover price. (RNS / Stock Analysis)
Traders’ corner
Our Technical View
Price executed a foundational bottoming sequence validated by the printing of a higher low, signaling early-stage trend reversal dynamics.
The RSI displays a bullish divergence warning and is sloping steeply upward out of deep oversold territory, confirming severe momentum exhaustion among sellers and a sharp reacceleration of buyer velocity.
- As long as price maintains its higher-low structural floor, we could expect a decisive upside penetration of the recent swing high, opening structural expansion toward higher supply targets.
Our Technical View
Price executed a structural rejection and potential topping process capped along the primary overhead supply ceiling at HK$49.48, failing to establish continued upward acceptance and disrupting prior bullish swing sequence dynamics.
The RSI displays a pronounced bearish divergence warning and is sloping downward toward its neutral 50-midline, confirming a severe deceleration in trend velocity and decaying buy-side initiative.
The HK$46.60 threshold represents the key lower structural demand anchor; a decisive breach and daily close below HK$46.60 will confirm a complete structural pivot validation, confirming the macro peak at HK$49.48 and opening path-of-least-resistance dynamics for an accelerated bearish expansion toward lower support targets.
Disclosures and disclaimers
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


