

Wealth Daily
Microsoft Bets Big on Custom AI Chips
Today’s Must-Know News
Overnight Markets
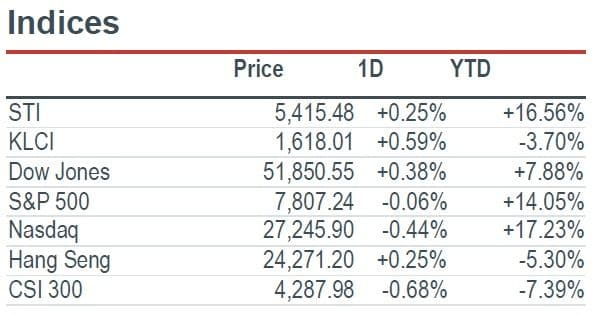
Market Movers: The S&P 500 fell 0.06% in the Monday, 12 October US session, while AI launches supported two major platforms. Meta Platforms (META US) rose 3.38% after unveiling Muse Wonder and Muse Wonder Full, intensifying competition in frontier models. Microsoft (MSFT US) gained 1.14% after announcing plans to expand its Maia systems to multiple gigawatts from 2027. Microsoft expects 40% more tokens per megawatt than leading GPU systems; a company estimate. Maia 300 also targets up to seven times the token throughput per rack of Maia 200. Custom chips could improve AI margins, but deployment costs and demand will determine returns. The gains contrasted with a 2.67% fall in the Philadelphia semiconductor index. (Reuters / Meta / Microsoft)
Macro: The IMF's Georgieva said AI investment is keeping global growth around 3%, despite the energy supply shock. At the Bangkok meetings on 12 October, she estimated potential growth gains of 0.5–1 percentage point for advanced Asian economies and 0.2–0.8 point for emerging Asia. These are potential contributions, not fresh country forecasts. Hardware exporters stand to benefit; productivity gains will determine longer-term returns. (Reuters)
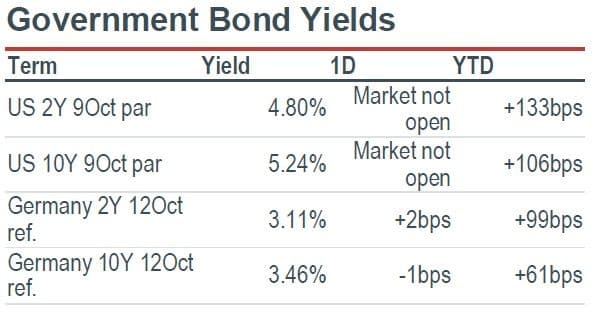
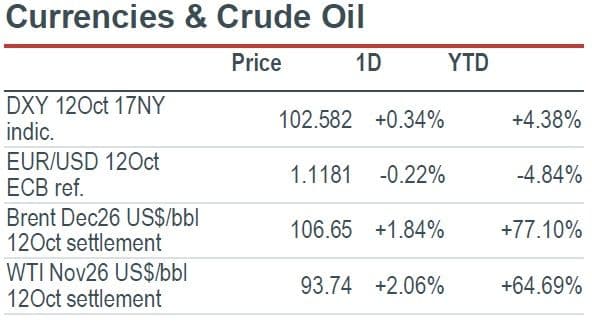
FICC: December Brent settled up 1.84% at US$106.65/bbl on 12 October; November WTI rose 2.06% to US$93.74. Saudi supply risks outweighed prospective diesel relief. Goldman raised its December Brent forecast to US$90 from US$85, still below the latest settlement, highlighting scope for a lower risk premium if supply normalises. Higher fuel costs remain a threat to transport margins and inflation. The US Treasury market was closed for Columbus Day; its latest official par yields are dated 9 October. (Reuters / Federal Reserve) Meta Platforms (META US) and Microsoft (MSFT US) are our Core Recommendations.
AI
- Meta Platforms (META US) rose 3.38% to US$742.96 after launching Muse Wonder and Muse Wonder Full. Muse Wonder is available through Meta’s API and coding service; Wonder Full is for coding subscribers. Active Memory retains context across conversations, while Active Focus supports persistent tasks. The launch broadens Meta’s paid AI offering against OpenAI and Anthropic. (Meta / Reuters / Market data)
Meta Platforms (META US) is our Core Recommendation.
- Microsoft (MSFT US) gained 1.14% to US$541.15 on plans for multi-gigawatt Maia deployments from 2027. Maia 300 is intended to become the primary inference system for Microsoft products. The company claims 40% more tokens per megawatt than leading GPU systems and up to seven times Maia 200 rack throughput. Those estimates highlight custom silicon’s role in reducing inference costs. (Microsoft / Reuters / Market data)
Microsoft (MSFT US) is our Core Recommendation.
- Nvidia (NVDA US) contributed Vera Rubin rack and compute-tray designs to the Open Compute Project. Announced on 12 October, its MGX 1.2 architecture supports racks up to 250kW, extending liquid cooling and standardising power interfaces. Meta will adopt Spectrum-6 Ethernet switches with 102.4Tb/s capacity. The initiatives strengthen Nvidia’s infrastructure ecosystem even as its shares fell 1.29% to US$226.32 during the session. (Nvidia / Market data)
Nvidia (NVDA US) is our Core Recommendation.
- Broadcom (AVGO US) chief executive Hock Tan identified capital as AI expansion’s biggest constraint on Monday. Speaking in Singapore, he said the industry was overcoming memory and wafer shortages. He also cautioned against speculative AI investment, according to Bloomberg. Broadcom shares fell 1.88% to US$354.73 in the 12 October US session. The remarks focus attention on funding and returns. (Reuters / Bloomberg / Market data)
Broadcom (AVGO US) is our Core Recommendation.
Americas
- Cisco Systems (CSCO US) announced Silicon One production deployments and a new networking chip on 12 October. Microsoft and Alibaba are deploying its 51.2Tb/s P200, while initial G300 systems offer 102.4Tb/s switching. The new G302 supports 1.6Tb/s optics and liquid cooling, with shipments planned by year-end. In the 12 October US session, shares fell 2.58% to US$115.34 despite advances targeting AI network capacity. (Cisco / Market data)
- In the 12 October US session, Lumentum (LITE US) fell 9.78% to US$995.41; Ciena (CIEN US) lost 9.95%. Lumentum separately announced an AI rack connectivity demonstration with Astera Labs and Corning. Its 1060nm optical platform transports PCIe traffic through fibre to address reach, density and power constraints. The demonstration is a development milestone; it did not establish a negative corporate catalyst for the optical-sector selloff. (Lumentum / Stock Analysis / Market data)
Lumentum (LITE US) is our Trading Buy.
- Salesforce (CRM US) rose 2.09% to US$233.92 in the 12 October US session after Bank of America upgraded it from Underperform to Buy. The bank raised its target to US$285 from US$160, citing its enterprise AI position. Salesforce also agreed to acquire Loops, whose analytics agents will support Tableau monitoring and alerts. Terms were undisclosed, leaving acquisition economics unquantified as the strategy shifts toward autonomous enterprise analysis. (Investing.com / Salesforce / Market data)
- Bristol Myers Squibb (BMY US) fell 2.60% to US$57.58 in the 12 October US session after mixed lung-drug results and a cancer-trial success. Admilparant’s 60mg dose met the Phase 3 ALOFT-IPF lung-function endpoint at 52 weeks, but 120mg did not. Separately, RYZ101 improved progression-free survival in advanced neuroendocrine tumours. Both programmes support potential submissions; detailed efficacy and safety data remain important to commercial prospects. (Bristol Myers Squibb / Bristol Myers Squibb / Market data)
- Chipotle Mexican Grill (CMG US) fell 3.77% to US$30.40 in the 12 October US session after Starbucks denied planning to buy the restaurant chain. The explicit Monday statement reversed acquisition speculation following last week’s report of preliminary discussions. Starbucks said it was concentrating on its own turnaround; Chipotle declined to comment. No transaction terms or timetable are confirmed, keeping attention on standalone operating performance. (Reuters / Market data)
Greater China
- Tencent's financing plan puts capital spending in focus. Tencent (0700.HK) proposed an international notes issue on 12 October, with size and terms unconfirmed. Its filing showed first-half capital expenditure of RMB96.3bn, up 109.8% YoY, covering infrastructure and other assets. The proposal underscores expansion's cash demands; assessing returns alongside financing costs matters, while the spending figure cannot be treated as AI investment alone. (Tencent)
Tencent (0700.HK) is our Core Recommendation.
- SERES rallies with its battery partnership in focus. SERES (9927.HK) rose 15.22% to HK$38.92 on 12 October after its 10 October agreement with CATL. The partners will expand battery manufacturing, charging cooperation and overseas development; all AITO models will continue using CATL batteries. The agreement improves supply-chain visibility, although it alone does not establish future vehicle margins, export demand or the returns on additional manufacturing capacity. (SERES / NewTimeSpace / Market data)
- China's domestic car contraction deepens as exports surge. Passenger-car sales at home fell 28.1% YoY to 1.63m in September, the CPCA reported on 12 October, marking twelve consecutive monthly declines. Exports rose 73.2% YoY to 923,000 vehicles. The divergence shifts attention from headline factory volumes to domestic demand, overseas margins and trade exposure; export strength offers relief, but does not demonstrate a recovery in Chinese consumer purchases. (Reuters)
Asia ex. China
- Korean chipmakers extend the AI valuation reset. Samsung Electronics (005930 KS) and SK Hynix (000660 KS) fell 4.39% and 4.52% respectively on 12 October as Seoul reopened after a long weekend. The KOSPI lost 3.65%, with Reuters citing concern over returns on AI spending. The selloff makes earnings conversion and customer funding more important tests of the memory investment cycle and its valuations. (Reuters / Market data / Market data)
SK Hynix (SKHY US) is our Trading Buy.
- HCLTech's AI growth outpaces its wider business. HCLTech (HCLTECH IN) reported second-quarter FY2027 revenue of INR356.2bn on 12 October, up 11.5% YoY. Overall constant-currency growth was 2.6%, while advanced-AI revenue reached US$219m, up 78% YoY in constant currency. The gap shows stronger monetisation within AI, but that activity remains a modest share of sales; broader enterprise demand and delivery margins still determine the group's earnings trajectory. (HCLTech)
- Singapore's cash-market activity strengthens SGX's revenue base. Singapore Exchange (S68 SG) reported September securities turnover of S$42.2bn on 12 October, up 27% YoY, while derivatives volume fell 2% YoY to 29.8m contracts. Shares closed 2.99% higher at S$21.35. The cash-market improvement supports transaction-fee momentum, although the contrast with derivatives shows why investors should assess the trading mix and fee yield alongside aggregate activity when judging earnings durability. (SGX / Market data)
- India's inflation acceleration raises the tightening stakes. September consumer inflation rose to 5.54% YoY from August's 4.83%, data released on 12 October showed. Food inflation climbed to 7.74% and core inflation to 4.3%, both measured annually. The release follows the RBI's rate increase last week. Broader price pressure reinforces the case for further tightening, putting borrowing costs, household purchasing power and interest-sensitive equity valuations under closer scrutiny. (Indian Express)
EMEA and Others
- LVMH's fashion contraction weakens the luxury recovery. LVMH (MC FP) disclosed third-quarter revenue of EUR18.5bn on 12 October, up 1.2% YoY on a reported basis and 1% organically. Fashion and leather goods contracted 5% organically, while selective retailing grew 8%. The uneven mix makes a luxury recovery harder to establish: strength outside the flagship division offers support, but investors need evidence that core fashion demand is stabilising. (LVMH)
- Volkswagen's delivery decline exposes persistent China pressure. Volkswagen (VOW3 GR) said on 12 October that third-quarter global deliveries fell 14.3% YoY to approximately 1.89m vehicles, with China down 38.5%. Nine-month deliveries were just over 6m, down 9% YoY. The sharper quarterly contraction increases the importance of production discipline and market mix; weaker volumes can pressure capacity utilisation even before pricing and product-development costs enter the earnings equation. (dpa via Yahoo Finance)
- European banks support a broader market rebound. The STOXX 600 closed 0.65% higher on 12 October, with banks gaining about 1.5% and Spain's IBEX advancing 1.33%. Telecommunications lagged, falling 0.54%. Reuters described banking strength as cushioning pressure from oil prices. This matters for regional positioning: financials supported the benchmark, while sector dispersion makes earnings resilience and sensitivity to financing conditions more useful guides than the index's direction alone. (Reuters)
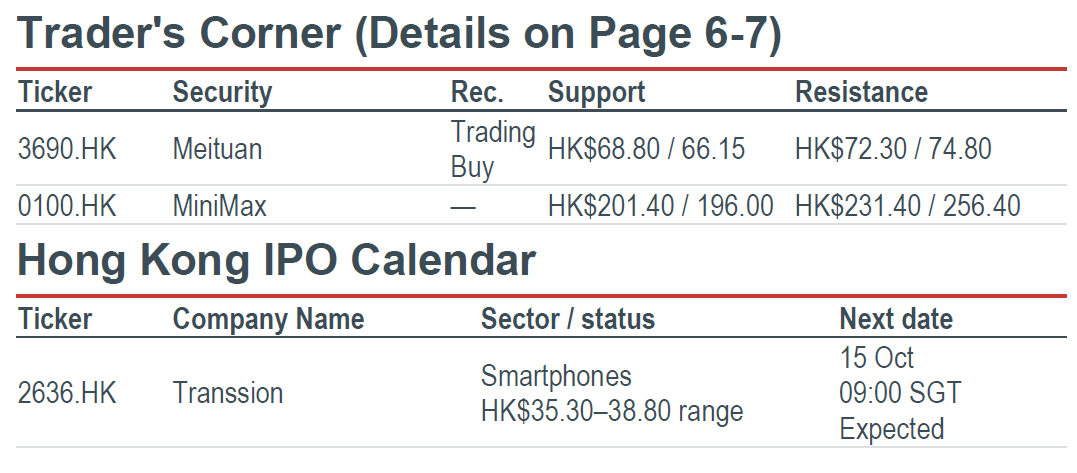
Traders' Corner
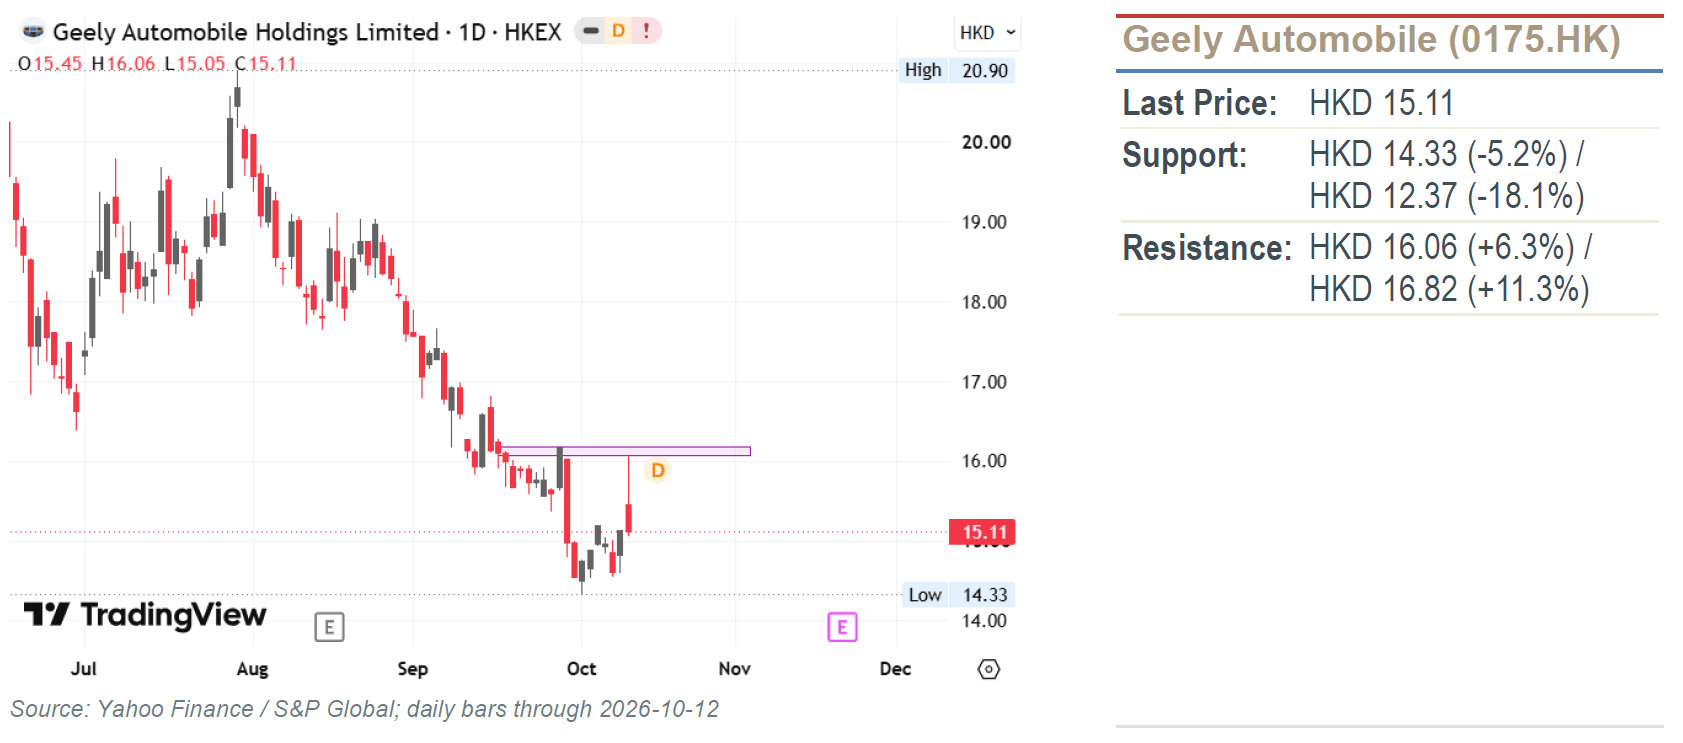
Our Technical View
- Price was capped by its previous high resistance zone, confirming robust overhead supply.
- The RSI remains in bearish territory and continues to slope downward with negative velocity, confirming expanding downward momentum velocity.
- As long as price remains underneath this Shooting Star high resistance, we see continued downward expansion toward lower support.
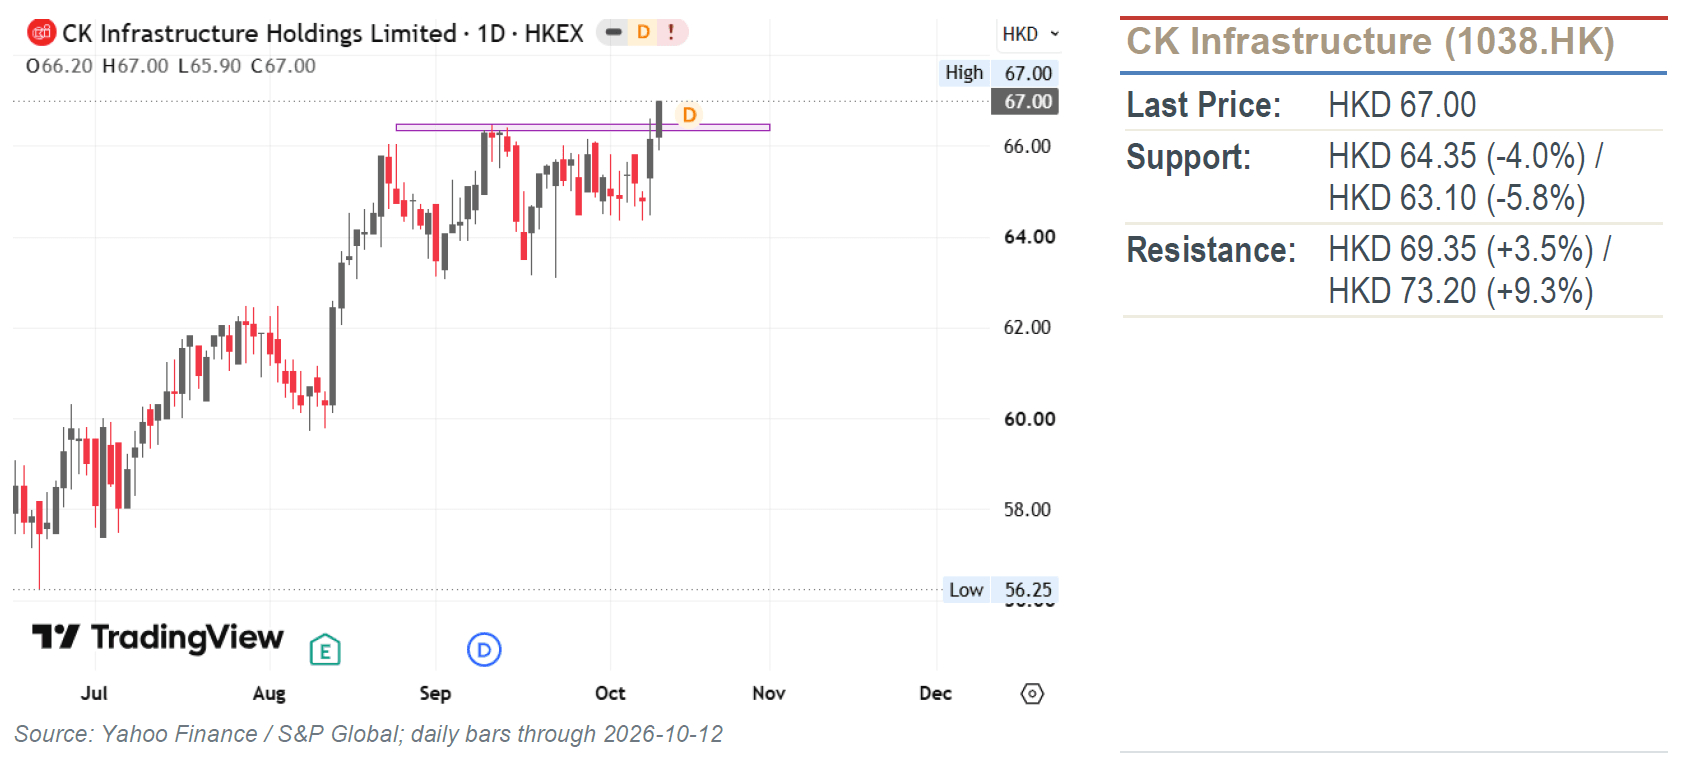
Our Technical View
- Price penetrated its prior swing peak and printed a new all-time high.
- The RSI remains in strong bullish territory and continues to slope upward with positive velocity, reflecting sustained momentum acceleration without immediate signs of momentum exhaustion or divergence.
- As long as price defends this newly converted all-time high support baseline, we see continued upward expansion into unchartered price territory.
Market Movers: The S&P 500 fell 0.06% in the Monday, 12 October US session, while AI launches supported two major platforms. Meta Platforms (META US) rose 3.38% after unveiling Muse Wonder and Muse Wonder Full, intensifying competition in frontier models. Microsoft (MSFT US) gained 1.14% after announcing plans to expand its Maia systems to multiple gigawatts from 2027. Microsoft expects 40% more tokens per megawatt than leading GPU systems; a company estimate. Maia 300 also targets up to seven times the token throughput per rack of Maia 200. Custom chips could improve AI margins, but deployment costs and demand will determine returns. The gains contrasted with a 2.67% fall in the Philadelphia semiconductor index. (Reuters / Meta / Microsoft)
Macro: The IMF's Georgieva said AI investment is keeping global growth around 3%, despite the energy supply shock. At the Bangkok meetings on 12 October, she estimated potential growth gains of 0.5–1 percentage point for advanced Asian economies and 0.2–0.8 point for emerging Asia. These are potential contributions, not fresh country forecasts. Hardware exporters stand to benefit; productivity gains will determine longer-term returns. (Reuters)
FICC: December Brent settled up 1.84% at US$106.65/bbl on 12 October; November WTI rose 2.06% to US$93.74. Saudi supply risks outweighed prospective diesel relief. Goldman raised its December Brent forecast to US$90 from US$85, still below the latest settlement, highlighting scope for a lower risk premium if supply normalises. Higher fuel costs remain a threat to transport margins and inflation. The US Treasury market was closed for Columbus Day; its latest official par yields are dated 9 October. (Reuters / Federal Reserve) Meta Platforms (META US) and Microsoft (MSFT US) are our Core Recommendations.
AI
- Meta Platforms (META US) rose 3.38% to US$742.96 after launching Muse Wonder and Muse Wonder Full. Muse Wonder is available through Meta’s API and coding service; Wonder Full is for coding subscribers. Active Memory retains context across conversations, while Active Focus supports persistent tasks. The launch broadens Meta’s paid AI offering against OpenAI and Anthropic. (Meta / Reuters / Market data)
Meta Platforms (META US) is our Core Recommendation.
- Microsoft (MSFT US) gained 1.14% to US$541.15 on plans for multi-gigawatt Maia deployments from 2027. Maia 300 is intended to become the primary inference system for Microsoft products. The company claims 40% more tokens per megawatt than leading GPU systems and up to seven times Maia 200 rack throughput. Those estimates highlight custom silicon’s role in reducing inference costs. (Microsoft / Reuters / Market data)
Microsoft (MSFT US) is our Core Recommendation.
- Nvidia (NVDA US) contributed Vera Rubin rack and compute-tray designs to the Open Compute Project. Announced on 12 October, its MGX 1.2 architecture supports racks up to 250kW, extending liquid cooling and standardising power interfaces. Meta will adopt Spectrum-6 Ethernet switches with 102.4Tb/s capacity. The initiatives strengthen Nvidia’s infrastructure ecosystem even as its shares fell 1.29% to US$226.32 during the session. (Nvidia / Market data)
Nvidia (NVDA US) is our Core Recommendation.
- Broadcom (AVGO US) chief executive Hock Tan identified capital as AI expansion’s biggest constraint on Monday. Speaking in Singapore, he said the industry was overcoming memory and wafer shortages. He also cautioned against speculative AI investment, according to Bloomberg. Broadcom shares fell 1.88% to US$354.73 in the 12 October US session. The remarks focus attention on funding and returns. (Reuters / Bloomberg / Market data)
Broadcom (AVGO US) is our Core Recommendation.
Americas
- Cisco Systems (CSCO US) announced Silicon One production deployments and a new networking chip on 12 October. Microsoft and Alibaba are deploying its 51.2Tb/s P200, while initial G300 systems offer 102.4Tb/s switching. The new G302 supports 1.6Tb/s optics and liquid cooling, with shipments planned by year-end. In the 12 October US session, shares fell 2.58% to US$115.34 despite advances targeting AI network capacity. (Cisco / Market data)
- In the 12 October US session, Lumentum (LITE US) fell 9.78% to US$995.41; Ciena (CIEN US) lost 9.95%. Lumentum separately announced an AI rack connectivity demonstration with Astera Labs and Corning. Its 1060nm optical platform transports PCIe traffic through fibre to address reach, density and power constraints. The demonstration is a development milestone; it did not establish a negative corporate catalyst for the optical-sector selloff. (Lumentum / Stock Analysis / Market data)
Lumentum (LITE US) is our Trading Buy.
- Salesforce (CRM US) rose 2.09% to US$233.92 in the 12 October US session after Bank of America upgraded it from Underperform to Buy. The bank raised its target to US$285 from US$160, citing its enterprise AI position. Salesforce also agreed to acquire Loops, whose analytics agents will support Tableau monitoring and alerts. Terms were undisclosed, leaving acquisition economics unquantified as the strategy shifts toward autonomous enterprise analysis. (Investing.com / Salesforce / Market data)
- Bristol Myers Squibb (BMY US) fell 2.60% to US$57.58 in the 12 October US session after mixed lung-drug results and a cancer-trial success. Admilparant’s 60mg dose met the Phase 3 ALOFT-IPF lung-function endpoint at 52 weeks, but 120mg did not. Separately, RYZ101 improved progression-free survival in advanced neuroendocrine tumours. Both programmes support potential submissions; detailed efficacy and safety data remain important to commercial prospects. (Bristol Myers Squibb / Bristol Myers Squibb / Market data)
- Chipotle Mexican Grill (CMG US) fell 3.77% to US$30.40 in the 12 October US session after Starbucks denied planning to buy the restaurant chain. The explicit Monday statement reversed acquisition speculation following last week’s report of preliminary discussions. Starbucks said it was concentrating on its own turnaround; Chipotle declined to comment. No transaction terms or timetable are confirmed, keeping attention on standalone operating performance. (Reuters / Market data)
Greater China
- Tencent's financing plan puts capital spending in focus. Tencent (0700.HK) proposed an international notes issue on 12 October, with size and terms unconfirmed. Its filing showed first-half capital expenditure of RMB96.3bn, up 109.8% YoY, covering infrastructure and other assets. The proposal underscores expansion's cash demands; assessing returns alongside financing costs matters, while the spending figure cannot be treated as AI investment alone. (Tencent)
Tencent (0700.HK) is our Core Recommendation.
- SERES rallies with its battery partnership in focus. SERES (9927.HK) rose 15.22% to HK$38.92 on 12 October after its 10 October agreement with CATL. The partners will expand battery manufacturing, charging cooperation and overseas development; all AITO models will continue using CATL batteries. The agreement improves supply-chain visibility, although it alone does not establish future vehicle margins, export demand or the returns on additional manufacturing capacity. (SERES / NewTimeSpace / Market data)
- China's domestic car contraction deepens as exports surge. Passenger-car sales at home fell 28.1% YoY to 1.63m in September, the CPCA reported on 12 October, marking twelve consecutive monthly declines. Exports rose 73.2% YoY to 923,000 vehicles. The divergence shifts attention from headline factory volumes to domestic demand, overseas margins and trade exposure; export strength offers relief, but does not demonstrate a recovery in Chinese consumer purchases. (Reuters)
Asia ex. China
- Korean chipmakers extend the AI valuation reset. Samsung Electronics (005930 KS) and SK Hynix (000660 KS) fell 4.39% and 4.52% respectively on 12 October as Seoul reopened after a long weekend. The KOSPI lost 3.65%, with Reuters citing concern over returns on AI spending. The selloff makes earnings conversion and customer funding more important tests of the memory investment cycle and its valuations. (Reuters / Market data / Market data)
SK Hynix (SKHY US) is our Trading Buy.
- HCLTech's AI growth outpaces its wider business. HCLTech (HCLTECH IN) reported second-quarter FY2027 revenue of INR356.2bn on 12 October, up 11.5% YoY. Overall constant-currency growth was 2.6%, while advanced-AI revenue reached US$219m, up 78% YoY in constant currency. The gap shows stronger monetisation within AI, but that activity remains a modest share of sales; broader enterprise demand and delivery margins still determine the group's earnings trajectory. (HCLTech)
- Singapore's cash-market activity strengthens SGX's revenue base. Singapore Exchange (S68 SG) reported September securities turnover of S$42.2bn on 12 October, up 27% YoY, while derivatives volume fell 2% YoY to 29.8m contracts. Shares closed 2.99% higher at S$21.35. The cash-market improvement supports transaction-fee momentum, although the contrast with derivatives shows why investors should assess the trading mix and fee yield alongside aggregate activity when judging earnings durability. (SGX / Market data)
- India's inflation acceleration raises the tightening stakes. September consumer inflation rose to 5.54% YoY from August's 4.83%, data released on 12 October showed. Food inflation climbed to 7.74% and core inflation to 4.3%, both measured annually. The release follows the RBI's rate increase last week. Broader price pressure reinforces the case for further tightening, putting borrowing costs, household purchasing power and interest-sensitive equity valuations under closer scrutiny. (Indian Express)
EMEA and Others
- LVMH's fashion contraction weakens the luxury recovery. LVMH (MC FP) disclosed third-quarter revenue of EUR18.5bn on 12 October, up 1.2% YoY on a reported basis and 1% organically. Fashion and leather goods contracted 5% organically, while selective retailing grew 8%. The uneven mix makes a luxury recovery harder to establish: strength outside the flagship division offers support, but investors need evidence that core fashion demand is stabilising. (LVMH)
- Volkswagen's delivery decline exposes persistent China pressure. Volkswagen (VOW3 GR) said on 12 October that third-quarter global deliveries fell 14.3% YoY to approximately 1.89m vehicles, with China down 38.5%. Nine-month deliveries were just over 6m, down 9% YoY. The sharper quarterly contraction increases the importance of production discipline and market mix; weaker volumes can pressure capacity utilisation even before pricing and product-development costs enter the earnings equation. (dpa via Yahoo Finance)
- European banks support a broader market rebound. The STOXX 600 closed 0.65% higher on 12 October, with banks gaining about 1.5% and Spain's IBEX advancing 1.33%. Telecommunications lagged, falling 0.54%. Reuters described banking strength as cushioning pressure from oil prices. This matters for regional positioning: financials supported the benchmark, while sector dispersion makes earnings resilience and sensitivity to financing conditions more useful guides than the index's direction alone. (Reuters)
Traders' Corner
Our Technical View
- Price was capped by its previous high resistance zone, confirming robust overhead supply.
- The RSI remains in bearish territory and continues to slope downward with negative velocity, confirming expanding downward momentum velocity.
- As long as price remains underneath this Shooting Star high resistance, we see continued downward expansion toward lower support.
Our Technical View
- Price penetrated its prior swing peak and printed a new all-time high.
- The RSI remains in strong bullish territory and continues to slope upward with positive velocity, reflecting sustained momentum acceleration without immediate signs of momentum exhaustion or divergence.
- As long as price defends this newly converted all-time high support baseline, we see continued upward expansion into unchartered price territory.
Disclosures and disclaimers
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


