

Company Coverage
KB Bukopin (BBKP IJ): Operating Recovery Gains Traction; Legacy NPLs Remain A Hurdle
NOT RATED
Current price:
Target price:
Upside:
Rp41
n.a.
n.a.
Analyst
Highlights
- Earnings recovery supported by lower funding costs. NII rose 54.4% yoy, supported by a 100bp reduction in CoF, although profitability remains modest.
- Legacy NPL resolution remains the key challenge. LaR improved to 21.9%, but gross NPL remained elevated at 10.0%, with further clean-up potentially affecting earnings and capital.
- Valuation rerating hinges on sustainable profitability. Trading at 0.91x P/B, BBKP needs stronger capital generation and further asset-quality improvement to justify a higher valuation.
Analysis
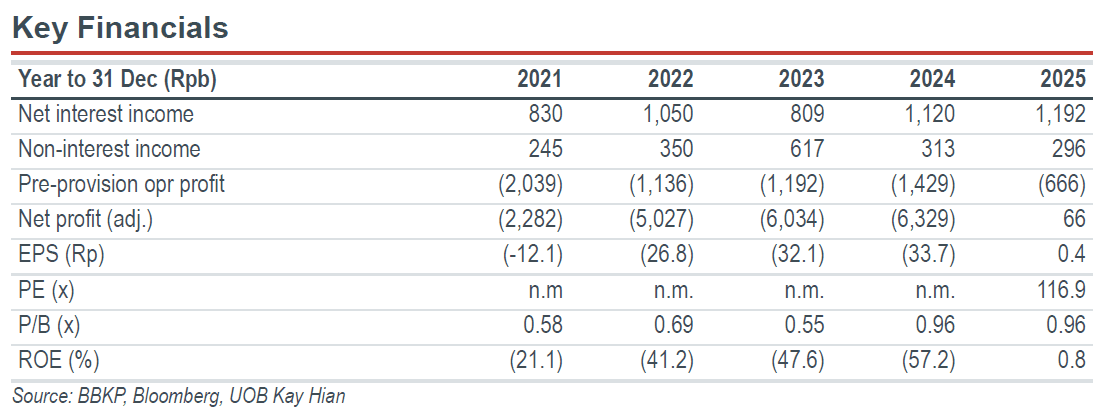
- Earnings recovery gains traction, supported by lower funding costs. KB Bank (BBKP) booked a bank-only net profit of Rp6b in 1H26, following a net profit of Rp13b in full-year 2025, marking a significant turnaround from historical losses. Net interest income (NII) rose 54.4% yoy to Rp695b, while pre-provision operating profit (PPOP) improved 43.5% yoy. Net interest margin (NIM) expanded 70bp yoy to 2.0%, largely supported by a 100bp reduction in cost of funds (CoF) to 4.3% while loan yield was relatively stable at 8.2% in 1H26. Deposits grew 12.4% yoy, with CASA increasing 15.2% yoy, lifting the CASA ratio to 32.3%. While operating performance is improving, earnings remain modest, limiting the bank’s capacity to absorb additional credit costs.
- Asset quality improves, but legacy loans remain a significant overhang. BBKP's loan-at-risk (LaR) ratio declined to 21.9% in Jun 26 from 24.4% in Jun 25, while normal loans (good loans) grew 8.1% yoy, accounting for nearly 80% of total loans (2021: 35%). However, gross NPL remained elevated at 10.0%, suggesting that legacy asset-quality issues have yet to be fully resolved. Management acknowledged that much of the historical LaR reduction was achieved through write-offs and asset swaps. BBKP continues to resolve legacy loans through organic collections, targeting Rp3t annually following Rp2.8t in 2025 and Rp1.4t in 1H26. Management is prioritising this approach to preserve capital, while discussing the possibility of a larger NPL clean-up in 2027, although no firm plan has been announced.
Highlights
- Earnings recovery supported by lower funding costs. NII rose 54.4% yoy, supported by a 100bp reduction in CoF, although profitability remains modest.
- Legacy NPL resolution remains the key challenge. LaR improved to 21.9%, but gross NPL remained elevated at 10.0%, with further clean-up potentially affecting earnings and capital.
- Valuation rerating hinges on sustainable profitability. Trading at 0.91x P/B, BBKP needs stronger capital generation and further asset-quality improvement to justify a higher valuation.
Analysis
- Earnings recovery gains traction, supported by lower funding costs. KB Bank (BBKP) booked a bank-only net profit of Rp6b in 1H26, following a net profit of Rp13b in full-year 2025, marking a significant turnaround from historical losses. Net interest income (NII) rose 54.4% yoy to Rp695b, while pre-provision operating profit (PPOP) improved 43.5% yoy. Net interest margin (NIM) expanded 70bp yoy to 2.0%, largely supported by a 100bp reduction in cost of funds (CoF) to 4.3% while loan yield was relatively stable at 8.2% in 1H26. Deposits grew 12.4% yoy, with CASA increasing 15.2% yoy, lifting the CASA ratio to 32.3%. While operating performance is improving, earnings remain modest, limiting the bank’s capacity to absorb additional credit costs.
- Asset quality improves, but legacy loans remain a significant overhang. BBKP's loan-at-risk (LaR) ratio declined to 21.9% in Jun 26 from 24.4% in Jun 25, while normal loans (good loans) grew 8.1% yoy, accounting for nearly 80% of total loans (2021: 35%). However, gross NPL remained elevated at 10.0%, suggesting that legacy asset-quality issues have yet to be fully resolved. Management acknowledged that much of the historical LaR reduction was achieved through write-offs and asset swaps. BBKP continues to resolve legacy loans through organic collections, targeting Rp3t annually following Rp2.8t in 2025 and Rp1.4t in 1H26. Management is prioritising this approach to preserve capital, while discussing the possibility of a larger NPL clean-up in 2027, although no firm plan has been announced.
NOT RATED
Current price:
Target price:
Upside:
Rp41
n.a.
n.a.
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


