
Company Coverage
SEA (SE US): 3Q26: Solid Delivery Across All Segments; Maintain BUY
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
US$77.96
US$123.72
58.7%
US$181.18
Analyst
Analyst
Analyst
Highlights
9M26 revenue of US$23.47b (+46% yoy) and PATMI of US$1.36b (+15% yoy) are ahead of the run-rate, representing 79% and 81% of our full-year forecasts respectively.
In 3Q26, Shopee’s take rate rose to 15%, Monee’s loan book grew to US$12.6b (+60% yoy), and Garena bookings rebounded to US$890m (+6% yoy).
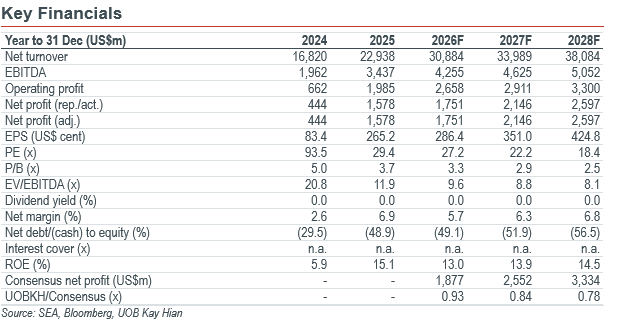
Maintain BUY with a lower SOTP-based target price of US$123.72, after factoring a de-rating across peers into our SOTP valuation.
Analysis
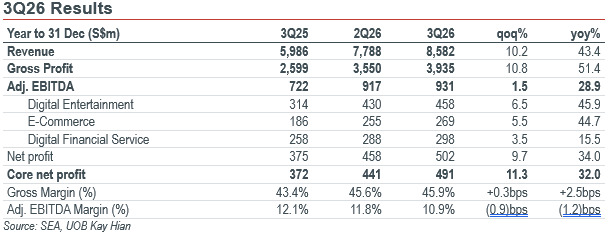
Revenue and earnings ahead of run-rate. SEA reported 3Q26 revenue of US$8.58b (+43% yoy), while PATMI came in at US$491m (+32% yoy). 9M26 revenue and PATMI reached US$23.47b (+46% yoy) and US$1.36b (+15% yoy) respectively, representing 79.0% and 80.5% of our forecasts, supported by growth across all three core businesses. Adjusted EBITDA increased 29% yoy to US$931.3m, while gross margin improved yoy to 45.9% (+2.5bps), despite higher marketing expenses and credit loss provisions.
E-commerce (Shopee): Strong GMV growth and improving monetisation support profitability. 3Q26 GMV reached a record US$39.7b (+23% yoy, +4% qoq), while revenue grew 41% yoy to US$6.07b, driven by a 51% yoy growth in core marketplace revenue and over 55% yoy advertising revenue growth. GAAP take rate improved to 15% from 13% in 3Q25. ShopeeVIP membership exceeded 21m, contributing nearly 25% of GMV. Adjusted EBITDA rose 45% yoy to US$269.2m, supported by improving unit economics. The company remains on track to achieve approximately 25% GMV growth and US$1.0b adjusted EBITDA in 2026.
Highlights
9M26 revenue of US$23.47b (+46% yoy) and PATMI of US$1.36b (+15% yoy) are ahead of the run-rate, representing 79% and 81% of our full-year forecasts respectively.
In 3Q26, Shopee’s take rate rose to 15%, Monee’s loan book grew to US$12.6b (+60% yoy), and Garena bookings rebounded to US$890m (+6% yoy).
Maintain BUY with a lower SOTP-based target price of US$123.72, after factoring a de-rating across peers into our SOTP valuation.
Analysis
Revenue and earnings ahead of run-rate. SEA reported 3Q26 revenue of US$8.58b (+43% yoy), while PATMI came in at US$491m (+32% yoy). 9M26 revenue and PATMI reached US$23.47b (+46% yoy) and US$1.36b (+15% yoy) respectively, representing 79.0% and 80.5% of our forecasts, supported by growth across all three core businesses. Adjusted EBITDA increased 29% yoy to US$931.3m, while gross margin improved yoy to 45.9% (+2.5bps), despite higher marketing expenses and credit loss provisions.
E-commerce (Shopee): Strong GMV growth and improving monetisation support profitability. 3Q26 GMV reached a record US$39.7b (+23% yoy, +4% qoq), while revenue grew 41% yoy to US$6.07b, driven by a 51% yoy growth in core marketplace revenue and over 55% yoy advertising revenue growth. GAAP take rate improved to 15% from 13% in 3Q25. ShopeeVIP membership exceeded 21m, contributing nearly 25% of GMV. Adjusted EBITDA rose 45% yoy to US$269.2m, supported by improving unit economics. The company remains on track to achieve approximately 25% GMV growth and US$1.0b adjusted EBITDA in 2026.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
US$77.96
US$123.72
58.7%
US$181.18
Analyst
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

10 Nov 2026
Venture Corporation (VMS SP): 3Q26: Broadening Growth Led By Portfolio B; Maintain BUY

5 Nov 2026
Beng Kuang Marine (BKM SP) - 3Q26: Higher Offshore Activities Drive Robust Growth

6 Nov 2026
DBS Group Holdings (DBS SP) - 3Q26: Focus On Resiliency And Growth Of Core Franchise
Our latest research

10 Nov 2026
Frasers Logistics & Commercial Trust (FLT SP): 2HFY26: Logistics Strength But Higher Gearing Limits Debt Headroom

10 Nov 2026
Oversea-Chinese Banking Corp (OCBC SP): 3Q26: Banking Strength Offsets Insurance Weakness
10 Nov 2026