

Company Coverage
Moshi Moshi (MOSHI TB) - 3Q26 Preview: Earnings Growth Is Expected To Remain Resilient
BUY (Maintained)
Current price:
Target price:
Upside:
Bt34.50
Bt50.00
+44.93%
Analyst
Highlights
- The current share price is trading close to its historical trough at 14.4x PE, which we view as a reasonable entry point.
- 3Q26 earnings are expected to increase 12% yoy, driven by positive SSSG and gross margin expansion.
- We view the flooding as a short-term impact, while business fundamentals remain unchanged.
- Maintain BUY. Target price is Bt50.00, based on mid-27F PE of 20x.
Analysis
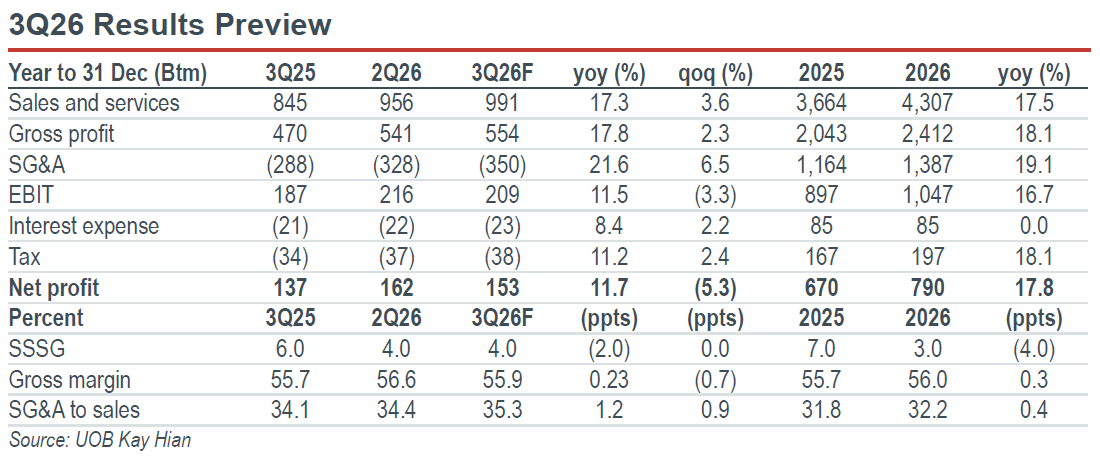
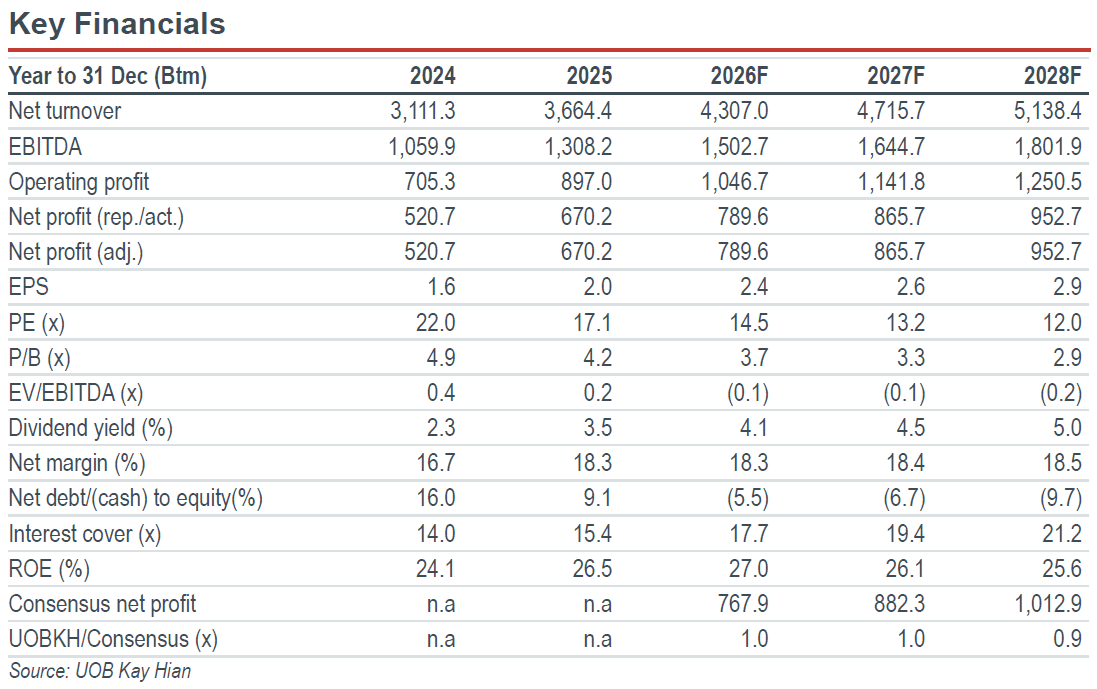
- Strong SSSG to offset higher expenses. We expect Moshi Moshi (MOSHI) to report 3Q26 net profit of Bt153m (+12% yoy, -5% qoq). Earnings growth is expected to soften from +21% yoy in 1H26, due to lower profitability. Sales growth should remain impressive, with revenue expected to increase 17% yoy, driven by +4% yoy SSSG. Gross margin should expand to 55.9% from a better product mix. This should more than offset the impact of unfavourable forex and higher logistics costs. SG&A-to-sales are expected to increase by 120 bps yoy, due to higher depreciation from new store openings and higher marketing expenses. Overall, we expect 3Q26 earnings to remain resilient, with 9M26 earnings accounting for 64% of our full-year forecast, in line with 9M25 at 64%. Hence, we maintain our 2026 earnings growth at 18% yoy.
Highlights
- The current share price is trading close to its historical trough at 14.4x PE, which we view as a reasonable entry point.
- 3Q26 earnings are expected to increase 12% yoy, driven by positive SSSG and gross margin expansion.
- We view the flooding as a short-term impact, while business fundamentals remain unchanged.
- Maintain BUY. Target price is Bt50.00, based on mid-27F PE of 20x.
Analysis
- Strong SSSG to offset higher expenses. We expect Moshi Moshi (MOSHI) to report 3Q26 net profit of Bt153m (+12% yoy, -5% qoq). Earnings growth is expected to soften from +21% yoy in 1H26, due to lower profitability. Sales growth should remain impressive, with revenue expected to increase 17% yoy, driven by +4% yoy SSSG. Gross margin should expand to 55.9% from a better product mix. This should more than offset the impact of unfavourable forex and higher logistics costs. SG&A-to-sales are expected to increase by 120 bps yoy, due to higher depreciation from new store openings and higher marketing expenses. Overall, we expect 3Q26 earnings to remain resilient, with 9M26 earnings accounting for 64% of our full-year forecast, in line with 9M25 at 64%. Hence, we maintain our 2026 earnings growth at 18% yoy.
BUY (Maintained)
Current price:
Target price:
Upside:
Bt34.50
Bt50.00
+44.93%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Our latest research

13 Oct 2026
Frasers Centrepoint Trust (FCT SP): Benefitting From Population And Job Growth In North Region

12 Oct 2026
