

Company Coverage
SCG Packaging (SCGP TB): 3Q26 Earnings Remain Strong Despite Higher RCP Costs
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt30.25
Bt43.00
+42.15%
Bt39.00
Analyst
Highlights
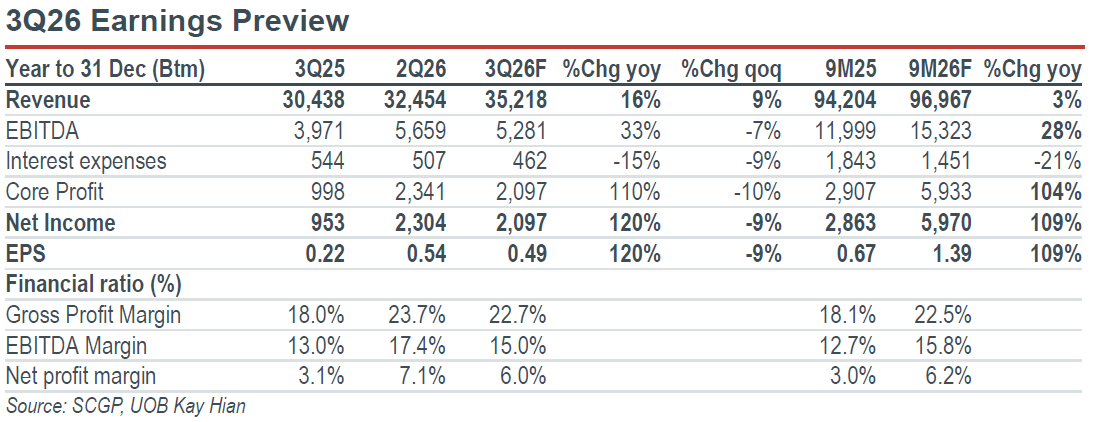
- We expect 3Q26 net profit of Bt2.10b, down qoq due to higher RCP costs, but up 120% yoy.
- Fajar continues to deliver a strong earnings performance, supported by selling price adjustments and effective cost management.
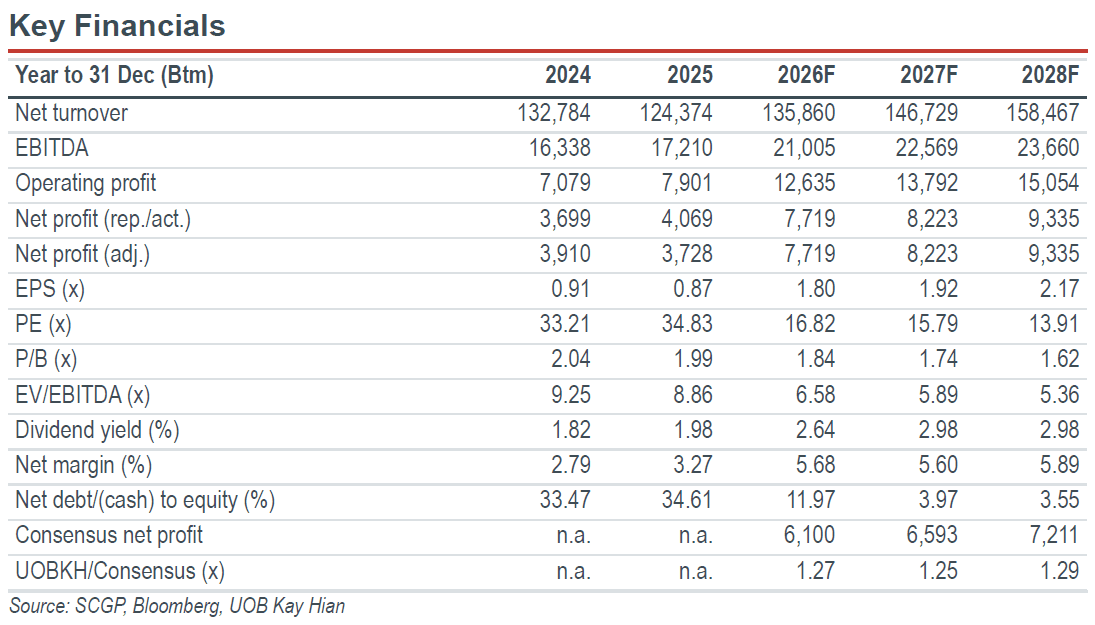
- Maintain BUY. Target price: Bt43.00 (previously Bt39.00).
Analysis
- 3Q26 net profit to decline qoq but remain strong. We expect SCG Packaging (SCGP) to report a 3Q26 net profit of Bt2.10b, down 9% qoq but up 120% yoy. The qoq decline is mainly attributable to higher recycled paper (RCP) costs, as the 14% qoq increase in RCP prices in 2Q26 is expected to feed through to SCGP’s raw material costs in 3Q26, weighing on both the integrated packaging business (IPB) and fibrous business (PB). We forecast EBITDA margins for IPB and PB at 19.5% and 8.2%, respectively, down from 20.4% and 9.5% in 2Q26.
- Nevertheless, earnings should remain strong, supported by selling price increases implemented progressively since 2Q26. Sales volumes is also likely to remain stable qoq despite Thailand’s seasonal low season. Higher sales from Vietnam and Indonesia should offset the seasonal weakness in Thailand, driven by an acceleration in customer orders across all segments as customers build inventory to meet demand during the extended holiday period from late-26 to early-27.
Highlights
- We expect 3Q26 net profit of Bt2.10b, down qoq due to higher RCP costs, but up 120% yoy.
- Fajar continues to deliver a strong earnings performance, supported by selling price adjustments and effective cost management.
- Maintain BUY. Target price: Bt43.00 (previously Bt39.00).
Analysis
- 3Q26 net profit to decline qoq but remain strong. We expect SCG Packaging (SCGP) to report a 3Q26 net profit of Bt2.10b, down 9% qoq but up 120% yoy. The qoq decline is mainly attributable to higher recycled paper (RCP) costs, as the 14% qoq increase in RCP prices in 2Q26 is expected to feed through to SCGP’s raw material costs in 3Q26, weighing on both the integrated packaging business (IPB) and fibrous business (PB). We forecast EBITDA margins for IPB and PB at 19.5% and 8.2%, respectively, down from 20.4% and 9.5% in 2Q26.
- Nevertheless, earnings should remain strong, supported by selling price increases implemented progressively since 2Q26. Sales volumes is also likely to remain stable qoq despite Thailand’s seasonal low season. Higher sales from Vietnam and Indonesia should offset the seasonal weakness in Thailand, driven by an acceleration in customer orders across all segments as customers build inventory to meet demand during the extended holiday period from late-26 to early-27.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Bt30.25
Bt43.00
+42.15%
Bt39.00
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Our latest research

13 Oct 2026
Frasers Centrepoint Trust (FCT SP): Benefitting From Population And Job Growth In North Region

12 Oct 2026
