

Company Coverage
Buana Lintas Lautan (BULL IJ): Bigger Fleet, Bullish Rates
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp328
Rp780
+137.8%
Rp770
Analyst
Analyst
Highlights
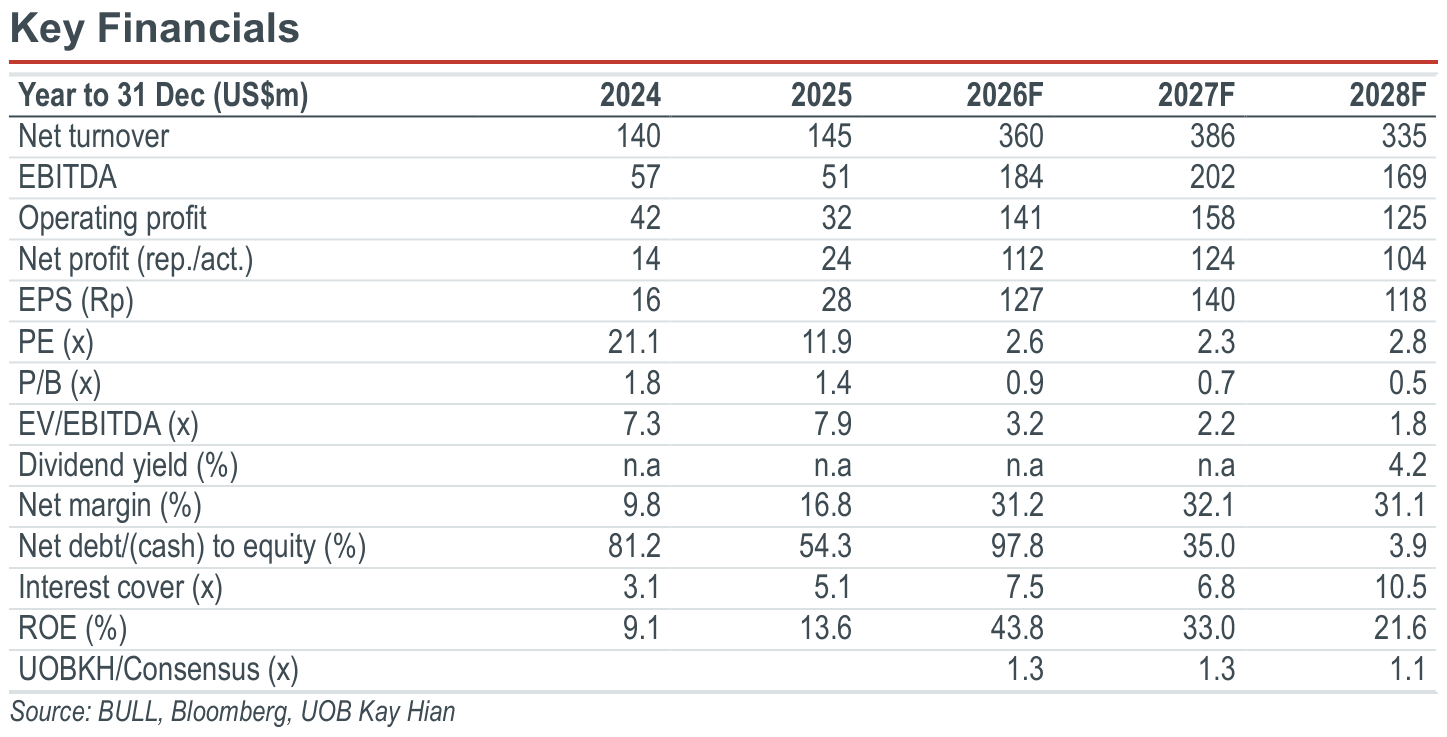
- Tanker freight rates have hit new highs, and with BULL's fleet set to reach 19 vessels by end-26, we expect a record 4Q26 profit after a softer 3Q26.
- The FPSO and FSO vessels expected for delivery in October add fixed contracted income, diversifying BULL from the volatile spot tanker market.
- We raise our forecasts for 2026-28, with 2027 EBITDA up 9.8% yoy to US$201.6m. We maintain BUY with a higher target price of Rp780.
Analysis
- Tanker freight rates reaching new highs following demand surge. Renewed tensions in the Middle East and tightening global crude supply have pushed tanker rates past both the 2022 energy-crisis spike and the 2Q26 peak. Aframax rates now sit above US$250,000/day, about 67% higher than 2Q26's peak of around US$150,000/day, while mid-range (MR) tankers, which cover the bulk of Buana Lintas Lautan’s (BULL) fleet, have climbed to about US$60,000/day from around US$40,000/day in 2Q26. With spot charters making up 98% of 1H26 revenue, BULL captures these moves almost in full. We see this as more than a short-lived spike: the Middle East tensions show no signs of easing, crude prices remain elevated and regional output is not expected to normalise until early-27. We therefore expect rates to ease only gradually throughout 2027, and even so, BULL expects its recently acquired vessels to pay off their purchase minus scrap value in under a year of commencing operations.
- New fleet additions improve earnings quality. The three MR tankers delivered in July lift BULL’s fleet to 15 vessels, and four more due in 4Q26 bring it to 19 by end-26, nearly double the 10 vessels recorded at end-25. This is one more than the 18 vessels in our previous report, and every remaining addition now has a firm delivery date and committed funding. The key additions are the Floating Production Storage and Offloading (FPSO) and Floating Storage and Offloading (FSO) deliveries due in October, acquired for a combined US$150m, with due diligence and funding secured, which limits execution risk. The FPSO is contracted to 2030 for about US$120m (around US$80,000/day, with a potential 10-year extension) and the FSO for 10 years for about US$50m, adding roughly US$35m of fixed revenue a year (~10% of 2027 revenue). With contract value already above the purchase price, we see this as a shift away from a pure spot play, giving BULL a stable earnings base. The remaining two, an Aframax and an MR tanker, should arrive in time to capture the still-elevated freight rates.
Highlights
- Tanker freight rates have hit new highs, and with BULL's fleet set to reach 19 vessels by end-26, we expect a record 4Q26 profit after a softer 3Q26.
- The FPSO and FSO vessels expected for delivery in October add fixed contracted income, diversifying BULL from the volatile spot tanker market.
- We raise our forecasts for 2026-28, with 2027 EBITDA up 9.8% yoy to US$201.6m. We maintain BUY with a higher target price of Rp780.
Analysis
- Tanker freight rates reaching new highs following demand surge. Renewed tensions in the Middle East and tightening global crude supply have pushed tanker rates past both the 2022 energy-crisis spike and the 2Q26 peak. Aframax rates now sit above US$250,000/day, about 67% higher than 2Q26's peak of around US$150,000/day, while mid-range (MR) tankers, which cover the bulk of Buana Lintas Lautan’s (BULL) fleet, have climbed to about US$60,000/day from around US$40,000/day in 2Q26. With spot charters making up 98% of 1H26 revenue, BULL captures these moves almost in full. We see this as more than a short-lived spike: the Middle East tensions show no signs of easing, crude prices remain elevated and regional output is not expected to normalise until early-27. We therefore expect rates to ease only gradually throughout 2027, and even so, BULL expects its recently acquired vessels to pay off their purchase minus scrap value in under a year of commencing operations.
- New fleet additions improve earnings quality. The three MR tankers delivered in July lift BULL’s fleet to 15 vessels, and four more due in 4Q26 bring it to 19 by end-26, nearly double the 10 vessels recorded at end-25. This is one more than the 18 vessels in our previous report, and every remaining addition now has a firm delivery date and committed funding. The key additions are the Floating Production Storage and Offloading (FPSO) and Floating Storage and Offloading (FSO) deliveries due in October, acquired for a combined US$150m, with due diligence and funding secured, which limits execution risk. The FPSO is contracted to 2030 for about US$120m (around US$80,000/day, with a potential 10-year extension) and the FSO for 10 years for about US$50m, adding roughly US$35m of fixed revenue a year (~10% of 2027 revenue). With contract value already above the purchase price, we see this as a shift away from a pure spot play, giving BULL a stable earnings base. The remaining two, an Aframax and an MR tanker, should arrive in time to capture the still-elevated freight rates.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
Rp328
Rp780
+137.8%
Rp770
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


