Company Coverage
Aztech Global (AZTECH SP): 3Q26: Earnings In Line; Competition Remains Intense
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$0.405
S$0.44
8.6%
S$0.73
Analyst
Highlights
- 9M26 net profit of S$15.9m forms 79.6% of our full-year forecast, in line with expectations after allowing for quarterly seasonality.
- Revenue of S$231.8m forms 73.4% of our July forecast, slightly below expectations. Competition continues to weigh on existing customer orders.
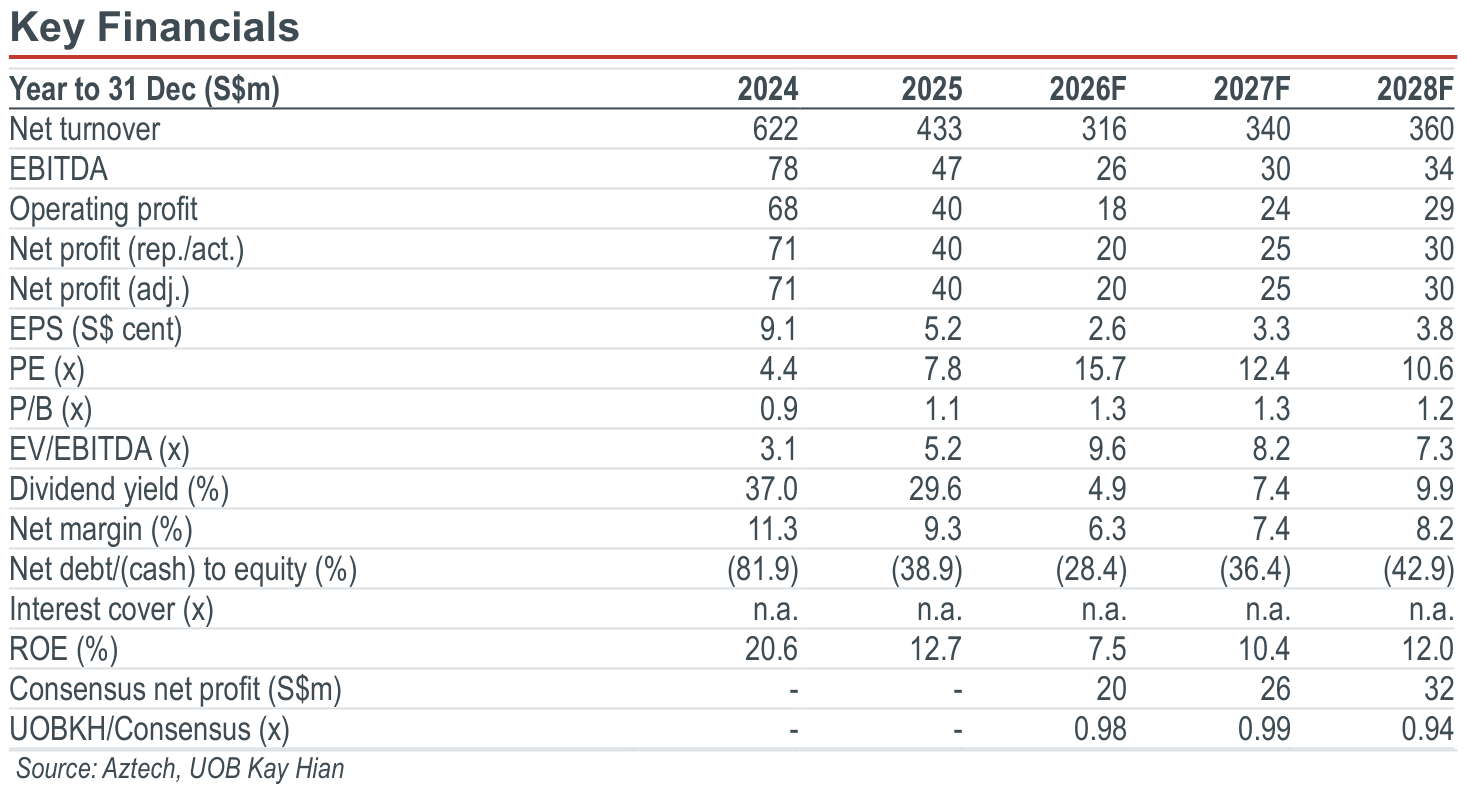
- Maintain HOLD with a lower target price of S$0.44 (previously S$0.73), pegged to 13.6x 2027F PE (+1.5SD above historical mean).
Analysis
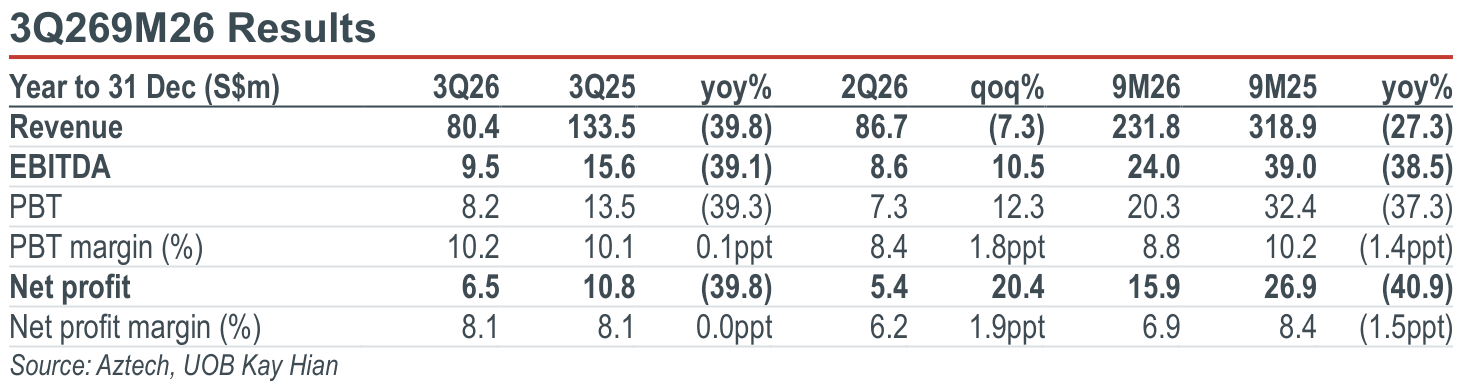
- Earnings in line; revenue slightly below expectations. Aztech Global’s (Aztech) 3Q26 revenue fell 39.8% yoy and 7.3% qoq to S$80.4m as intensifying competition reduced orders from existing customers. Net profit declined 39.8% yoy but rose 20.4% qoq to S$6.5m. 9M26 revenue of S$231.8m (down 27.3% yoy) formed 73.4% of our full-year forecast, slightly below expectations, while net profit of S$15.9m (down 40.9% yoy) formed 79.6%, in line with expectations.
- Margins improved qoq, but remain lower on a 9M basis. 3Q26 EBITDA rose 10.5% qoq to S$9.5m despite lower sales, lifting PBT margin to 10.2% from 8.4% in 2Q26. A tax incentive cut the effective tax rate to 20.7% from 26.0%, raising net margin to 8.1% from 6.2%, flat yoy. However, 9M26 PBT and net margins fell to 8.8% and 6.9% respectively (9M25: 10.2% and 8.4%) on higher R&D costs, lower interest income and forex losses from a stronger Chinese yuan. Increased production in Malaysia also raised the 9M26 effective tax rate to 21.7% from 17.0%.
- 4Q26 delivery remains key. Our forecasts imply 4Q26 revenue of S$83.8m (up 4.3% qoq) and net profit of S$4.1m (down 37.5% qoq). The high earnings fulfilment partly reflects the 3Q tax incentive and quarterly earnings seasonality, so we do not view it as a beat. Existing customer orders and NPI conversion will drive 4Q performance.
Highlights
- 9M26 net profit of S$15.9m forms 79.6% of our full-year forecast, in line with expectations after allowing for quarterly seasonality.
- Revenue of S$231.8m forms 73.4% of our July forecast, slightly below expectations. Competition continues to weigh on existing customer orders.
- Maintain HOLD with a lower target price of S$0.44 (previously S$0.73), pegged to 13.6x 2027F PE (+1.5SD above historical mean).
Analysis
- Earnings in line; revenue slightly below expectations. Aztech Global’s (Aztech) 3Q26 revenue fell 39.8% yoy and 7.3% qoq to S$80.4m as intensifying competition reduced orders from existing customers. Net profit declined 39.8% yoy but rose 20.4% qoq to S$6.5m. 9M26 revenue of S$231.8m (down 27.3% yoy) formed 73.4% of our full-year forecast, slightly below expectations, while net profit of S$15.9m (down 40.9% yoy) formed 79.6%, in line with expectations.
- Margins improved qoq, but remain lower on a 9M basis. 3Q26 EBITDA rose 10.5% qoq to S$9.5m despite lower sales, lifting PBT margin to 10.2% from 8.4% in 2Q26. A tax incentive cut the effective tax rate to 20.7% from 26.0%, raising net margin to 8.1% from 6.2%, flat yoy. However, 9M26 PBT and net margins fell to 8.8% and 6.9% respectively (9M25: 10.2% and 8.4%) on higher R&D costs, lower interest income and forex losses from a stronger Chinese yuan. Increased production in Malaysia also raised the 9M26 effective tax rate to 21.7% from 17.0%.
- 4Q26 delivery remains key. Our forecasts imply 4Q26 revenue of S$83.8m (up 4.3% qoq) and net profit of S$4.1m (down 37.5% qoq). The high earnings fulfilment partly reflects the 3Q tax incentive and quarterly earnings seasonality, so we do not view it as a beat. Existing customer orders and NPI conversion will drive 4Q performance.
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$0.405
S$0.44
8.6%
S$0.73
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

28 Oct 2026
iFAST Corporation (IFAST SP): 9M26: Earnings Beat; Record AUA And Strong Banking Growth

28 Sept 2026
Reclaims Global (RGL SP) : 1HFY27: Healthy Results; Margins Remain Resilient

7 Sept 2026
Soon Hock Enterprise (SHOCK SP): 1H26: Robust Development Pipeline Supports Growth
Our latest research

29 Oct 2026
Mapletree Industrial Trust (MINT SP): 2QFY27: Revamp Underway

29 Oct 2026
UI Boustead REIT (UIBREIT SP): 1HFY27: Steady Progress On Leasing And Co-development

29 Oct 2026