
Company Coverage
Bumitama Agri (BAL SP): 9M26: Below Expectations On Delayed Sales Realisation
BUY (Maintained)
Current price:
Target price:
Upside:
S$1.39
S$2.54
82.7%
Analyst
Highlights
- Bumitama’s 9M26 net profit of Rp2,440b (+30% yoy) came in below expectations, due to lower-than-expected sales volume from logistic disruptions despite production growth.
- We expect the inventory buildup to be gradually cleared over the next two quarters, while operationally, Bumitama remains resilient on track to exceed its upper end target of 10% yoy.
- We trim our 2026F earnings forecasts by 12% but slightly raised our 2027F estimates by 1% to account for deferred sales realisation into the following year, partly offset by lower FFB production in 2027F.
- Maintain BUY with a target price of S$2.54 based on 14x 2027F PE.
Analysis
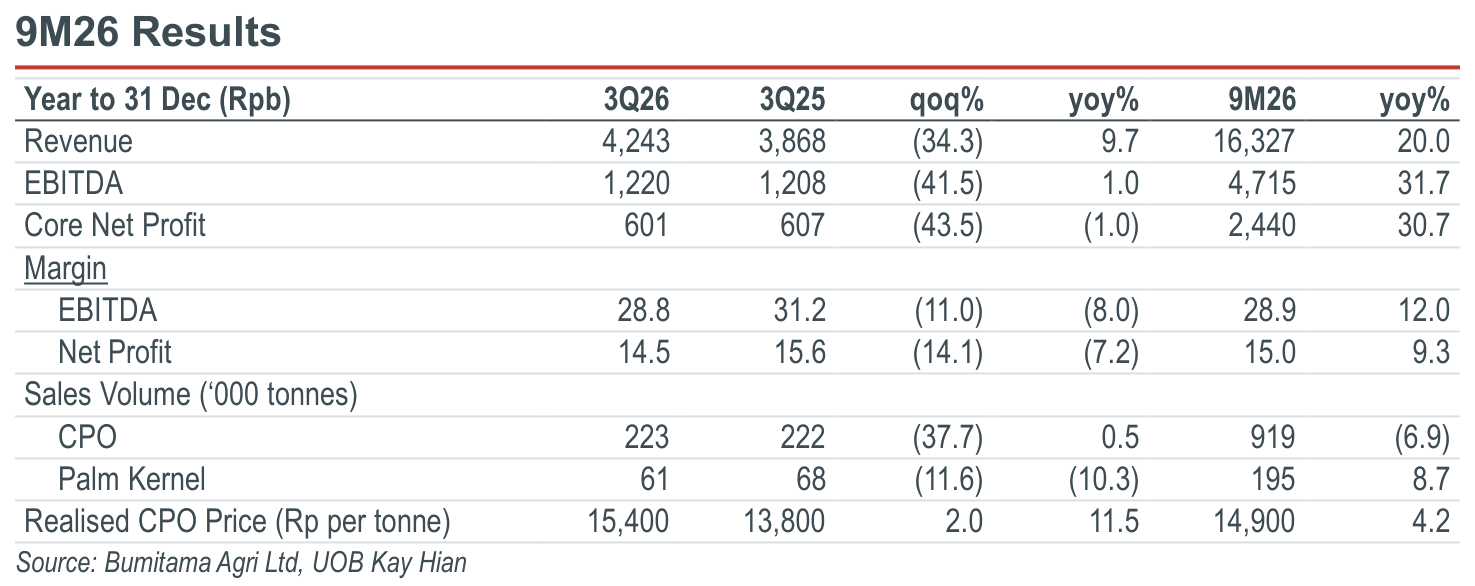
- Below expectations. Bumitama Agri’s (Bumitama) 9M26 core net profit of Rp2,440t (+30% yoy) came in below expectations, accounting for 64%/66% of our and consensus forecasts respectively. The earnings miss was mainly due to weaker-than-expected CPO sales volume (-38% qoq) in 3Q26, which saw core net profit fell 44% qoq to Rp601b.
Highlights
- Bumitama’s 9M26 net profit of Rp2,440b (+30% yoy) came in below expectations, due to lower-than-expected sales volume from logistic disruptions despite production growth.
- We expect the inventory buildup to be gradually cleared over the next two quarters, while operationally, Bumitama remains resilient on track to exceed its upper end target of 10% yoy.
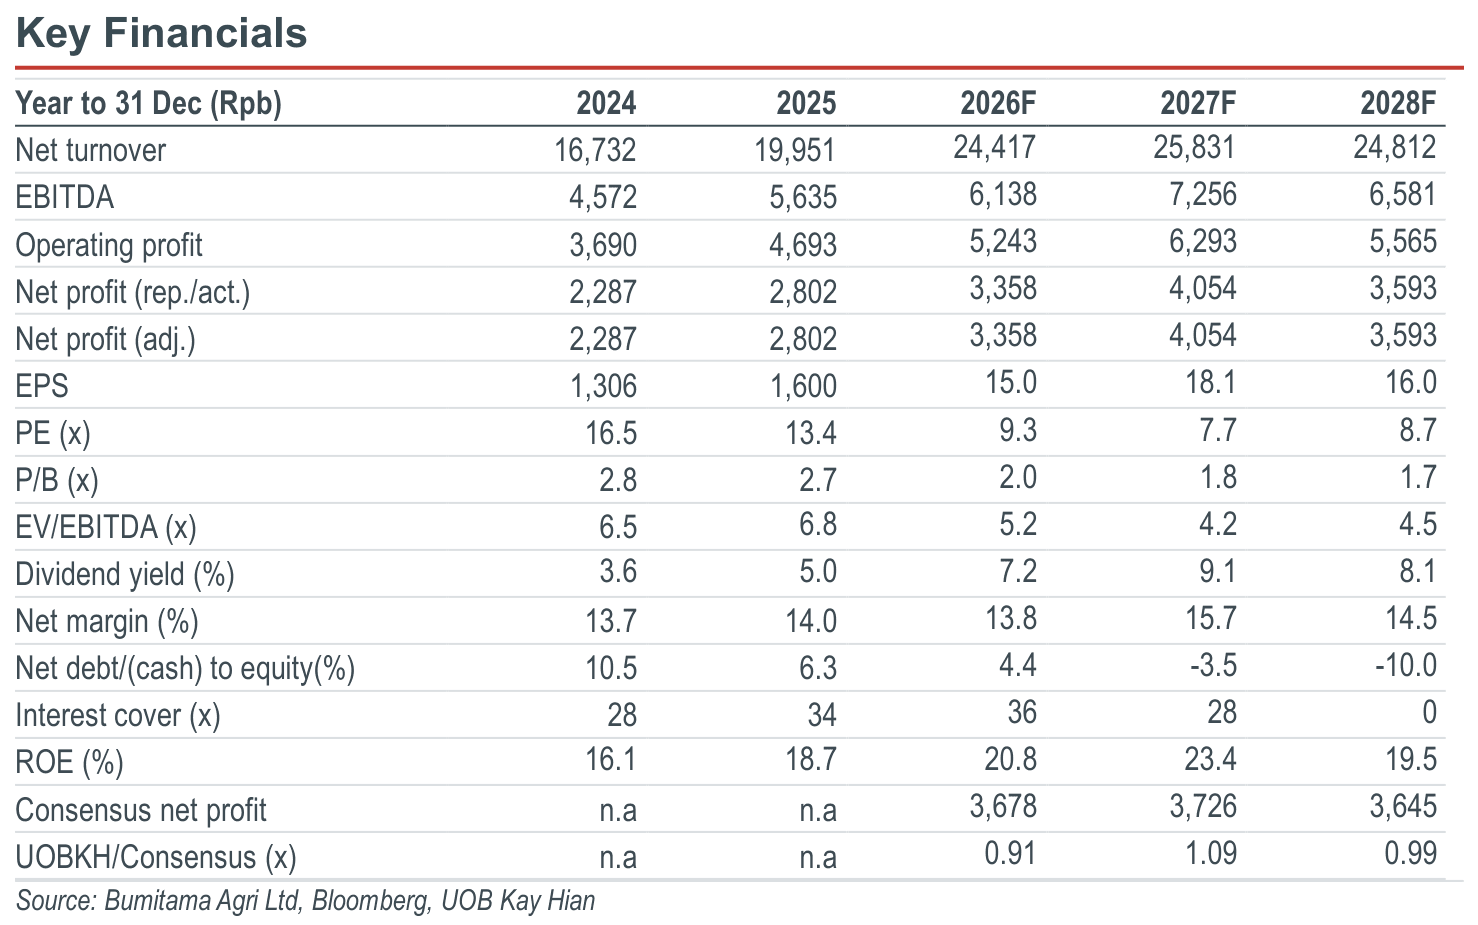
- We trim our 2026F earnings forecasts by 12% but slightly raised our 2027F estimates by 1% to account for deferred sales realisation into the following year, partly offset by lower FFB production in 2027F.
- Maintain BUY with a target price of S$2.54 based on 14x 2027F PE.
Analysis
- Below expectations. Bumitama Agri’s (Bumitama) 9M26 core net profit of Rp2,440t (+30% yoy) came in below expectations, accounting for 64%/66% of our and consensus forecasts respectively. The earnings miss was mainly due to weaker-than-expected CPO sales volume (-38% qoq) in 3Q26, which saw core net profit fell 44% qoq to Rp601b.
BUY (Maintained)
Current price:
Target price:
Upside:
S$1.39
S$2.54
82.7%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

30 Oct 2026
Keppel (KEP SP): Decent Headline Earnings Growth But Slower-than-expected Core Earnings Growth In 3Q26

12 Nov 2026
UMS Integration (UMSH SP): 3Q26: Earnings In Line; New Customer Ramp-up Drives Growth

16 Nov 2026
First Resources (FR SP): 3Q26: Above Expectations On Strong Output; Consensus Looks Too Low For 4Q
Our latest research

16 Nov 2026
CSE Global (CSE SP): 3Q26: Strong Order Momentum; Margin Recovery Expected In 2H26
16 Nov 2026
First Resources (FR SP): 3Q26: Above Expectations On Strong Output; Consensus Looks Too Low For 4Q

16 Nov 2026