
Company Coverage
Delfi (DELFI SP): 3Q26: Resilient Demand For Own Brands Amid Margin Pressure
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$0.645
S$0.88
+36.4%
S$0.98
Analyst
Analyst
Highlights
- 9M26 revenue rose 0.1% yoy to US$384.6m, accounting for 75.4% of our full-year forecast. Growth was driven by resilient demand for its own brands.
- Elevated cocoa prices and currency headwinds continue to weigh on margins, although easing input costs and strong demand for its own brands could support recovery in 2027.
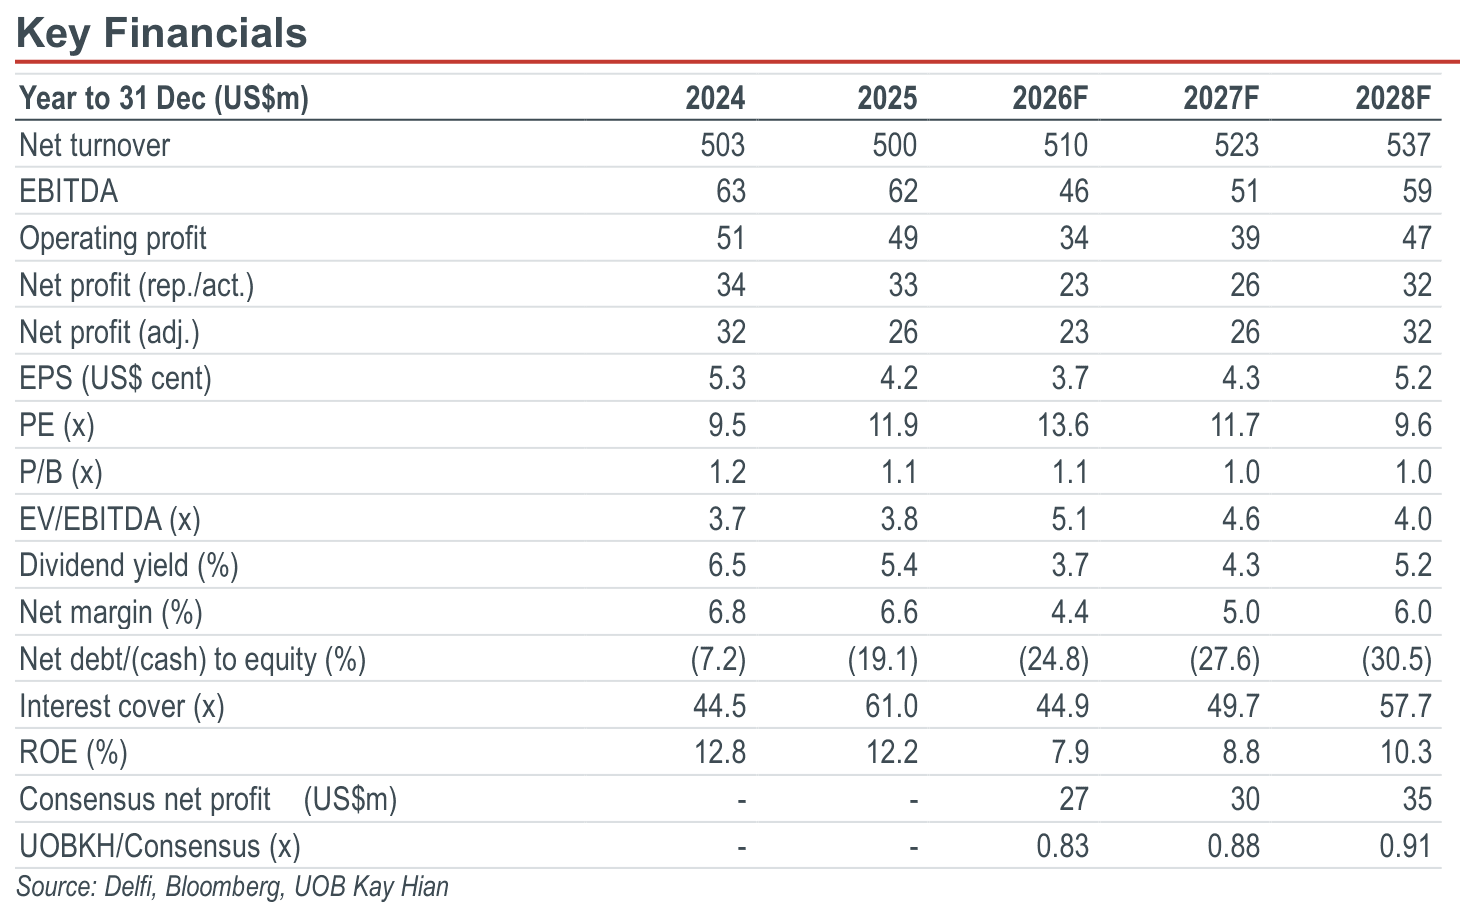
- Maintain BUY with a 10% lower target price of S$0.88, pegged to 16x 2027F PE, based on historical mean.
Analysis
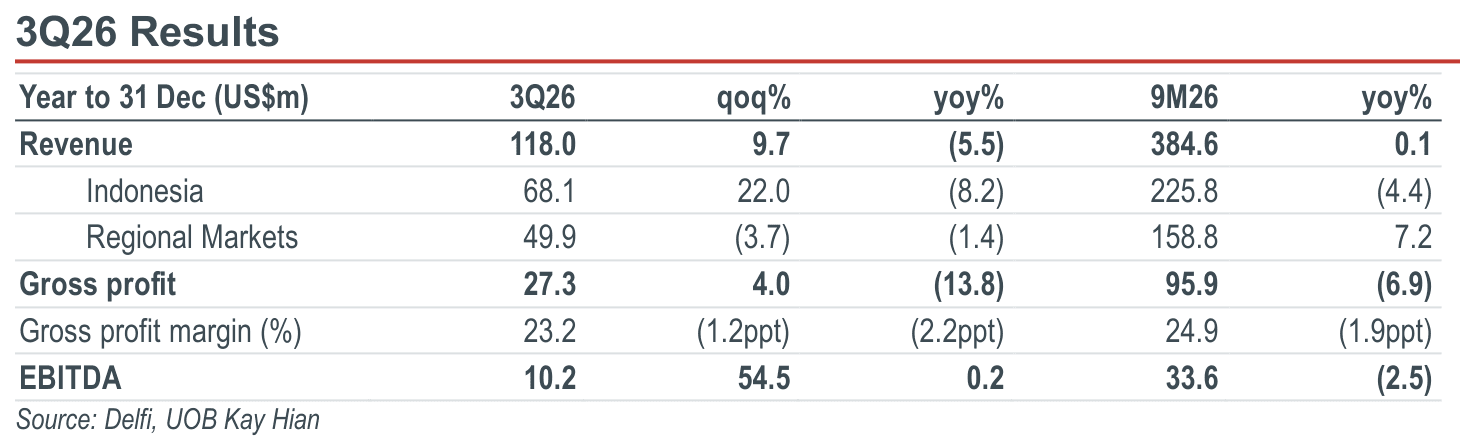
- 3Q26 revenue declined amid currency headwinds and margin pressures. Delfi reported 3Q26 revenue of US$118.0m (-5.5% yoy), largely due to weaker regional currencies, alongside softer consumer demand in Indonesia. On a constant currency basis, revenue remained flat yoy. Elevated raw material costs and currency pressures weighed on profitability, with gross margin declining 2.2ppt yoy to 23.2%, while EBITDA remained stable at US$10.2m (+0.2% yoy), supported by lower operating expenses. 9M26 revenue remained stable at US$384.6m (+0.1% yoy), accounting for 75.4% of our full-year forecast, broadly in line with expectations.
- Own brands remains a key growth driver. Delfi's own brands business remained resilient in 9M26, with sales in Indonesia growing 11.2% yoy, supported by sustained demand for its key brands despite weaker consumer sentiment and challenging domestic economic conditions. Regional markets also recorded strong own brands performance, particularly in Malaysia and the Philippines, supporting an overall regional revenue growth of 7.2% yoy to US$158.8m. The continued strength of its own brands, which typically command higher margins, remains a key driver of underlying growth.
Highlights
- 9M26 revenue rose 0.1% yoy to US$384.6m, accounting for 75.4% of our full-year forecast. Growth was driven by resilient demand for its own brands.
- Elevated cocoa prices and currency headwinds continue to weigh on margins, although easing input costs and strong demand for its own brands could support recovery in 2027.
- Maintain BUY with a 10% lower target price of S$0.88, pegged to 16x 2027F PE, based on historical mean.
Analysis
- 3Q26 revenue declined amid currency headwinds and margin pressures. Delfi reported 3Q26 revenue of US$118.0m (-5.5% yoy), largely due to weaker regional currencies, alongside softer consumer demand in Indonesia. On a constant currency basis, revenue remained flat yoy. Elevated raw material costs and currency pressures weighed on profitability, with gross margin declining 2.2ppt yoy to 23.2%, while EBITDA remained stable at US$10.2m (+0.2% yoy), supported by lower operating expenses. 9M26 revenue remained stable at US$384.6m (+0.1% yoy), accounting for 75.4% of our full-year forecast, broadly in line with expectations.
- Own brands remains a key growth driver. Delfi's own brands business remained resilient in 9M26, with sales in Indonesia growing 11.2% yoy, supported by sustained demand for its key brands despite weaker consumer sentiment and challenging domestic economic conditions. Regional markets also recorded strong own brands performance, particularly in Malaysia and the Philippines, supporting an overall regional revenue growth of 7.2% yoy to US$158.8m. The continued strength of its own brands, which typically command higher margins, remains a key driver of underlying growth.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$0.645
S$0.88
+36.4%
S$0.98
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

29 Oct 2026
Aztech Global (AZTECH SP): 3Q26: Earnings In Line; Competition Remains Intense

12 Nov 2026
UMS Integration (UMSH SP): 3Q26: Earnings In Line; New Customer Ramp-up Drives Growth

16 Nov 2026
CSE Global (CSE SP): 3Q26: Strong Order Momentum; Margin Recovery Expected In 2H26
Our latest research

17 Nov 2026
United Hampshire US REIT (UHU SP): 9M26: Resilient Retail Portfolio With Multiple Paths For Growth

17 Nov 2026
China Sunsine Chemical (CSSC SP): 3Q26: Record Sales Volumes And Strong ASPs Drive Earnings Beat
16 Nov 2026