
Company Coverage
China Sunsine Chemical (CSSC SP): 3Q26: Record Sales Volumes And Strong ASPs Drive Earnings Beat
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$0.65
S$0.72
10.8%
S$0.71
Analyst
Analyst
Highlights
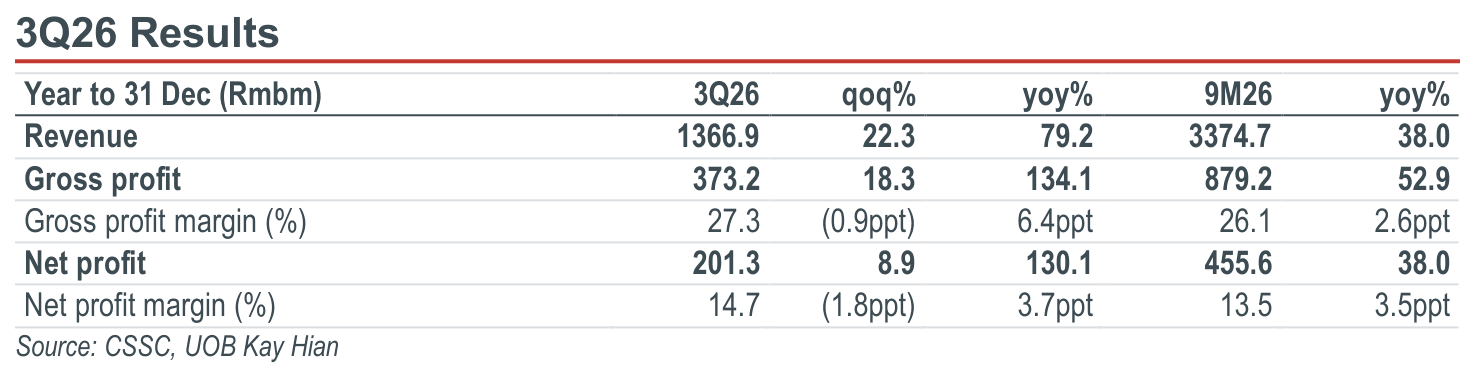
- Sunsine's 9M26 revenue rose 38% yoy to Rmb3.37b, while PAT increased 38% yoy to Rmb455.6m, forming 89% and 110% of our 2026 forecasts.
- Record 3Q26 sales volume of 66,390 tonnes (+22% yoy) and higher ASPs (+47% yoy) supported gross margin expansion to 27.3% (+6.4ppt yoy).
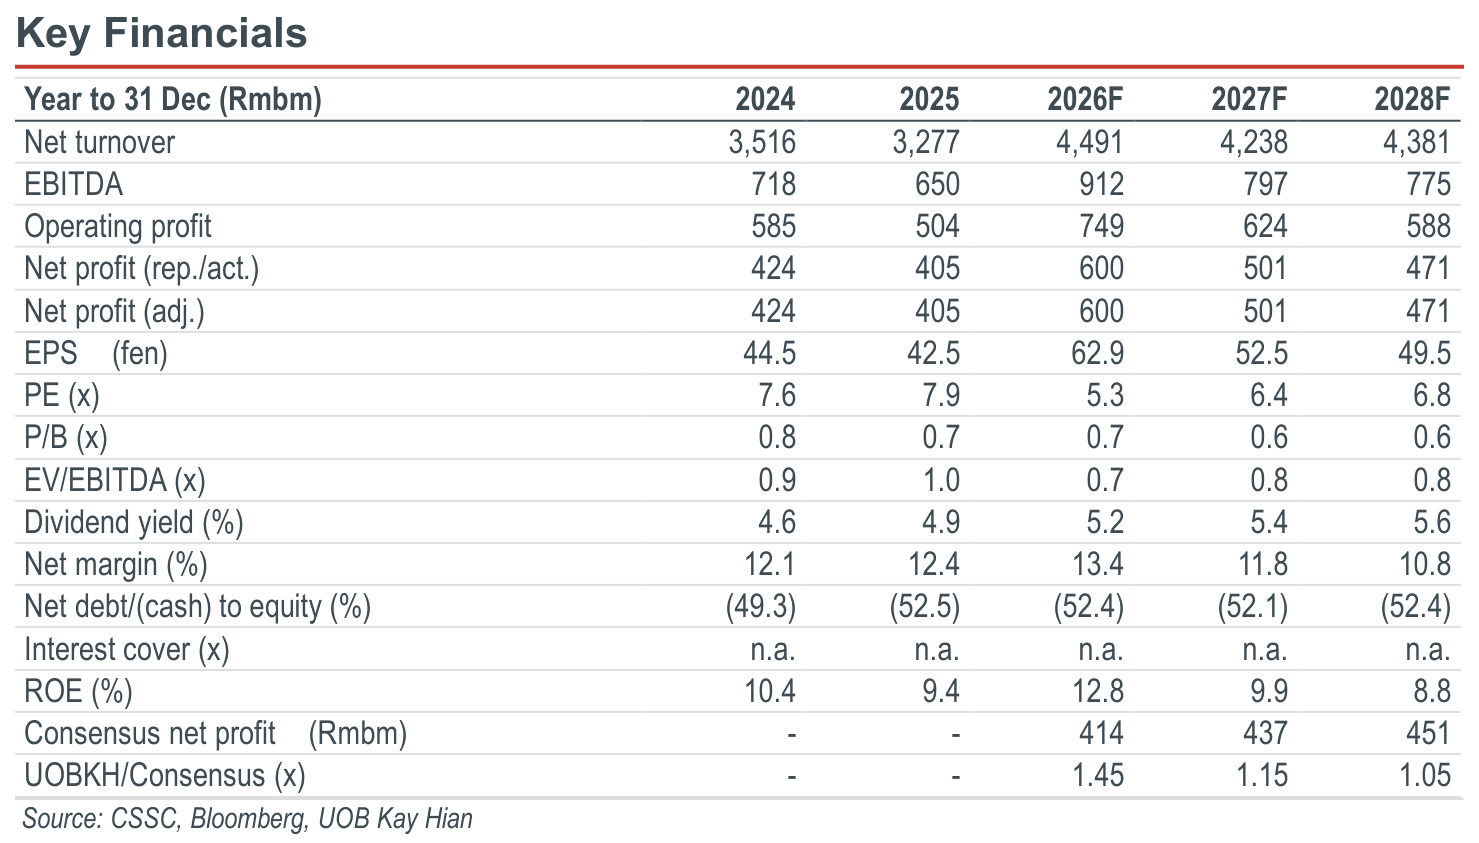
- Maintain HOLD with a 1.4% higher target price of S$0.72, based on 7.5x 2027F PE, partially offset by sector de-rating.
Analysis
- 9M26 earnings significantly ahead of expectations. China Sunsine Chemical (Sunsine) reported 3Q26 revenue of Rmb1.37b (+79% yoy), while profit after tax surged 130% yoy to Rmb201.3m, driven by higher ASPs and record sales volume. For 9M26, revenue increased 38% yoy to Rmb3.37b, while profit after tax rose 38% yoy to Rmb455.6m, representing 89.0% and 110.0% of our full-year forecasts respectively.
- Record sales volume drove robust revenue growth. Sunsine reported a 22% yoy increase in 3Q26 sales volume to a new high of 66,390 tonnes, up from 54,304 tonnes in 3Q25. This brought total 9M26 sales volume to 186,348 tonnes (+14% yoy), reflecting continued sales momentum despite challenging market conditions. Higher sales volumes, alongside a 47% yoy increase in ASP, supported strong revenue growth during the quarter.
- Sharp ASP increase supports margin expansion. 3Q26 ASP surged 47% yoy to Rmb20,436/tonne, primarily reflecting higher raw material prices following the Iran conflict and disruptions to shipping through the Strait of Hormuz. Sunsine responded swiftly by adjusting selling prices, enabling effective cost pass-through despite elevated input costs. Consequently, gross margin improved to 27.3% in 3Q26, compared with 20.9% in 3Q25 and 25.2% in 1H26. Continued volatility in crude oil and raw material prices could affect pricing and margins in subsequent quarters.
Highlights
- Sunsine's 9M26 revenue rose 38% yoy to Rmb3.37b, while PAT increased 38% yoy to Rmb455.6m, forming 89% and 110% of our 2026 forecasts.
- Record 3Q26 sales volume of 66,390 tonnes (+22% yoy) and higher ASPs (+47% yoy) supported gross margin expansion to 27.3% (+6.4ppt yoy).
- Maintain HOLD with a 1.4% higher target price of S$0.72, based on 7.5x 2027F PE, partially offset by sector de-rating.
Analysis
- 9M26 earnings significantly ahead of expectations. China Sunsine Chemical (Sunsine) reported 3Q26 revenue of Rmb1.37b (+79% yoy), while profit after tax surged 130% yoy to Rmb201.3m, driven by higher ASPs and record sales volume. For 9M26, revenue increased 38% yoy to Rmb3.37b, while profit after tax rose 38% yoy to Rmb455.6m, representing 89.0% and 110.0% of our full-year forecasts respectively.
- Record sales volume drove robust revenue growth. Sunsine reported a 22% yoy increase in 3Q26 sales volume to a new high of 66,390 tonnes, up from 54,304 tonnes in 3Q25. This brought total 9M26 sales volume to 186,348 tonnes (+14% yoy), reflecting continued sales momentum despite challenging market conditions. Higher sales volumes, alongside a 47% yoy increase in ASP, supported strong revenue growth during the quarter.
- Sharp ASP increase supports margin expansion. 3Q26 ASP surged 47% yoy to Rmb20,436/tonne, primarily reflecting higher raw material prices following the Iran conflict and disruptions to shipping through the Strait of Hormuz. Sunsine responded swiftly by adjusting selling prices, enabling effective cost pass-through despite elevated input costs. Consequently, gross margin improved to 27.3% in 3Q26, compared with 20.9% in 3Q25 and 25.2% in 1H26. Continued volatility in crude oil and raw material prices could affect pricing and margins in subsequent quarters.
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$0.65
S$0.72
10.8%
S$0.71
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

13 Nov 2026
Food Empire Holdings (FEH SP): 3Q26: Healthy Growth; Expect Better Margins And Earnings hoh For 2H26

28 Oct 2026
iFAST Corporation (IFAST SP): 9M26: Earnings Beat; Record AUA And Strong Banking Growth

5 Nov 2026
Beng Kuang Marine (BKM SP) - 3Q26: Higher Offshore Activities Drive Robust Growth
Our latest research

17 Nov 2026
United Hampshire US REIT (UHU SP): 9M26: Resilient Retail Portfolio With Multiple Paths For Growth

16 Nov 2026
CSE Global (CSE SP): 3Q26: Strong Order Momentum; Margin Recovery Expected In 2H26

16 Nov 2026