
Company Coverage
Genting Singapore (GENS SP): 3Q26: Dragged By Weaker Gaming Operations
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$0.61
S$0.65
6.56%
S$0.70
Analyst
Highlights
- 3Q26 results came in below expectations, with earnings declining steeply due to lower gaming statistics and higher operating expenses.
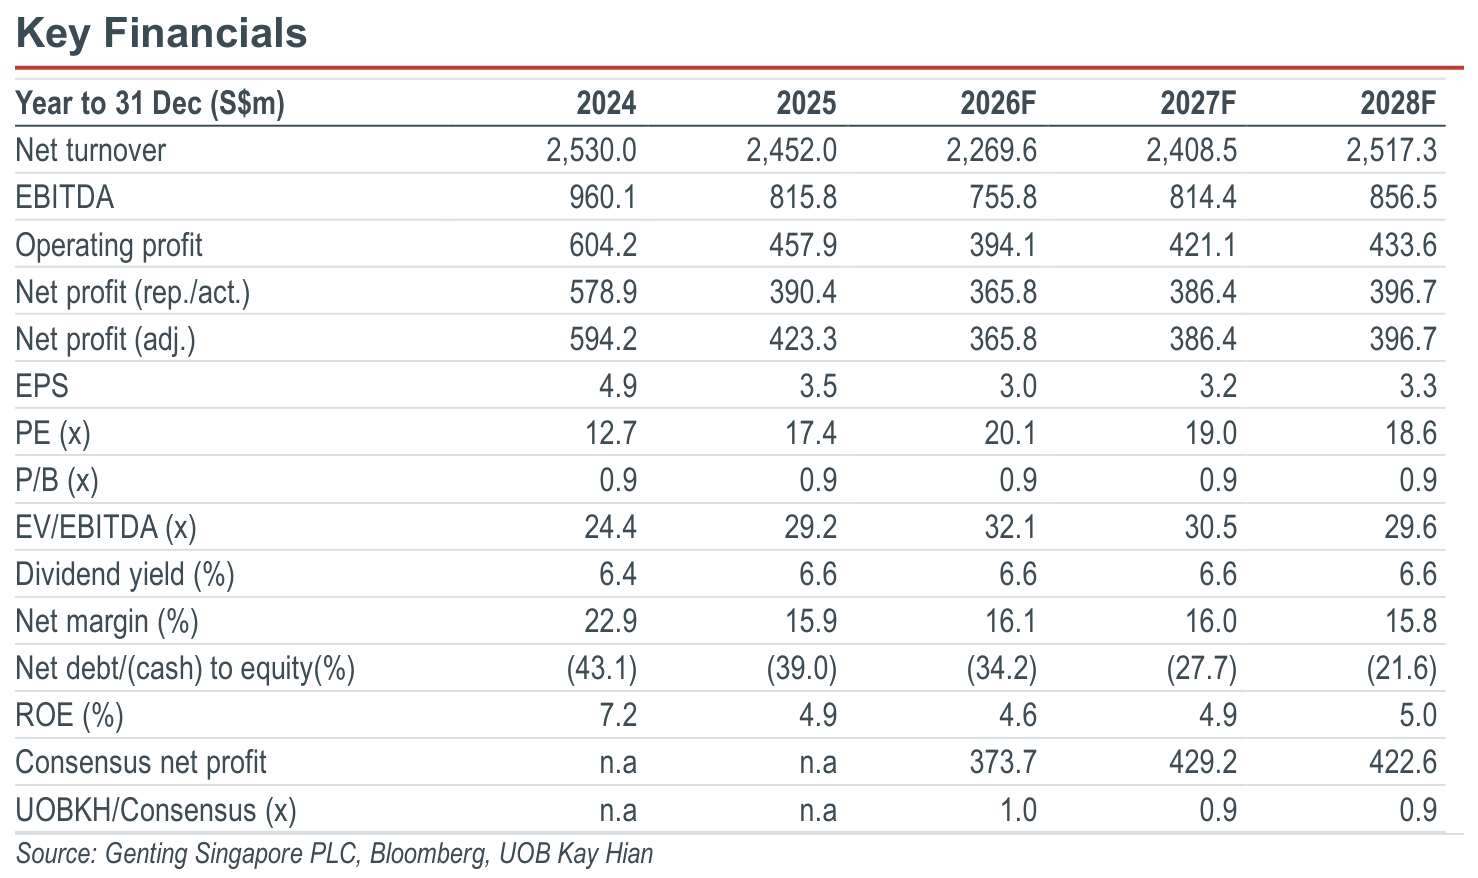
- We remain neutral on GENS’ short- to medium-term outlook, but expect support from a commendable dividend yield (6.6%). Maintain HOLD with a lower target price of S$0.65 (from S$0.70) as we reduce our 2026-27 EBITDA forecasts.
Analysis
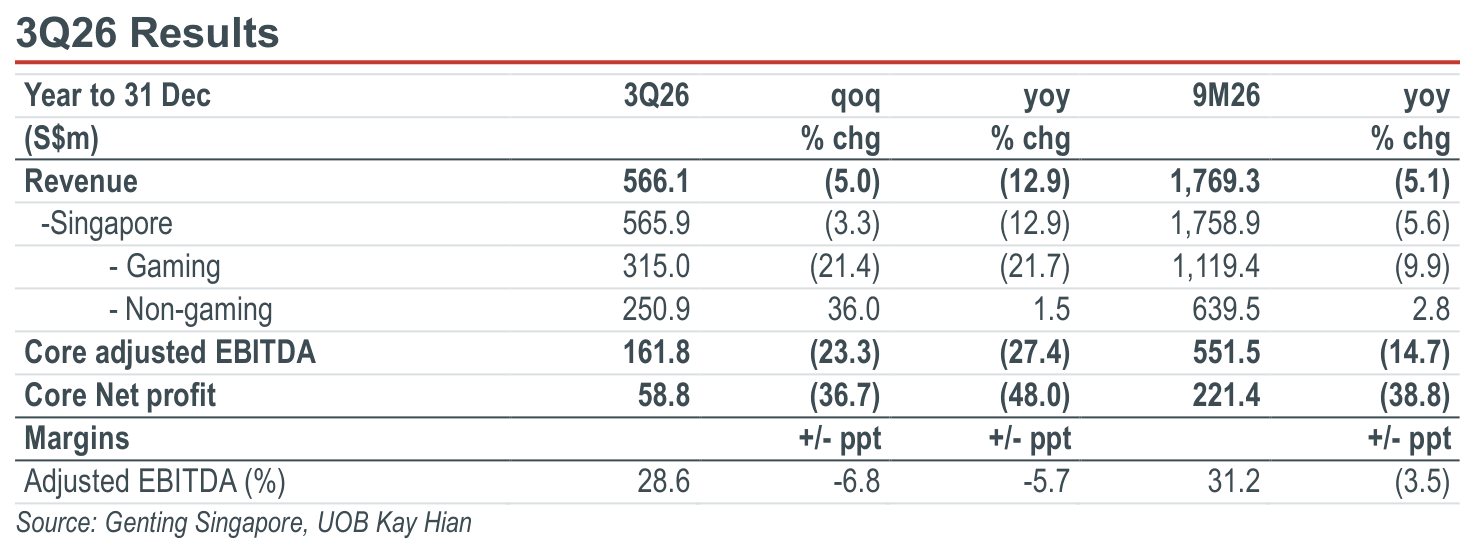
- 3Q26: Below expectations. Resort World Sentosa’s (RWS) 3Q26 revenue (-5% qoq, -13% yoy) and EBITDA (-23% qoq; -27% yoy) declined meaningfully yoy. Earnings were weaker yoy, mainly due to softer VIP volume and a lower win rate. 9M26 EBITDA represented only 68% of our and consensus full-year forecasts respectively.
- Gaming statistics dropped on weaker volume and VIP luck factor. 3Q26 gaming revenue declined significantly (-22% yoy). This mainly reflects a weaker VIP rolling chip volume (-32% yoy) and win percentage of 2.74% (3Q25: 3.1%), which have dragged down VIP’s gross gaming revenue (GGR) by 40% yoy. Meanwhile, mass GGR is estimated to have also fallen modestly by 5% yoy as overall RWS footfall was impacted by a lower number of hotel rooms available due to the ongoing renovation and modernisation efforts.
Highlights
- 3Q26 results came in below expectations, with earnings declining steeply due to lower gaming statistics and higher operating expenses.
- We remain neutral on GENS’ short- to medium-term outlook, but expect support from a commendable dividend yield (6.6%). Maintain HOLD with a lower target price of S$0.65 (from S$0.70) as we reduce our 2026-27 EBITDA forecasts.
Analysis
- 3Q26: Below expectations. Resort World Sentosa’s (RWS) 3Q26 revenue (-5% qoq, -13% yoy) and EBITDA (-23% qoq; -27% yoy) declined meaningfully yoy. Earnings were weaker yoy, mainly due to softer VIP volume and a lower win rate. 9M26 EBITDA represented only 68% of our and consensus full-year forecasts respectively.
- Gaming statistics dropped on weaker volume and VIP luck factor. 3Q26 gaming revenue declined significantly (-22% yoy). This mainly reflects a weaker VIP rolling chip volume (-32% yoy) and win percentage of 2.74% (3Q25: 3.1%), which have dragged down VIP’s gross gaming revenue (GGR) by 40% yoy. Meanwhile, mass GGR is estimated to have also fallen modestly by 5% yoy as overall RWS footfall was impacted by a lower number of hotel rooms available due to the ongoing renovation and modernisation efforts.
HOLD (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$0.61
S$0.65
6.56%
S$0.70
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

25 Sept 2026
Wilmar International (WIL SP): Integrated Business Model To Navigate The Challenging Operating Environment

3 Nov 2026
Lendlease Global Commercial REIT (LREIT SP) - 1QFY27: Retail Momentum Builds; Planning More AEIs

9 Oct 2026
Riverstone Holdings (RSTON SP): AI, Forex And Pricing Tailwinds Emerging; 7% Yield Is Attractive
Our latest research

13 Nov 2026
SATS (SATS SP): 1HFY27: Steady Headline Earnings Supported By Tax Items; Cost Pressures Peak, Margins Poised To Recover

13 Nov 2026
Food Empire Holdings (FEH SP): 3Q26: Healthy Growth; Expect Better Margins And Earnings hoh For 2H26

13 Nov 2026