
Company Coverage
Lendlease Global Commercial REIT (LREIT SP) - 1QFY27: Retail Momentum Builds; Planning More AEIs
BUY (Maintained)
Current price:
Target price:
Upside:
S$0.555
S$0.800
+
Analyst
Highlights
- LREIT delivered a strong retail performance in 1QFY27, with rental reversion of 10.0% and like-for-like tenant sales growth of 8.1% yoy. Occupancy at PLQ Mall temporarily dipped 2.3ppt qoq to 94% due to an ongoing AEI. The operating metrics for LREIT’s retail properties were above our expectation.
- PLQ Mall’s enhancement is scheduled to complete by end-26 and Grange House’s opening by mid-27. PLQ Mall will provide a full 12-month contribution in FY27. Management will evaluate AEIs for 313@Somerset and Jem.
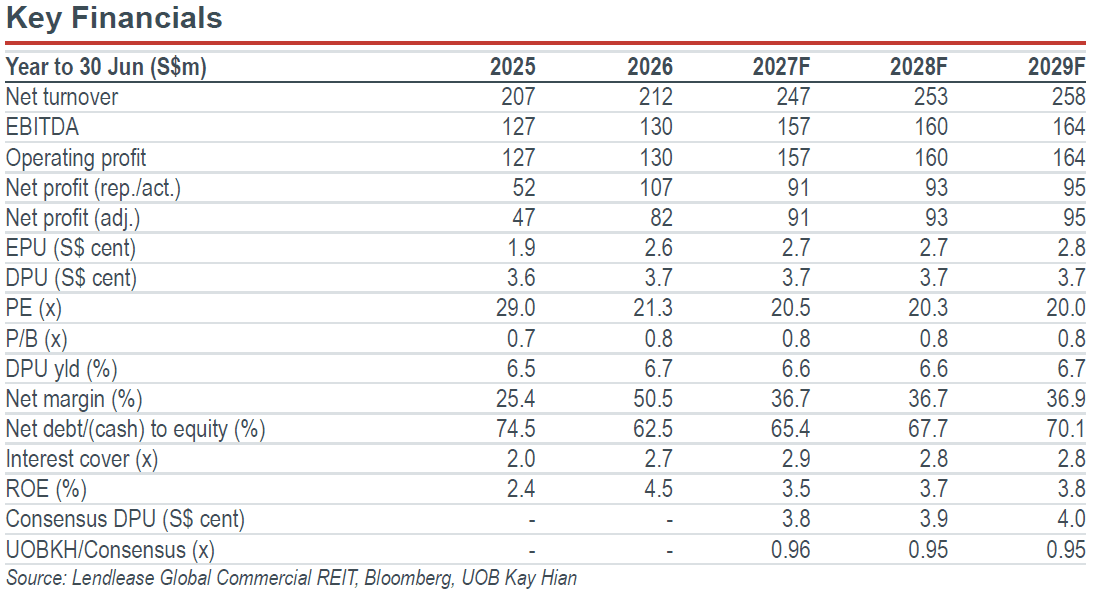
- Management continues to pursue potential acquisitions in Singapore and the divestment of Building 3 in Milan. LREIT provides an attractive FY27 DPU yield of 6.6%. Maintain BUY. Target price: S$0.80.
Analysis
- Lendlease Global Commercial REIT (LREIT) delivered positive retail leasing momentum in its 1QFY27 business update:
- Positive leasing momentum and impressive tenant sales. Retail rental reversion was +10.0% (PLQ Mall and 313@Somerset: low teens; Jem: high single-digit). On a like-for-like basis excluding PLQ Mall, tenant sales increased 8.1% yoy due to new tenancies secured in FY26 and strong growth in visitation by 6.7% yoy. By trade sector, food & beverage, beauty & wellness, gold & jewelleries and sports & athleisure performed well. New retail offerings include Gentlewoman (Bangkok-born fashion label) and LSOUL (contemporary fashion brand from Vietnam) at 313@Somerset.
- Retail occupancy remains high despite temporary PLQ vacancies. Retail committed occupancy eased 0.3ppt qoq to 98.2%, mainly due to space reconfiguration at PLQ Mall. Jem remained fully occupied, while occupancy at 313@somerset was 99.0%. Occupancy at PLQ Mall eased 2.3ppt qoq to 94% due to an ongoing AEI. Office occupancy unchanged at 89.1%. Tenant retention was 87% by NLA for completed renewals in 1QFY27. Portfolio WALE was 4.4 years by NLA. Only 4.8% of NLA is due for renewal in FY27.
- Lower financing costs. Weighted average cost of debt declined 59bp yoy to 2.50% in 1QFY27, mainly from refinancing PLQ Mall loans at lower rates. Gearing eased 0.2ppt qoq to 38.7% as of Sep 26. Fixed-rate borrowings remained at 68%, and average debt maturity was 2.6 years. Interest coverage ratio remained 2.1x, and benefits from the Jun 26 perpetual securities refinancing should accrue progressively.
Highlights
- LREIT delivered a strong retail performance in 1QFY27, with rental reversion of 10.0% and like-for-like tenant sales growth of 8.1% yoy. Occupancy at PLQ Mall temporarily dipped 2.3ppt qoq to 94% due to an ongoing AEI. The operating metrics for LREIT’s retail properties were above our expectation.
- PLQ Mall’s enhancement is scheduled to complete by end-26 and Grange House’s opening by mid-27. PLQ Mall will provide a full 12-month contribution in FY27. Management will evaluate AEIs for 313@Somerset and Jem.
- Management continues to pursue potential acquisitions in Singapore and the divestment of Building 3 in Milan. LREIT provides an attractive FY27 DPU yield of 6.6%. Maintain BUY. Target price: S$0.80.
Analysis
- Lendlease Global Commercial REIT (LREIT) delivered positive retail leasing momentum in its 1QFY27 business update:
- Positive leasing momentum and impressive tenant sales. Retail rental reversion was +10.0% (PLQ Mall and 313@Somerset: low teens; Jem: high single-digit). On a like-for-like basis excluding PLQ Mall, tenant sales increased 8.1% yoy due to new tenancies secured in FY26 and strong growth in visitation by 6.7% yoy. By trade sector, food & beverage, beauty & wellness, gold & jewelleries and sports & athleisure performed well. New retail offerings include Gentlewoman (Bangkok-born fashion label) and LSOUL (contemporary fashion brand from Vietnam) at 313@Somerset.
- Retail occupancy remains high despite temporary PLQ vacancies. Retail committed occupancy eased 0.3ppt qoq to 98.2%, mainly due to space reconfiguration at PLQ Mall. Jem remained fully occupied, while occupancy at 313@somerset was 99.0%. Occupancy at PLQ Mall eased 2.3ppt qoq to 94% due to an ongoing AEI. Office occupancy unchanged at 89.1%. Tenant retention was 87% by NLA for completed renewals in 1QFY27. Portfolio WALE was 4.4 years by NLA. Only 4.8% of NLA is due for renewal in FY27.
- Lower financing costs. Weighted average cost of debt declined 59bp yoy to 2.50% in 1QFY27, mainly from refinancing PLQ Mall loans at lower rates. Gearing eased 0.2ppt qoq to 38.7% as of Sep 26. Fixed-rate borrowings remained at 68%, and average debt maturity was 2.6 years. Interest coverage ratio remained 2.1x, and benefits from the Jun 26 perpetual securities refinancing should accrue progressively.
BUY (Maintained)
Current price:
Target price:
Upside:
S$0.555
S$0.800
+
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

13 Oct 2026
Frasers Centrepoint Trust (FCT SP): Benefitting From Population And Job Growth In North Region

6 Oct 2026
CapitaLand Ascott Trust (CLAS SP): Disciplined Reconstitution To Pivot Towards The Living Sector

7 Oct 2026
Sasseur REIT (SASSR SP) - Sasseur Site Visit: Value Hunters Keep Chongqing Busy
Our latest research

2 Nov 2026
CapitaLand Ascendas REIT (CLAR SP) - 3Q26: Uptick In Occupancy From Singapore And The US

2 Nov 2026
NetLink NBN Trust (NETLINK SP) - 1HFY27: EBITDA In Line; Higher Depreciation A Drag To Earnings

30 Oct 2026