
Company Coverage
Singapore Airlines (SIA SP): 1HFY27: Results Miss Our Expectations; Expect 2HFY27 To Remain Weighed Down By Elevated Jet Fuel Prices
SELL (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$7.25
S$6.65
-8.3%
S$6.16
Analyst
Highlights
- SIA’s 2QFY27 earnings of S$210m missed our guided range of US$230m-370m, driven by weaker-than-expected pax yields. 2QFY27 would have been a bigger miss if we exclude Air India’s one-off accounting gains.
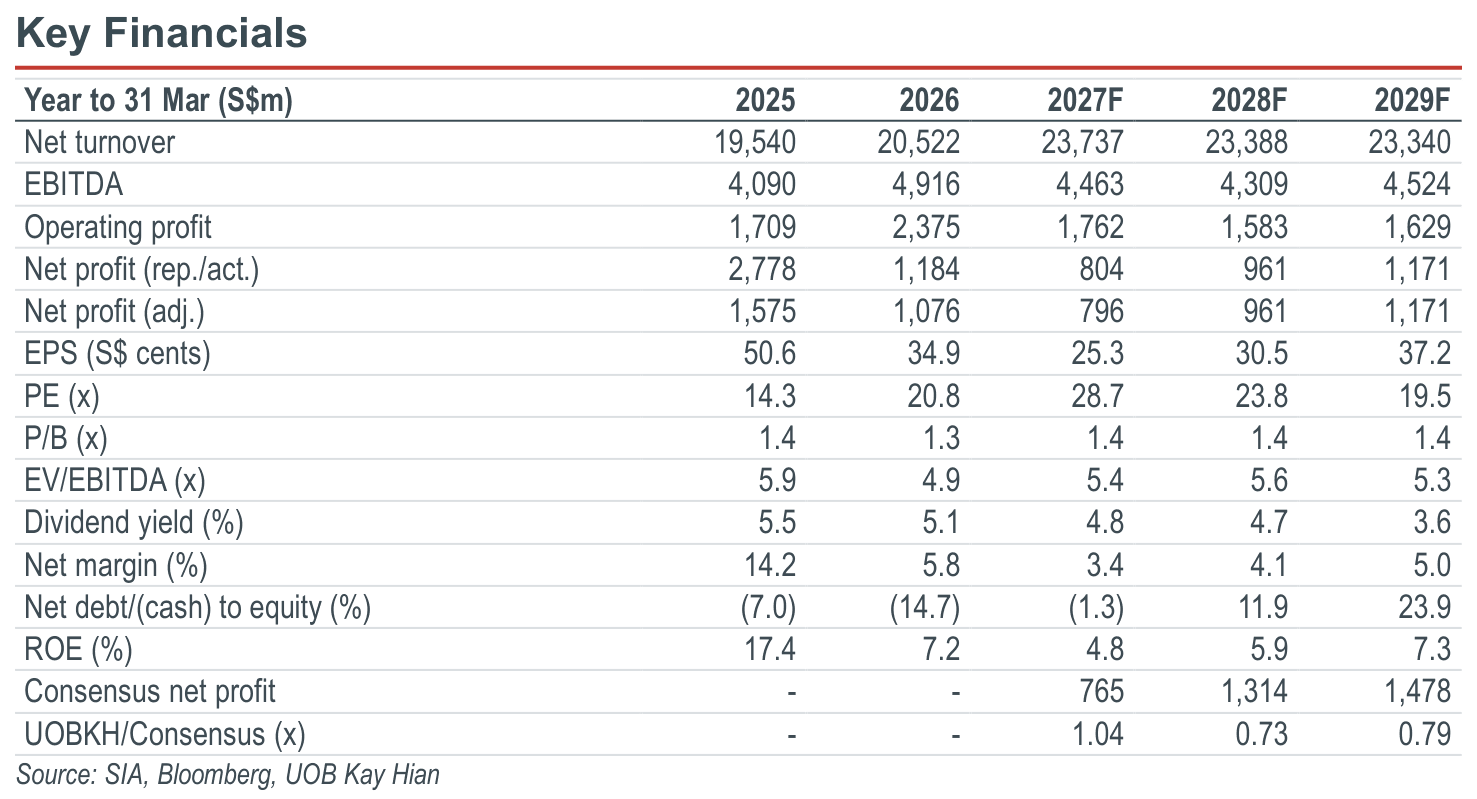
- Despite having pulled back from recent peaks, elevated jet fuel prices are likely to still weigh on SIA’s 3Q/2HFY27 performance, leading to our forecasted 33%/29% yoy drop in SIA’s 3Q/2HFY27 earnings respectively.
- SIA’s current valuation (at 1.40x FY27F P/B, or 1.6SD above historical mean) appears to have priced in an imminent resolution to the Middle East unrest, although significant uncertainties remain.
- Maintain SELL; target price raised to S$6.65 (based on 1.29x FY27F P/B).
Analysis
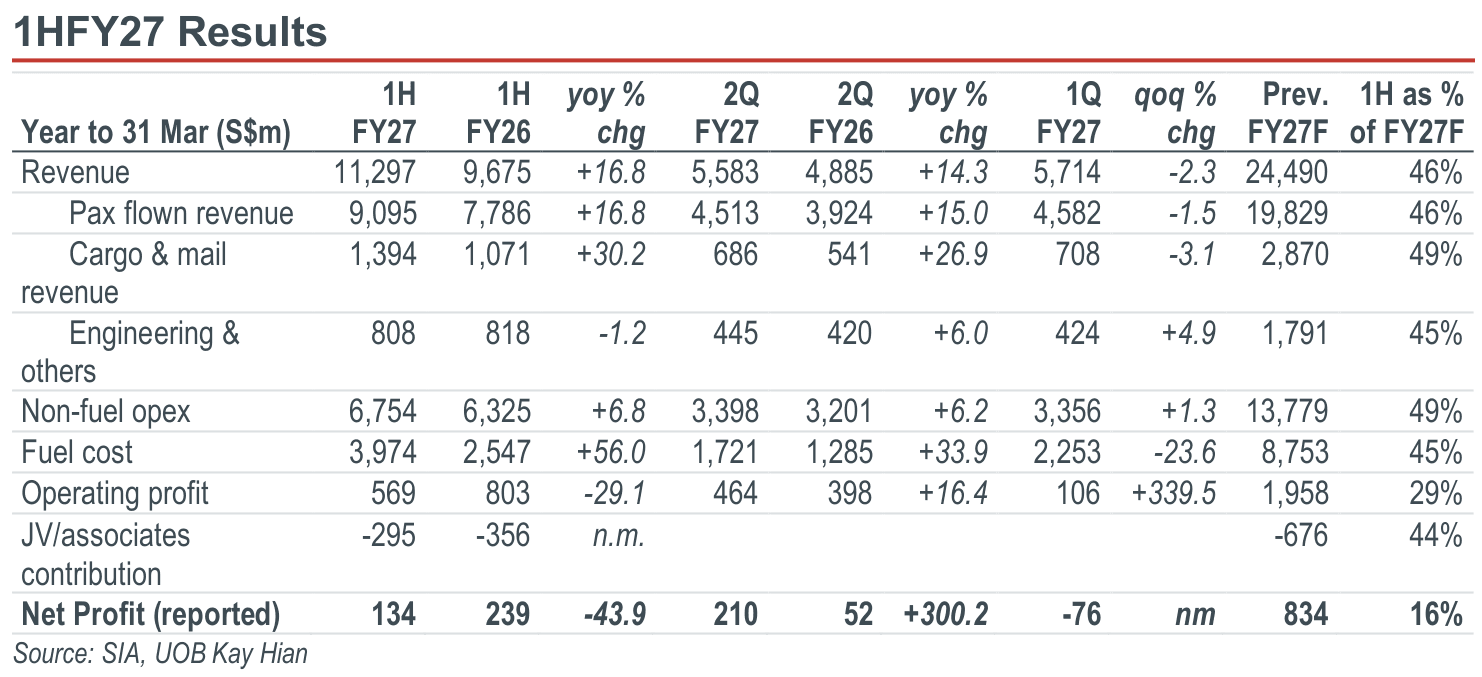
- 2QFY27 results missed our expectations… Singapore Airlines’ (SIA) 1HFY27 reported net profit dropped 44% yoy to S$134m. Despite having improved yoy and qoq from 1QFY27’s and 2QFY26’s very low bases, 2QFY26 net profit of S$210m was below our guided range of S$230m-370m.
- …due to lower-than-projected pax yields. Pax yields rose 12.2% yoy, below our projected 17.0% increase, as fuel cost pass-through to customers came in lower than our expectations. Cargo yields rose 22.3% yoy, broadly in line with our forecast, while non-fuel opex/ATK increased 3.7% yoy, also in line. Consequently, 2QFY27 operating profit of S$464m (+16.4% yoy) was below our projected range of S$565m-745m.
Highlights
- SIA’s 2QFY27 earnings of S$210m missed our guided range of US$230m-370m, driven by weaker-than-expected pax yields. 2QFY27 would have been a bigger miss if we exclude Air India’s one-off accounting gains.
- Despite having pulled back from recent peaks, elevated jet fuel prices are likely to still weigh on SIA’s 3Q/2HFY27 performance, leading to our forecasted 33%/29% yoy drop in SIA’s 3Q/2HFY27 earnings respectively.
- SIA’s current valuation (at 1.40x FY27F P/B, or 1.6SD above historical mean) appears to have priced in an imminent resolution to the Middle East unrest, although significant uncertainties remain.
- Maintain SELL; target price raised to S$6.65 (based on 1.29x FY27F P/B).
Analysis
- 2QFY27 results missed our expectations… Singapore Airlines’ (SIA) 1HFY27 reported net profit dropped 44% yoy to S$134m. Despite having improved yoy and qoq from 1QFY27’s and 2QFY26’s very low bases, 2QFY26 net profit of S$210m was below our guided range of S$230m-370m.
- …due to lower-than-projected pax yields. Pax yields rose 12.2% yoy, below our projected 17.0% increase, as fuel cost pass-through to customers came in lower than our expectations. Cargo yields rose 22.3% yoy, broadly in line with our forecast, while non-fuel opex/ATK increased 3.7% yoy, also in line. Consequently, 2QFY27 operating profit of S$464m (+16.4% yoy) was below our projected range of S$565m-745m.
SELL (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$7.25
S$6.65
-8.3%
S$6.16
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

5 Nov 2026
SIA Engineering (SIE SP) - 1HFY27: Results In Line; Steady Earnings Despite Expansion-related Gestation Costs

13 Nov 2026
SATS (SATS SP): 1HFY27: Steady Headline Earnings Supported By Tax Items; Cost Pressures Peak, Margins Poised To Recover

29 Oct 2026
Aztech Global (AZTECH SP): 3Q26: Earnings In Line; Competition Remains Intense
Our latest research
13 Nov 2026
SATS (SATS SP): 1HFY27: Steady Headline Earnings Supported By Tax Items; Cost Pressures Peak, Margins Poised To Recover

13 Nov 2026
Food Empire Holdings (FEH SP): 3Q26: Healthy Growth; Expect Better Margins And Earnings hoh For 2H26

13 Nov 2026