
Company Coverage
Singapore Technologies Engineering (STE SP): 3Q26: Revenue Broadly In Line; Expect Strong Closing For 2026 And Sustainable Healthy Growth In the Medium Term
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$9.67
S$10.97
13.4%
S$11.75
Analyst
Highlights
- STE’s 3Q/9M26 revenue came in broadly in line with our expectations, forming 25%/73% of our full-year forecast, respectively.
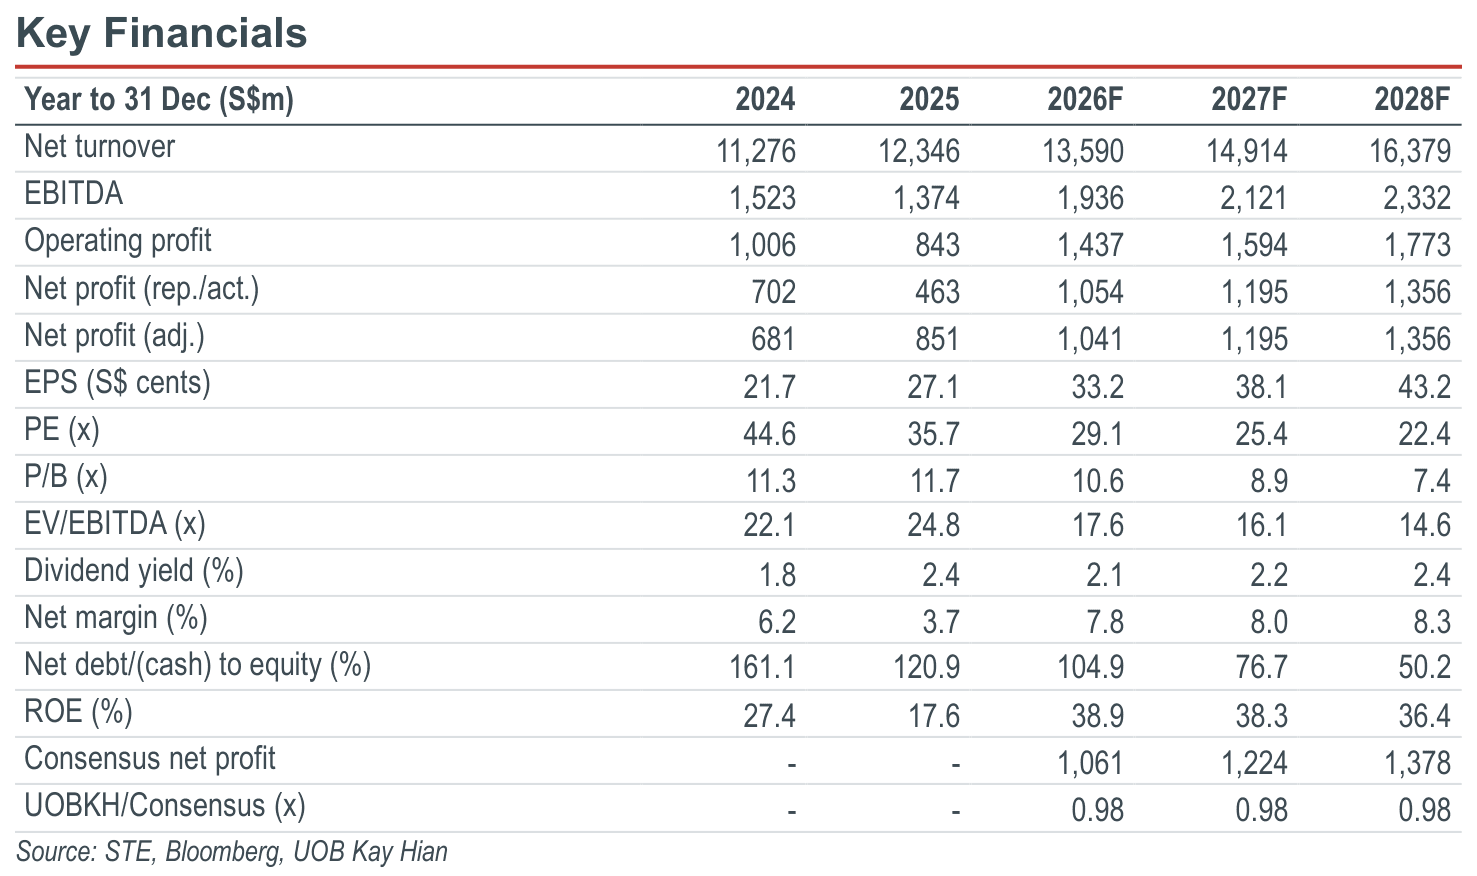
- Management guides for a strong closing for 2026, and we remain upbeat on STE’s medium-term growth trajectory, backed by a record-high orderbook and further improvement in margins.
- Maintain BUY as we continue to like STE, though our target price is moderated to S$10.97 (based on 25.2x 2028F PE, or 1SD above mean), reflecting the recent global defence sector de-rating and a higher risk-free rate environment.
Analysis
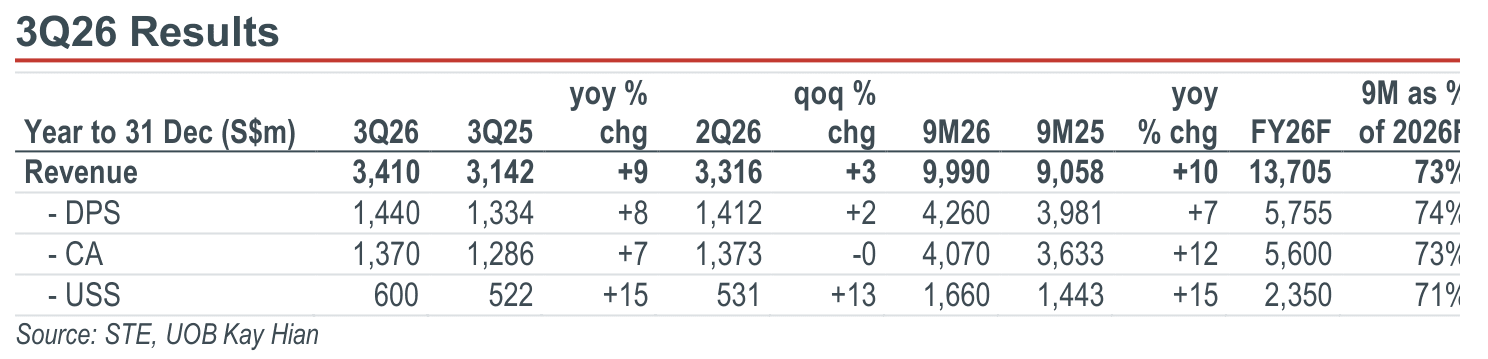
- 3Q26 revenue broadly in line. Singapore Technologies Engineering’s (STE) 3Q26 revenue of S$3.4b (+9% yoy) was broadly in line with our expectations, with 9M26 revenue of S$10.0b (+10% yoy), forming 73% of our full-year forecast. If adjusted for the Leeboy disposal (completed in Sep 25) and foreign currency fluctuations, STE’s 3Q26 revenue would have grown 11% yoy.
- Broad-based growth across three segments. Revenue of Defence & Public Security (DPS) rose 8% yoy in 3Q26, driven by higher revenue led by Marine and Digital Systems & Cybersecurity businesses. Revenue of Commercial Aerospace (CA) rose 7%, driven by higher revenue from Engine MRO and Nacelle production. Revenue of Urban Solutions & Satcom (USS) rose 15%, backed by higher revenue from both Urban Solution and Satcom businesses.
Highlights
- STE’s 3Q/9M26 revenue came in broadly in line with our expectations, forming 25%/73% of our full-year forecast, respectively.
- Management guides for a strong closing for 2026, and we remain upbeat on STE’s medium-term growth trajectory, backed by a record-high orderbook and further improvement in margins.
- Maintain BUY as we continue to like STE, though our target price is moderated to S$10.97 (based on 25.2x 2028F PE, or 1SD above mean), reflecting the recent global defence sector de-rating and a higher risk-free rate environment.
Analysis
- 3Q26 revenue broadly in line. Singapore Technologies Engineering’s (STE) 3Q26 revenue of S$3.4b (+9% yoy) was broadly in line with our expectations, with 9M26 revenue of S$10.0b (+10% yoy), forming 73% of our full-year forecast. If adjusted for the Leeboy disposal (completed in Sep 25) and foreign currency fluctuations, STE’s 3Q26 revenue would have grown 11% yoy.
- Broad-based growth across three segments. Revenue of Defence & Public Security (DPS) rose 8% yoy in 3Q26, driven by higher revenue led by Marine and Digital Systems & Cybersecurity businesses. Revenue of Commercial Aerospace (CA) rose 7%, driven by higher revenue from Engine MRO and Nacelle production. Revenue of Urban Solutions & Satcom (USS) rose 15%, backed by higher revenue from both Urban Solution and Satcom businesses.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$9.67
S$10.97
13.4%
S$11.75
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

16 Nov 2026
CSE Global (CSE SP): 3Q26: Strong Order Momentum; Margin Recovery Expected In 2H26

28 Oct 2026
iFAST Corporation (IFAST SP): 9M26: Earnings Beat; Record AUA And Strong Banking Growth

16 Nov 2026
First Resources (FR SP): 3Q26: Above Expectations On Strong Output; Consensus Looks Too Low For 4Q
Our latest research
16 Nov 2026
CSE Global (CSE SP): 3Q26: Strong Order Momentum; Margin Recovery Expected In 2H26
16 Nov 2026
First Resources (FR SP): 3Q26: Above Expectations On Strong Output; Consensus Looks Too Low For 4Q

16 Nov 2026