
Company Coverage
UMS Integration (UMSH SP): 3Q26: Earnings In Line; New Customer Ramp-up Drives Growth
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$1.89
S$2.40
+27.0%
S$3.27
Analyst
Highlights
- 3Q26 earnings rose 102% yoy and 9% qoq to S$21m. 9M26 earnings of S$54.5m (+78% yoy) were largely in line at 76% of our full-year forecast.
- 3Q26 revenue grew 61% yoy and 9% qoq to S$95m, led by an 87% yoy rise in semiconductor component sales to S$56m.
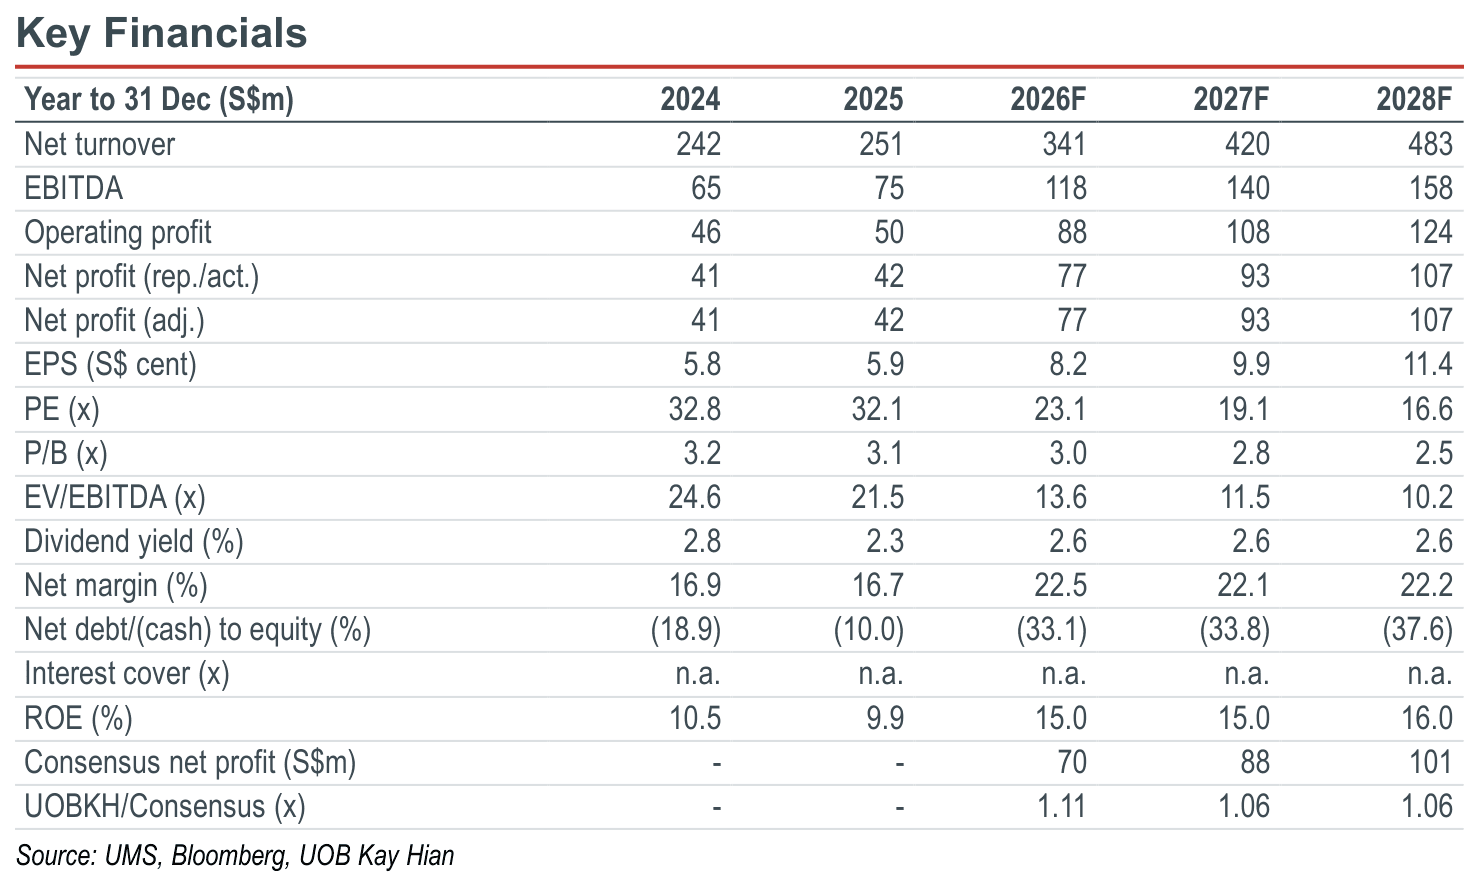
- Customer demand and outlook remain robust. Capacity expansion in Malaysia and Vietnam supports future growth. Maintain BUY with a 27% lower target price of S$2.40.
Analysis
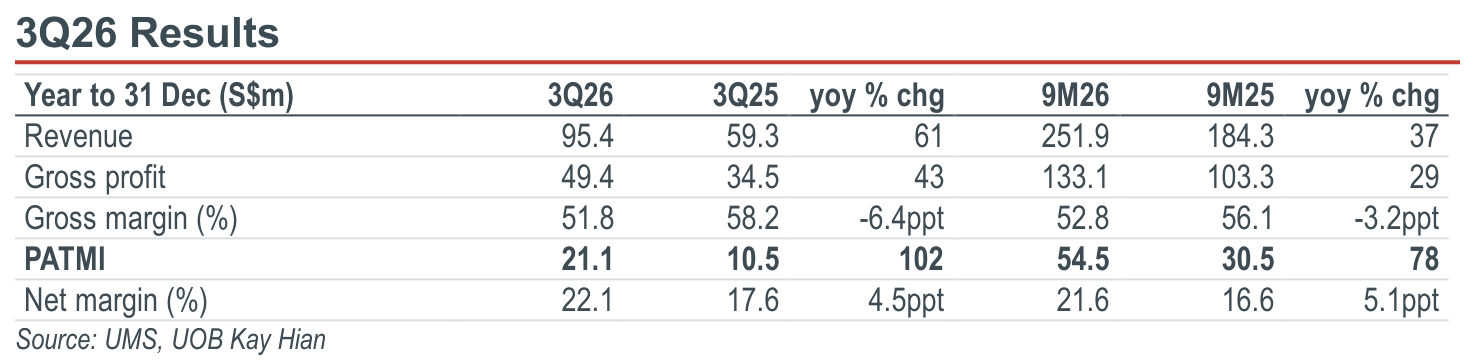
- 9M26 earnings in line with expectations. UMS Integration (UMS) reported 9M26 earnings of S$54.5m (+78% yoy), which accounts for 76% of our 2026 forecast. 3Q26 earnings rose 102% yoy and 8.7% qoq to S$21.1m. 9M26 revenue of S$251.9m already exceeds the S$251.1m revenue recorded for full-year 2025.
- New customer ramp-up drives semiconductor growth. 3Q26 revenue increased 61% yoy/9% qoq to S$95.4m. Semiconductor sales rose 65% yoy to S$83.1m, led by an 87% increase in component sales to S$55.8m. Integrated system sales grew 32% yoy to S$27.3m but fell 19% qoq due to OEM parts shortages, which management expects to ease. Aerospace sales rose 55% yoy to S$9.7m. Malaysia revenue surged 209% yoy to S$24.3m as production for the new customer accelerated; Taiwan and South Korea sales grew 94% and 86% respectively.
- Margins softened, but cash generation remained strong. 3Q26 gross material margin fell to 51.8% from 58.2% a year earlier, due to less favourable product mix as component sales to the new customer ramped up. A S$1.6m forex gain also supported earnings. Operating cash flow was S$21.2m in 3Q26 and S$52.7m in 9M26. A third interim dividend of 1.0 S cent/share was declared.
Highlights
- 3Q26 earnings rose 102% yoy and 9% qoq to S$21m. 9M26 earnings of S$54.5m (+78% yoy) were largely in line at 76% of our full-year forecast.
- 3Q26 revenue grew 61% yoy and 9% qoq to S$95m, led by an 87% yoy rise in semiconductor component sales to S$56m.
- Customer demand and outlook remain robust. Capacity expansion in Malaysia and Vietnam supports future growth. Maintain BUY with a 27% lower target price of S$2.40.
Analysis
- 9M26 earnings in line with expectations. UMS Integration (UMS) reported 9M26 earnings of S$54.5m (+78% yoy), which accounts for 76% of our 2026 forecast. 3Q26 earnings rose 102% yoy and 8.7% qoq to S$21.1m. 9M26 revenue of S$251.9m already exceeds the S$251.1m revenue recorded for full-year 2025.
- New customer ramp-up drives semiconductor growth. 3Q26 revenue increased 61% yoy/9% qoq to S$95.4m. Semiconductor sales rose 65% yoy to S$83.1m, led by an 87% increase in component sales to S$55.8m. Integrated system sales grew 32% yoy to S$27.3m but fell 19% qoq due to OEM parts shortages, which management expects to ease. Aerospace sales rose 55% yoy to S$9.7m. Malaysia revenue surged 209% yoy to S$24.3m as production for the new customer accelerated; Taiwan and South Korea sales grew 94% and 86% respectively.
- Margins softened, but cash generation remained strong. 3Q26 gross material margin fell to 51.8% from 58.2% a year earlier, due to less favourable product mix as component sales to the new customer ramped up. A S$1.6m forex gain also supported earnings. Operating cash flow was S$21.2m in 3Q26 and S$52.7m in 9M26. A third interim dividend of 1.0 S cent/share was declared.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$1.89
S$2.40
+27.0%
S$3.27
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

30 Oct 2026
Keppel (KEP SP): Decent Headline Earnings Growth But Slower-than-expected Core Earnings Growth In 3Q26

29 Oct 2026
Aztech Global (AZTECH SP): 3Q26: Earnings In Line; Competition Remains Intense

10 Nov 2026
Venture Corporation (VMS SP): 3Q26: Broadening Growth Led By Portfolio B; Maintain BUY
Our latest research

12 Nov 2026
City Developments (CIT SP): Resilient Operating Performance

12 Nov 2026
Yangzijiang Shipbuilding (YZJSGD SP): Strong New Contract Wins Bring Orderbook To A New Record-high Level, Extending Earnings Visibility Through 2030

12 Nov 2026