
Company Coverage
Valuetronics (VALUE SP): 1HFY27: Dividend Up 75%; ICE Drives Growth
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$0.93
S$1.40
50.5%
S$1.88
Analyst
Analyst
Highlights
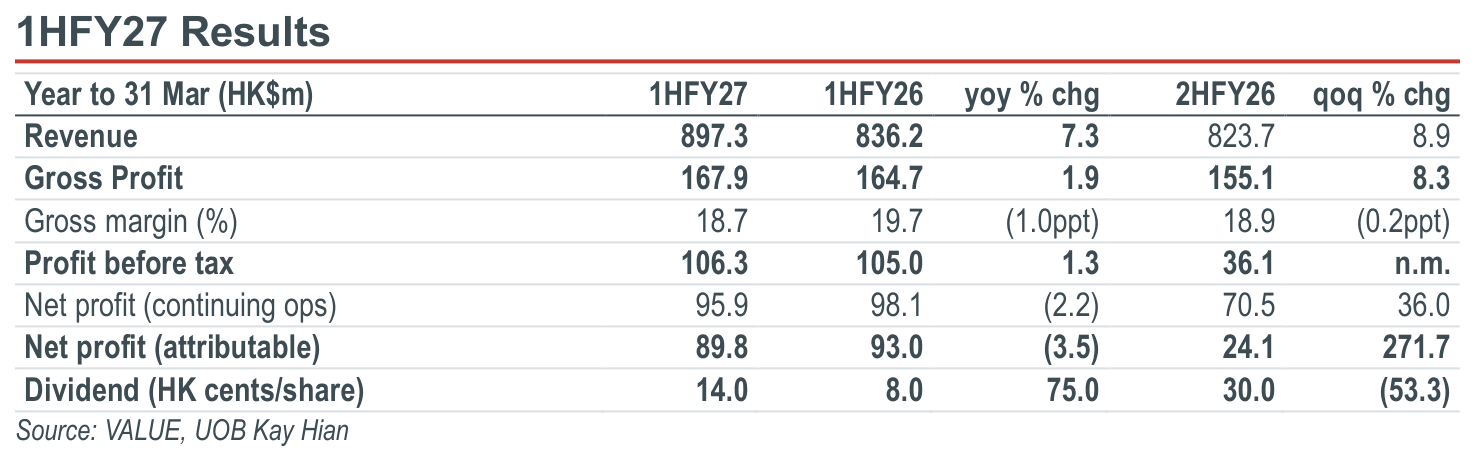
- 1HFY27 revenue of HK$897.3m (+7.3% yoy) and PATMI of HK$89.8m (-3.5% yoy) are ahead of the run-rate, representing 53.8% and 56.1% of our FY27 forecasts respectively.
- Interim dividends surged 75% yoy to 14 HK cents/share, while ICE revenue grew 18.6% yoy to HK$837.9m. Strong net cash of HK$1.15b supports the HK$300m capital return programme.
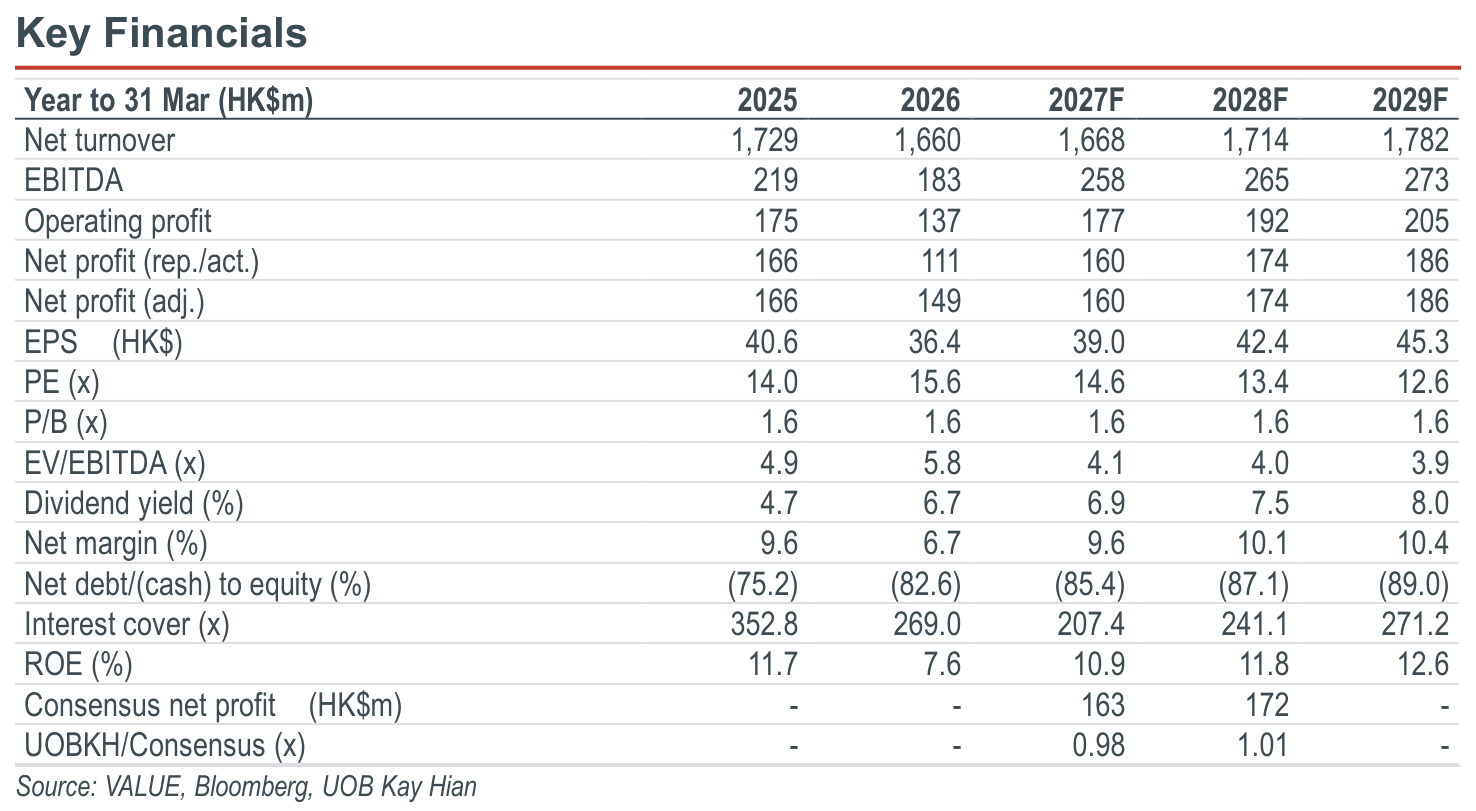
- Maintain BUY with a 25% lower target price of S$1.40, pegged to 16x FY28F ex-cash PE (+1SD), down from 19x (+2SD) to reflect the broader tech sector de-rating.
Analysis
- Revenue and PATMI ahead of run-rate. Revenue rose 7.3% yoy to HK$897.3m, driven by higher contributions from ICE's network access solutions and captioned phone customers. Reported PATMI declined 3.5% yoy to HK$89.8m, weighed down by higher component costs and increased taxes following changes to tax incentives in Vietnam. Revenue and PATMI accounted for 53.8% and 56.1% of our FY27 forecasts respectively. PBT grew 1.3% yoy to HK$106.3m despite a 1.0ppt decline in gross profit margin to 18.7% amid semiconductor supply constraints. Excluding discontinued GPU cloud operations, net profit declined 2.2% yoy to HK$95.9m.
- Interim dividend jumps 75% to 14 HK cents/share. Management declared an ordinary interim dividend of 8 HK cents/share (1HFY26: 4 HK cents) and a special interim dividend of 6 HK cents/share (1HFY26: 4 HK cents), bringing total interim dividends to 14 HK cents/share (+75% yoy). This represents a payout ratio of approximately 59.8%, in line with its revised dividend policy of 50-70% of net profit, reinforcing management's commitment to enhancing shareholder returns through its HK$300m capital return programme.
Highlights
- 1HFY27 revenue of HK$897.3m (+7.3% yoy) and PATMI of HK$89.8m (-3.5% yoy) are ahead of the run-rate, representing 53.8% and 56.1% of our FY27 forecasts respectively.
- Interim dividends surged 75% yoy to 14 HK cents/share, while ICE revenue grew 18.6% yoy to HK$837.9m. Strong net cash of HK$1.15b supports the HK$300m capital return programme.
- Maintain BUY with a 25% lower target price of S$1.40, pegged to 16x FY28F ex-cash PE (+1SD), down from 19x (+2SD) to reflect the broader tech sector de-rating.
Analysis
- Revenue and PATMI ahead of run-rate. Revenue rose 7.3% yoy to HK$897.3m, driven by higher contributions from ICE's network access solutions and captioned phone customers. Reported PATMI declined 3.5% yoy to HK$89.8m, weighed down by higher component costs and increased taxes following changes to tax incentives in Vietnam. Revenue and PATMI accounted for 53.8% and 56.1% of our FY27 forecasts respectively. PBT grew 1.3% yoy to HK$106.3m despite a 1.0ppt decline in gross profit margin to 18.7% amid semiconductor supply constraints. Excluding discontinued GPU cloud operations, net profit declined 2.2% yoy to HK$95.9m.
- Interim dividend jumps 75% to 14 HK cents/share. Management declared an ordinary interim dividend of 8 HK cents/share (1HFY26: 4 HK cents) and a special interim dividend of 6 HK cents/share (1HFY26: 4 HK cents), bringing total interim dividends to 14 HK cents/share (+75% yoy). This represents a payout ratio of approximately 59.8%, in line with its revised dividend policy of 50-70% of net profit, reinforcing management's commitment to enhancing shareholder returns through its HK$300m capital return programme.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$0.93
S$1.40
50.5%
S$1.88
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

2 Nov 2026
NetLink NBN Trust (NETLINK SP) - 1HFY27: EBITDA In Line; Higher Depreciation A Drag To Earnings

6 Nov 2026
DBS Group Holdings (DBS SP) - 3Q26: Focus On Resiliency And Growth Of Core Franchise

29 Oct 2026
UI Boustead REIT (UIBREIT SP): 1HFY27: Steady Progress On Leasing And Co-development
Our latest research

12 Nov 2026
City Developments (CIT SP): Resilient Operating Performance

12 Nov 2026
UMS Integration (UMSH SP): 3Q26: Earnings In Line; New Customer Ramp-up Drives Growth

12 Nov 2026