
Key Indices
Top Stories
Company Results | Bumitama Agri (BAL SP/BUY/S$1.39/Target: S$2.54)
- Bumitama’s 9M26 results were below expectations following a lower-than-expected sales volume due to logistic disruptions. Nonetheless, FFB production remains positive and is on track to exceed the upper end of the group's 5-10% yoy growth target. While we trim our 2026 earnings forecast by 12% to reflect the weaker sales volume and delayed sales realisation, we maintain our BUY call and unchanged target price of S$2.54, based on 14x 2027F PE.
Company Results | CSE Global (CSE SP/BUY/S$0.86/Target: S$1.30)
- CSE’s 3Q26 revenue rose 25.4% yoy to S$323.2m, bringing 9M26 revenue to 78.6% of our 2026 forecast, in line with expectations. Order intake surged 197.7% yoy to S$434.9m, lifting the orderbook to S$728.5m (+55.8% yoy). Net margin recovery is expected in 2H26 as capacity utilisation improves and major projects enter execution. Maintain BUY with a 27% lower target price of S$1.30.
Company Results | First Resources (FR SP/BUY/S$2.97/Target: S$5.09)
- FR’s 9M26 core net profit of US$338.9m (+41.5% yoy) was above expectations at 78%/80% of our/consensus full-year forecasts respectively. 3Q26 core net profit rose 40.1% yoy to US$122.7m on a 16.4% higher CPO output, but only 2.6% qoq as a larger share of lower-margin bought-in fruit kept margins flat. We raise 2026 net profit by 4.3% and keep 2027-28 unchanged. Maintain BUY with an unchanged target price of S$5.09, based on 14x 2027F PE.
Company Results | Singapore Technologies Engineering (STE SP/BUY/S$9.67/Target: S$10.97)
- STE’s 3Q/9M26 revenue came in broadly in line with our expectations, forming 25%/73% of our full-year forecast, respectively. Management guides for a strong closing for 2026, and we remain upbeat on STE’s medium-term growth trajectory, backed by a record-high orderbook and further improvement in margins. Maintain BUY as we continue to like STE, though our target price is moderated to S$10.97 (based on 25.2x 2028F PE), reflecting the recent global defence sector de-rating and a higher risk-free rate environment.
Market Spotlight
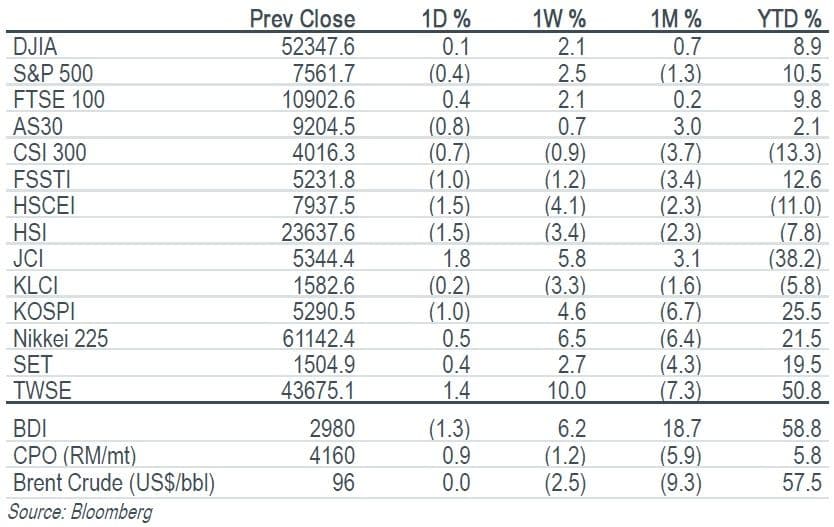
- US stocks were mixed on Friday. Dow Jones rose while S&P 500 and Nasdaq fell as the information technology, consumer discretionary and industrials sectors slid. There were more decliners than advancers on NASDAQ.
- The FSSTI fell 50.86 points to 5,231.84, supported by weakness in DBS, Singtel and ST Engineering. Both mid-and small-cap indices fell, with a broad market decline on a S$1.91b turnover.
What’s Inside
Company Results | Singapore Telecommunications (ST SP/BUY/S$4.11/Target: S$5.50)
- Singtel reported a higher 1HFY27 underlying net profit of S$1.49b (+10 yoy), within expectations and guiding towards a strong finish for the year. Key drivers include positive operating leverage from Optus, NCS and Digital InfraCo as well as higher associate earnings from Airtel and AIS. The group also declared a higher 1HFY27 interim dividend of 9.0 S cents/share. Maintain BUY with a target price of S$5.50.
Technical Analysis
Monthly Technical Regional Indices Watch – STI Outlook
Top Stories
Company Results | Bumitama Agri (BAL SP/BUY/S$1.39/Target: S$2.54)
- Bumitama’s 9M26 results were below expectations following a lower-than-expected sales volume due to logistic disruptions. Nonetheless, FFB production remains positive and is on track to exceed the upper end of the group's 5-10% yoy growth target. While we trim our 2026 earnings forecast by 12% to reflect the weaker sales volume and delayed sales realisation, we maintain our BUY call and unchanged target price of S$2.54, based on 14x 2027F PE.
Company Results | CSE Global (CSE SP/BUY/S$0.86/Target: S$1.30)
- CSE’s 3Q26 revenue rose 25.4% yoy to S$323.2m, bringing 9M26 revenue to 78.6% of our 2026 forecast, in line with expectations. Order intake surged 197.7% yoy to S$434.9m, lifting the orderbook to S$728.5m (+55.8% yoy). Net margin recovery is expected in 2H26 as capacity utilisation improves and major projects enter execution. Maintain BUY with a 27% lower target price of S$1.30.
Company Results | First Resources (FR SP/BUY/S$2.97/Target: S$5.09)
- FR’s 9M26 core net profit of US$338.9m (+41.5% yoy) was above expectations at 78%/80% of our/consensus full-year forecasts respectively. 3Q26 core net profit rose 40.1% yoy to US$122.7m on a 16.4% higher CPO output, but only 2.6% qoq as a larger share of lower-margin bought-in fruit kept margins flat. We raise 2026 net profit by 4.3% and keep 2027-28 unchanged. Maintain BUY with an unchanged target price of S$5.09, based on 14x 2027F PE.
Company Results | Singapore Technologies Engineering (STE SP/BUY/S$9.67/Target: S$10.97)
- STE’s 3Q/9M26 revenue came in broadly in line with our expectations, forming 25%/73% of our full-year forecast, respectively. Management guides for a strong closing for 2026, and we remain upbeat on STE’s medium-term growth trajectory, backed by a record-high orderbook and further improvement in margins. Maintain BUY as we continue to like STE, though our target price is moderated to S$10.97 (based on 25.2x 2028F PE), reflecting the recent global defence sector de-rating and a higher risk-free rate environment.
Market Spotlight
- US stocks were mixed on Friday. Dow Jones rose while S&P 500 and Nasdaq fell as the information technology, consumer discretionary and industrials sectors slid. There were more decliners than advancers on NASDAQ.
- The FSSTI fell 50.86 points to 5,231.84, supported by weakness in DBS, Singtel and ST Engineering. Both mid-and small-cap indices fell, with a broad market decline on a S$1.91b turnover.
What’s Inside
Company Results | Singapore Telecommunications (ST SP/BUY/S$4.11/Target: S$5.50)
- Singtel reported a higher 1HFY27 underlying net profit of S$1.49b (+10 yoy), within expectations and guiding towards a strong finish for the year. Key drivers include positive operating leverage from Optus, NCS and Digital InfraCo as well as higher associate earnings from Airtel and AIS. The group also declared a higher 1HFY27 interim dividend of 9.0 S cents/share. Maintain BUY with a target price of S$5.50.
Technical Analysis
Monthly Technical Regional Indices Watch – STI Outlook
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


