
Wealth Daily
US Equity Hits Fresh High on AI & Power Strength
Today’s Must-Know News
Overnight Markets
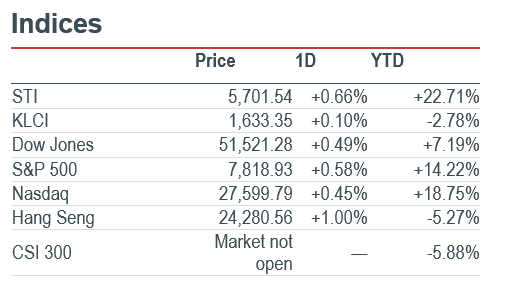
Market Movers: AMD (AMD US) rose 2.80% at the U.S. close on Tues, 6 October as CEO Lisa Su outlined a substantial 2027 chip-supply increase. The S&P 500 gained 0.58%. SpaceX (SPCX US) was reported after the close to be seeking US$40bn to buy Nvidia (NVDA US) chips: US$10bn of bank loans and US$30bn of investment-grade debt. Reuters, citing the Financial Times, said Apollo was expected to lead the financing; no completed transaction was announced. Constellation Energy (CEG US) jumped 12.25% after a power agreement with Alphabet (GOOGL US), covering 890MW of new nuclear capacity and 2,700MW of existing supply. Constellation plans over US$4.3bn of investment, with first upgrades expected in 2028. Funding and capacity delivery remain the key execution tests. (Reuters / Reuters / Google / Market data) Nvidia (NVDA US) is our Core Recommendation; Alphabet (GOOGL US) is our Trading Buy.
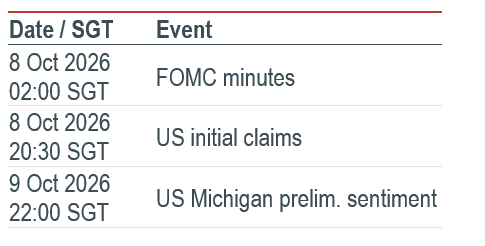
Macro: The U.S. trade deficit widened 13.7% to US$105.6bn in August. Imports rose 4.3% to US$420.8bn, outpacing exports’ 1.4% increase to US$315.2bn. Capital-equipment imports reflect part of the AI investment cycle. Strong domestic demand supports activity, while the import surge weighs on measured GDP. FOMC minutes on 8 October at 02:00 SGT will clarify the September policy debate. (Census / BEA / Reuters)
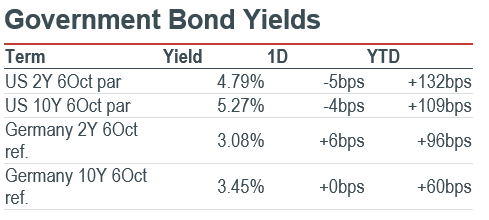
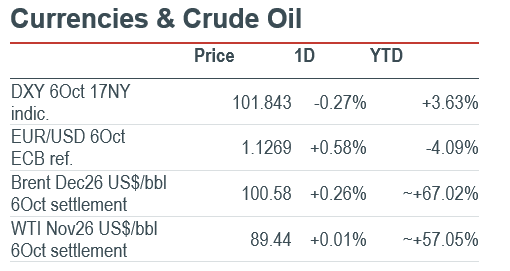
FICC: The U.S. 10-year par yield fell 4bps from 5.31% to 5.27% at Tuesday’s official reference. December Brent settled 0.26% higher at US$100.58/bbl; November WTI gained 0.01% to US$89.44/bbl. EIA raised its 4Q26 Brent spot forecast by US$14 to US$105/bbl, underscoring persistent fuel pressure. Lower yields ease discount-rate pressure, but diesel tightness remains a risk for energy-intensive businesses. Its forecast excludes the additional stock releases announced by the G7 on 2 October. (US Treasury / Reuters / EIA)
AI
AMD plans a larger chip-supply response. Advanced Micro Devices (AMD US) rose about 2.8% to US$649.42 at the 6 October US close. Chief Executive Lisa Su told reporters that chip supply would increase substantially in 2027, following increases this year. AMD plans capacity three to five years ahead and seeks advanced wafer capacity and closer memory partnerships. Demand visibility improves, although no production target was quantified. (Reuters / Market data)
SpaceX reportedly seeks financing for Nvidia chips. Reuters reported after the 6 October close, citing the Financial Times, that SpaceX (SPCX US) seeks US$40bn of Apollo Global Management (APO US)-led financing for Nvidia (NVDA US) chips. Plans envisage about US$10bn of bank loans and US$30bn of investment-grade debt, with closing expected in 2027. Company confirmation remains outstanding. The proposal highlights AI demand and reliance on credit markets. (Financial Times via Reuters) Nvidia (NVDA US) is our Core Recommendation.
Google contracts support new nuclear capacity investment. Constellation Energy (CEG US) gained about 12.2% to US$300.40 at the 6 October close after agreements with Google, part of Alphabet (GOOGL US). A 20-year contract supports 890MW of new nuclear capacity across 11 units and over US$4.3bn investment, with first additions expected in 2028. Separately, a 15-year agreement covers 2,700MW of existing supply. Construction execution remains critical. (Constellation Energy / Reuters / Market data) Alphabet (GOOGL US) is our Trading Buy.
Marvell raises its custom-chip revenue outlook. Marvell Technology (MRVL US) rose about 5.8% to US$287.01 at the 6 October US close following its investor day. Management raised fiscal 2028 revenue guidance to approximately US$20bn from US$18bn and fiscal 2029 custom-chip revenue to above US$12bn from above US$10bn. Its fiscal 2031 revenue target is US$70–90bn. The longer-term ambition depends on production ramps and sustained AI spending. (Reuters / Marvell investor-day transcript / Market data)
Americas
Amazon extends live-event reach with Emmy rights. Amazon (AMZN US) announced a six-year agreement with the Television Academy to stream the Emmy Awards on Prime Video from 2027. The ceremony will be free in more than 240 countries and territories, without a Prime subscription. The deal extends streaming's role in major live events and broadens Amazon's entertainment audience. Undisclosed rights economics leave the financial return uncertain. (Television Academy / AP) Amazon (AMZN US) is our Core Recommendation.
Option Care takeover expands home-infusion exposure. Option Care Health (OPCH US) gained about 32.6% to US$31.00 at the 6 October close after agreeing a US$32.05-per-share cash takeover. Enterprise value is approximately US$5.8bn. CD&R will own 51%, while McKesson (MCK US) invests approximately US$1.4bn for 49%. The home-infusion combination is expected to close in first-half 2027, subject to shareholder and regulatory approvals; that uncertainty leaves an offer-price discount. (Option Care Health / Reuters / Market data)
Emera merger expands capacity for utility investment. Emera (EMA CN) agreed on 6 October to acquire Canadian Utilities (CU CN) in an all-share transaction valued at C$14.3bn, approximately US$10.02bn. The combined enterprise value is approximately C$72bn. Its C$32bn capital plan through 2030 targets 7–8% annual rate-base growth. The enlarged utility gains financing capacity and diversification, but expected third- or fourth-quarter 2027 completion remains subject to shareholder, court and regulatory approvals. (Emera / Reuters)
Lamb Weston raises guidance despite margin pressure. Lamb Weston (LW US) rose about 7.5% to US$47.91 at the 6 October US close after fiscal first-quarter results. Sales rose 1% to US$1.67bn and adjusted EPS increased 1% to US$0.75, while adjusted EBITDA fell 5% to US$286mn. Fiscal 2027 adjusted EPS guidance increased to US$3.05–3.35 from US$2.95–3.25. North American volume growth supports recovery, but weaker international profitability remains a constraint. (Lamb Weston / AP / Market data)
FICO links workforce cuts to AI restructuring. Fair Isaac (FICO US) disclosed on 6 October plans to eliminate approximately 15% of positions as it simplifies operations and integrates AI into product development. Expected pretax charges total approximately US$27mn in fiscal fourth-quarter 2026, largely severance and substantially all future cash expenditure. Completion is targeted by fiscal third-quarter 2027. Recurring savings remain unquantified, limiting assessment of the efficiency payoff. (FICO SEC filing / Reuters)
Constellation Brands' earnings beat masks weaker volumes. Constellation Brands (STZ US) reported fiscal second-quarter comparable EPS of US$3.74, up 3%, on revenue of US$2.63bn, up 6%, after the 6 October US close. Both beat forecasts, but fiscal 2027 comparable EPS guidance remained US$11.20–11.90. Beer depletions fell 0.6% and operating margin declined 160bps to 39%. Consumer demand and margin recovery remain crucial to converting the beat into sustained growth. (Constellation Brands / Reuters)
Greater China
DeepSeek’s reported financing strengthens its competitive capacity. DeepSeek is nearing at least RMB80bn (about US$12bn) of funding, The Next Web reported on Tuesday, citing Bloomberg sources. Tencent (0700.HK) and CATL (300750.SZ) are reportedly major backers. The total could approach RMB100bn versus an initial RMB50bn target, but completion remains unannounced. Additional capital could intensify competition for computing resources and model talent; returns for the listed investors remain uncertain. (The Next Web) Tencent (0700.HK) is our Core Recommendation. CATL (300750.SZ) is our Core Recommendation.
New World seeks a longer debt maturity profile. New World Development (0017.HK) launched an offer on Tuesday to exchange existing debt for up to US$600mn of secured 7.375% notes due 2032. The three existing note series have about US$991mn outstanding and mature in 2027–28. Shares fell about 3.5% to HK$5.50 at Tuesday’s Hong Kong close. Bondholder participation levels and exchange terms will determine the liquidity relief. (Reuters / Market data)
Ant and HSBC expand tokenised treasury pilots. Ant International and HSBC (0005.HK) announced completed pilot transactions on Tuesday across two UAE corridors: domestic dirham transfers and cross-border US dollar payments. Ant’s treasury platform connects more than 20 banks across over 17 currencies; the corridors include Hong Kong and Singapore links. Faster liquidity movement could strengthen transaction-banking relationships, but undisclosed volumes and fees leave any earnings benefit unquantified. (Ant International) HSBC (0005.HK) is our Core Recommendation.
Asia ex. China
Trent’s operating update prompts a sharp re-rating. Trent (TRENT IN) gained about 12.6% in Tuesday’s session, according to Reuters’ closing report, following Monday’s after-market business update. September-quarter merchandise revenue rose 23% YoY. Net openings of 10 Westside and 17 Zudio stores lifted its network to 1,342. The response signals renewed confidence in expansion, but store productivity and margins remain untested by this revenue-only operating update. (Trent / Reuters)
Korean bank breaches sharpen AI security concerns. South Korean President Lee Jae Myung said on Tuesday that AI appeared to have been used in recent bank hacks; regulators shared 28 IP addresses linked to the attacks. The comments update breaches first reported last week. Banks face potential remediation spending and customer-confidence pressure, although authorities had not established the tools used or the full damage. Financial effects remain unquantified. (Reuters)
Fuji Media’s sale process tests property valuations. Fuji Media Holdings (4676 JP) expects a potential sale of Sankei Building to value the property unit at around ¥1tn (US$6.3bn), including debt, Reuters reported on Tuesday. Private-equity groups are preparing final bids, but the structure and outcome remain undecided. A disposal could release capital and simplify the group; the quoted enterprise value should not be treated as distributable equity proceeds. (Reuters)
GIC and Bain explore Japanese software exit. Singapore’s GIC and Bain Capital are exploring an IPO or sale of WHI Holdings at a valuation of at least ¥500bn (US$3.2bn), Reuters reported on Tuesday. Its main operating business serves about 1,200 large corporate groups. Discussions remain preliminary and the owners may retain the asset. The process would test demand for established Japanese enterprise software and potential sponsor liquidity. (Reuters / GIC)
Aspial completes longer-dated Singapore dollar funding issue. Aspial Lifestyle (5UF SP) announced on Tuesday evening that it had issued S$75mn of 5.00% notes due 2031. An earlier announcement proposed repurchases of up to S$10mn of its 6.25% 2027 notes and S$15mn of its 5.10% 2029 notes. The completed issue provides term funding, but net debt reduction depends on accepted tenders and use of proceeds; new issuance alone does not establish deleveraging. (Aspial Lifestyle / Aspial Lifestyle)
EMEA and Others
Nokia rallies alongside a fresh network contract. Nokia ADR (NOK US) rose about 7.5% to US$10.97 at Tues’s US close. Separately, Brazil’s RNP selected Nokia and Q13 to modernise its research network. The deployment covers 4.8Tbps and over 350 routers, connecting more than 4mn users. This illustrates infrastructure demand, but the undisclosed contract value prevents earnings quantification. The announcement alone does not explain the full share-price gain. (Nokia / Reuters / Market data) Nokia ADR (NOK US) is our Trading Buy.
Genmab trial data strengthen frontline lymphoma opportunity. Genmab (GMAB DC) rose about 4.4% to DKK2,482 at Tuesday’s Copenhagen close, the first local session after Monday’s US-time clinical announcement. Epcoritamab plus R-CHOP reduced disease-progression or death risk by 51% versus R-CHOP in a phase 3 frontline lymphoma trial. The combination remains investigational; regulatory review and treatment adoption will determine whether the promising clinical result translates into a commercial benefit. (Genmab / Reuters / Market data)
BPCE’s Sabadell stake opens a banking partnership. BPCE announced a friendly 7% holding in Banco Sabadell (SAB SM) on Tuesday, saying it did not intend to exceed 9.9% and would seek a board seat. The groups will explore cooperation in corporate and investment banking, leasing and consumer finance. The minority investment offers cross-border distribution opportunities, but earnings synergies remain unquantified and depend on subsequent operating agreements and execution. (BPCE / Reuters)
Neinor’s capital recycling improves its medium-term outlook. Neinor Homes (HOME SM) rose about 5.1% to €17.41 at Tuesday’s Spanish close as investors assessed its Monday-dated transaction and guidance update. The €110mn land portfolio sale supported raising 2027 EBITDA guidance to €260–280mn from €240–260mn; 2026 guidance was reiterated. Faster capital recycling improves cash availability and the distribution outlook, but asset disposals and development execution remain necessary to deliver targets. (Neinor Homes / Reuters / Market data)
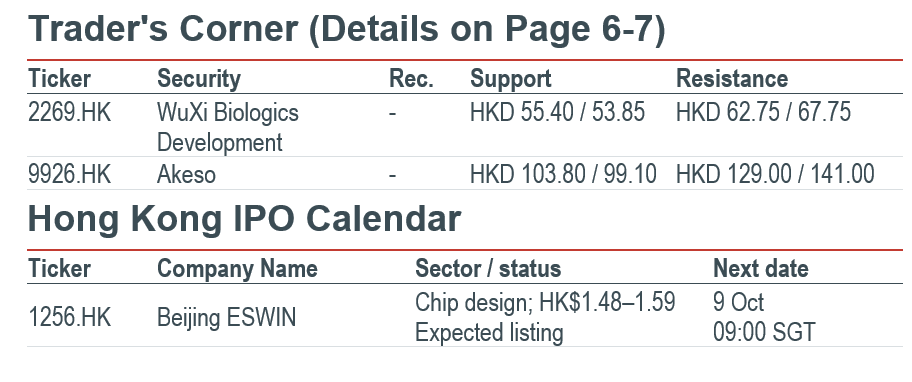
Traders’ corner
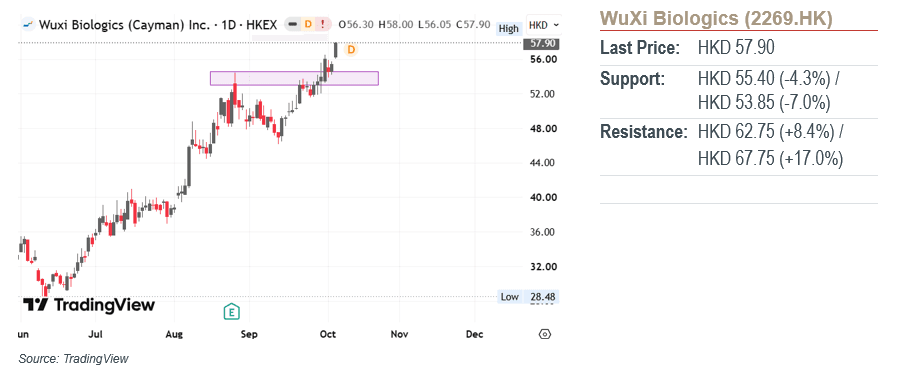
Our Technical View
Price executed a successful retest and structural defense along its resistance-turned-support zone.
The RSI remains firmly established in strong, bullish territory and continues to slope upward, confirming sustained trend velocity.
As long as price strictly defends this converted demand anchor, we see continued upward expansion toward higher supply targets.
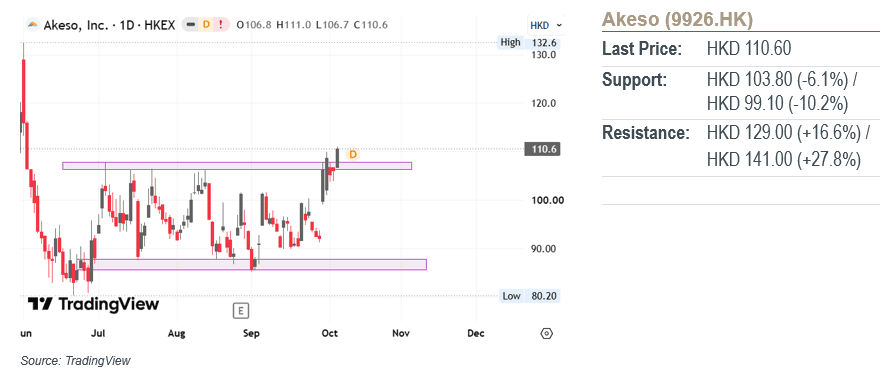
Our Technical View
Price broke out from its sideways consolidation range, subsequently completing a successful retest and structural defense along the breakout pivot.
The RSI remains firmly established in bullish territory and continues to slope upward, confirming sustained trend velocity.
As long as price strictly defends this converted demand anchor, we could expect continued upward expansion toward higher supply targets.
Market Movers: AMD (AMD US) rose 2.80% at the U.S. close on Tues, 6 October as CEO Lisa Su outlined a substantial 2027 chip-supply increase. The S&P 500 gained 0.58%. SpaceX (SPCX US) was reported after the close to be seeking US$40bn to buy Nvidia (NVDA US) chips: US$10bn of bank loans and US$30bn of investment-grade debt. Reuters, citing the Financial Times, said Apollo was expected to lead the financing; no completed transaction was announced. Constellation Energy (CEG US) jumped 12.25% after a power agreement with Alphabet (GOOGL US), covering 890MW of new nuclear capacity and 2,700MW of existing supply. Constellation plans over US$4.3bn of investment, with first upgrades expected in 2028. Funding and capacity delivery remain the key execution tests. (Reuters / Reuters / Google / Market data) Nvidia (NVDA US) is our Core Recommendation; Alphabet (GOOGL US) is our Trading Buy.
Macro: The U.S. trade deficit widened 13.7% to US$105.6bn in August. Imports rose 4.3% to US$420.8bn, outpacing exports’ 1.4% increase to US$315.2bn. Capital-equipment imports reflect part of the AI investment cycle. Strong domestic demand supports activity, while the import surge weighs on measured GDP. FOMC minutes on 8 October at 02:00 SGT will clarify the September policy debate. (Census / BEA / Reuters)
FICC: The U.S. 10-year par yield fell 4bps from 5.31% to 5.27% at Tuesday’s official reference. December Brent settled 0.26% higher at US$100.58/bbl; November WTI gained 0.01% to US$89.44/bbl. EIA raised its 4Q26 Brent spot forecast by US$14 to US$105/bbl, underscoring persistent fuel pressure. Lower yields ease discount-rate pressure, but diesel tightness remains a risk for energy-intensive businesses. Its forecast excludes the additional stock releases announced by the G7 on 2 October. (US Treasury / Reuters / EIA)
AI
AMD plans a larger chip-supply response. Advanced Micro Devices (AMD US) rose about 2.8% to US$649.42 at the 6 October US close. Chief Executive Lisa Su told reporters that chip supply would increase substantially in 2027, following increases this year. AMD plans capacity three to five years ahead and seeks advanced wafer capacity and closer memory partnerships. Demand visibility improves, although no production target was quantified. (Reuters / Market data)
SpaceX reportedly seeks financing for Nvidia chips. Reuters reported after the 6 October close, citing the Financial Times, that SpaceX (SPCX US) seeks US$40bn of Apollo Global Management (APO US)-led financing for Nvidia (NVDA US) chips. Plans envisage about US$10bn of bank loans and US$30bn of investment-grade debt, with closing expected in 2027. Company confirmation remains outstanding. The proposal highlights AI demand and reliance on credit markets. (Financial Times via Reuters) Nvidia (NVDA US) is our Core Recommendation.
Google contracts support new nuclear capacity investment. Constellation Energy (CEG US) gained about 12.2% to US$300.40 at the 6 October close after agreements with Google, part of Alphabet (GOOGL US). A 20-year contract supports 890MW of new nuclear capacity across 11 units and over US$4.3bn investment, with first additions expected in 2028. Separately, a 15-year agreement covers 2,700MW of existing supply. Construction execution remains critical. (Constellation Energy / Reuters / Market data) Alphabet (GOOGL US) is our Trading Buy.
Marvell raises its custom-chip revenue outlook. Marvell Technology (MRVL US) rose about 5.8% to US$287.01 at the 6 October US close following its investor day. Management raised fiscal 2028 revenue guidance to approximately US$20bn from US$18bn and fiscal 2029 custom-chip revenue to above US$12bn from above US$10bn. Its fiscal 2031 revenue target is US$70–90bn. The longer-term ambition depends on production ramps and sustained AI spending. (Reuters / Marvell investor-day transcript / Market data)
Americas
Amazon extends live-event reach with Emmy rights. Amazon (AMZN US) announced a six-year agreement with the Television Academy to stream the Emmy Awards on Prime Video from 2027. The ceremony will be free in more than 240 countries and territories, without a Prime subscription. The deal extends streaming's role in major live events and broadens Amazon's entertainment audience. Undisclosed rights economics leave the financial return uncertain. (Television Academy / AP) Amazon (AMZN US) is our Core Recommendation.
Option Care takeover expands home-infusion exposure. Option Care Health (OPCH US) gained about 32.6% to US$31.00 at the 6 October close after agreeing a US$32.05-per-share cash takeover. Enterprise value is approximately US$5.8bn. CD&R will own 51%, while McKesson (MCK US) invests approximately US$1.4bn for 49%. The home-infusion combination is expected to close in first-half 2027, subject to shareholder and regulatory approvals; that uncertainty leaves an offer-price discount. (Option Care Health / Reuters / Market data)
Emera merger expands capacity for utility investment. Emera (EMA CN) agreed on 6 October to acquire Canadian Utilities (CU CN) in an all-share transaction valued at C$14.3bn, approximately US$10.02bn. The combined enterprise value is approximately C$72bn. Its C$32bn capital plan through 2030 targets 7–8% annual rate-base growth. The enlarged utility gains financing capacity and diversification, but expected third- or fourth-quarter 2027 completion remains subject to shareholder, court and regulatory approvals. (Emera / Reuters)
Lamb Weston raises guidance despite margin pressure. Lamb Weston (LW US) rose about 7.5% to US$47.91 at the 6 October US close after fiscal first-quarter results. Sales rose 1% to US$1.67bn and adjusted EPS increased 1% to US$0.75, while adjusted EBITDA fell 5% to US$286mn. Fiscal 2027 adjusted EPS guidance increased to US$3.05–3.35 from US$2.95–3.25. North American volume growth supports recovery, but weaker international profitability remains a constraint. (Lamb Weston / AP / Market data)
FICO links workforce cuts to AI restructuring. Fair Isaac (FICO US) disclosed on 6 October plans to eliminate approximately 15% of positions as it simplifies operations and integrates AI into product development. Expected pretax charges total approximately US$27mn in fiscal fourth-quarter 2026, largely severance and substantially all future cash expenditure. Completion is targeted by fiscal third-quarter 2027. Recurring savings remain unquantified, limiting assessment of the efficiency payoff. (FICO SEC filing / Reuters)
Constellation Brands' earnings beat masks weaker volumes. Constellation Brands (STZ US) reported fiscal second-quarter comparable EPS of US$3.74, up 3%, on revenue of US$2.63bn, up 6%, after the 6 October US close. Both beat forecasts, but fiscal 2027 comparable EPS guidance remained US$11.20–11.90. Beer depletions fell 0.6% and operating margin declined 160bps to 39%. Consumer demand and margin recovery remain crucial to converting the beat into sustained growth. (Constellation Brands / Reuters)
Greater China
DeepSeek’s reported financing strengthens its competitive capacity. DeepSeek is nearing at least RMB80bn (about US$12bn) of funding, The Next Web reported on Tuesday, citing Bloomberg sources. Tencent (0700.HK) and CATL (300750.SZ) are reportedly major backers. The total could approach RMB100bn versus an initial RMB50bn target, but completion remains unannounced. Additional capital could intensify competition for computing resources and model talent; returns for the listed investors remain uncertain. (The Next Web) Tencent (0700.HK) is our Core Recommendation. CATL (300750.SZ) is our Core Recommendation.
New World seeks a longer debt maturity profile. New World Development (0017.HK) launched an offer on Tuesday to exchange existing debt for up to US$600mn of secured 7.375% notes due 2032. The three existing note series have about US$991mn outstanding and mature in 2027–28. Shares fell about 3.5% to HK$5.50 at Tuesday’s Hong Kong close. Bondholder participation levels and exchange terms will determine the liquidity relief. (Reuters / Market data)
Ant and HSBC expand tokenised treasury pilots. Ant International and HSBC (0005.HK) announced completed pilot transactions on Tuesday across two UAE corridors: domestic dirham transfers and cross-border US dollar payments. Ant’s treasury platform connects more than 20 banks across over 17 currencies; the corridors include Hong Kong and Singapore links. Faster liquidity movement could strengthen transaction-banking relationships, but undisclosed volumes and fees leave any earnings benefit unquantified. (Ant International) HSBC (0005.HK) is our Core Recommendation.
Asia ex. China
Trent’s operating update prompts a sharp re-rating. Trent (TRENT IN) gained about 12.6% in Tuesday’s session, according to Reuters’ closing report, following Monday’s after-market business update. September-quarter merchandise revenue rose 23% YoY. Net openings of 10 Westside and 17 Zudio stores lifted its network to 1,342. The response signals renewed confidence in expansion, but store productivity and margins remain untested by this revenue-only operating update. (Trent / Reuters)
Korean bank breaches sharpen AI security concerns. South Korean President Lee Jae Myung said on Tuesday that AI appeared to have been used in recent bank hacks; regulators shared 28 IP addresses linked to the attacks. The comments update breaches first reported last week. Banks face potential remediation spending and customer-confidence pressure, although authorities had not established the tools used or the full damage. Financial effects remain unquantified. (Reuters)
Fuji Media’s sale process tests property valuations. Fuji Media Holdings (4676 JP) expects a potential sale of Sankei Building to value the property unit at around ¥1tn (US$6.3bn), including debt, Reuters reported on Tuesday. Private-equity groups are preparing final bids, but the structure and outcome remain undecided. A disposal could release capital and simplify the group; the quoted enterprise value should not be treated as distributable equity proceeds. (Reuters)
GIC and Bain explore Japanese software exit. Singapore’s GIC and Bain Capital are exploring an IPO or sale of WHI Holdings at a valuation of at least ¥500bn (US$3.2bn), Reuters reported on Tuesday. Its main operating business serves about 1,200 large corporate groups. Discussions remain preliminary and the owners may retain the asset. The process would test demand for established Japanese enterprise software and potential sponsor liquidity. (Reuters / GIC)
Aspial completes longer-dated Singapore dollar funding issue. Aspial Lifestyle (5UF SP) announced on Tuesday evening that it had issued S$75mn of 5.00% notes due 2031. An earlier announcement proposed repurchases of up to S$10mn of its 6.25% 2027 notes and S$15mn of its 5.10% 2029 notes. The completed issue provides term funding, but net debt reduction depends on accepted tenders and use of proceeds; new issuance alone does not establish deleveraging. (Aspial Lifestyle / Aspial Lifestyle)
EMEA and Others
Nokia rallies alongside a fresh network contract. Nokia ADR (NOK US) rose about 7.5% to US$10.97 at Tues’s US close. Separately, Brazil’s RNP selected Nokia and Q13 to modernise its research network. The deployment covers 4.8Tbps and over 350 routers, connecting more than 4mn users. This illustrates infrastructure demand, but the undisclosed contract value prevents earnings quantification. The announcement alone does not explain the full share-price gain. (Nokia / Reuters / Market data) Nokia ADR (NOK US) is our Trading Buy.
Genmab trial data strengthen frontline lymphoma opportunity. Genmab (GMAB DC) rose about 4.4% to DKK2,482 at Tuesday’s Copenhagen close, the first local session after Monday’s US-time clinical announcement. Epcoritamab plus R-CHOP reduced disease-progression or death risk by 51% versus R-CHOP in a phase 3 frontline lymphoma trial. The combination remains investigational; regulatory review and treatment adoption will determine whether the promising clinical result translates into a commercial benefit. (Genmab / Reuters / Market data)
BPCE’s Sabadell stake opens a banking partnership. BPCE announced a friendly 7% holding in Banco Sabadell (SAB SM) on Tuesday, saying it did not intend to exceed 9.9% and would seek a board seat. The groups will explore cooperation in corporate and investment banking, leasing and consumer finance. The minority investment offers cross-border distribution opportunities, but earnings synergies remain unquantified and depend on subsequent operating agreements and execution. (BPCE / Reuters)
Neinor’s capital recycling improves its medium-term outlook. Neinor Homes (HOME SM) rose about 5.1% to €17.41 at Tuesday’s Spanish close as investors assessed its Monday-dated transaction and guidance update. The €110mn land portfolio sale supported raising 2027 EBITDA guidance to €260–280mn from €240–260mn; 2026 guidance was reiterated. Faster capital recycling improves cash availability and the distribution outlook, but asset disposals and development execution remain necessary to deliver targets. (Neinor Homes / Reuters / Market data)
Traders’ corner
Our Technical View
Price executed a successful retest and structural defense along its resistance-turned-support zone.
The RSI remains firmly established in strong, bullish territory and continues to slope upward, confirming sustained trend velocity.
As long as price strictly defends this converted demand anchor, we see continued upward expansion toward higher supply targets.
Our Technical View
Price broke out from its sideways consolidation range, subsequently completing a successful retest and structural defense along the breakout pivot.
The RSI remains firmly established in bullish territory and continues to slope upward, confirming sustained trend velocity.
As long as price strictly defends this converted demand anchor, we could expect continued upward expansion toward higher supply targets.
Disclosures and disclaimers
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


