

Company Coverage
Astra Otoparts (AUTO IJ): Organic Growth And Potential M&A to Drive Expansion
NOT RATED
Current price:
Target price:
Upside:
Rp3,340
n.a.
n.a.
Analyst
Analyst
Highlights
- Store network target remains on track. AUTO had 666 stores as of Jun 26 and targets to have 680-690 by end-26.
- M&A to complement organic growth. AUTO is pursuing the acquisition of a majority stake in a company operating across manufacturing and trading.
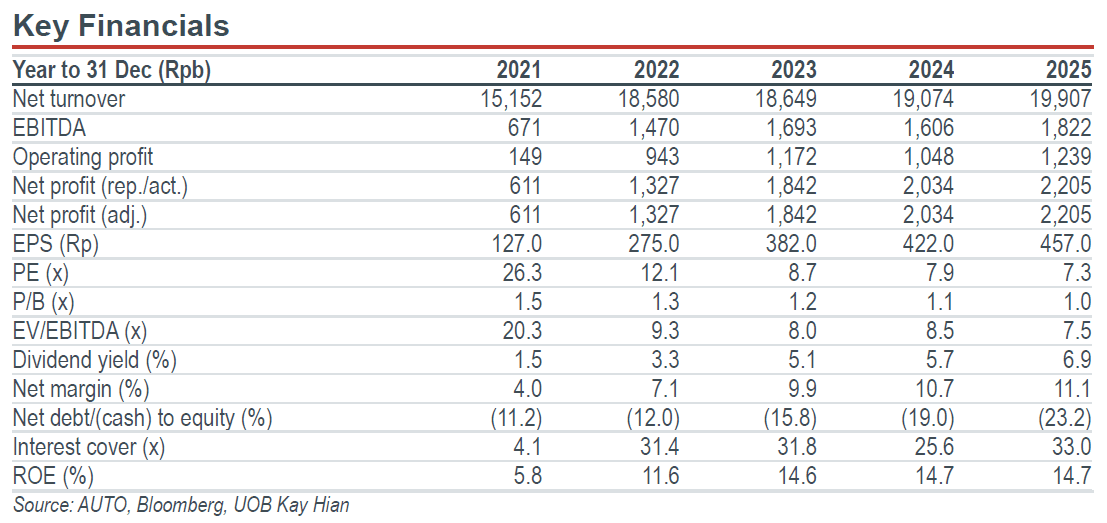
- There should be continued dividend growth, with interim 2026 DPS of Rp72.52 (+22.9% yoy), and payout upside on hold until the planned M&A is completed.
Analysis
- Replacement market offers a larger and more recurring growth opportunity. Indonesia’s car population reached around 21m units in 2025, more than 25x annual new-car sales of around 800,000 units. Replacement demand is driven by the existing car parc and its maintenance needs, which makes it more recurring and more resilient through the cycle. As vehicles age and move out of warranty, owners increasingly shift to independent workshops and aftermarket parts, which widens the addressable market for Astra Otoparts’ (AUTO) trading segment. While Auto2000 accounted for 41% of Toyota sales in 2025 (over 106,000 units) and services these vehicles under warranty, AUTO aims to capture them through Astra Otoservice once warranties expire. This lets the Astra group capture the full vehicle life cycle: from new-car sales and financing, to OEM components at production, to parts and servicing through the Shop & Drive and Astra Otoservice network.
- Store network target remains on track. AUTO operated 666 stores as of Jun 26, including 420 Shop & Drive and 45 Astra Otoservice outlets, and targets to have a total of 680-690 stores by end-26. AUTO adds 30-40 stores annually, with leased sites requiring two months of renovation, while greenfield Astra Otoservice outlets take 3-6 months to develop. Astra Otoservice offers periodic servicing at prices 30-50% below those of authorised workshops, targeting vehicles whose warranties have expired. AUTO plans to convert suitable Shop & Drive locations into larger outlets offering similar services. As the Astra Otoservice brand cannot be franchised, these larger outlets will retain the Shop & Drive name to preserve franchising opportunities. Store expansion is important for margin improvement, as B2C operations generate gross margins of above 30%, compared with the trading segment average of 24%. AUTO expects a growing retail contribution to gradually lift the trading gross margin towards 25-26%.
- Organic growth complemented by M&A. AUTO is targeting a sizeable M&A transaction, potentially involving a majority stake and funded through a combination of cash and bank loans. The target operates across manufacturing and trading and is expected to create synergies through products and distribution channels.
Highlights
- Store network target remains on track. AUTO had 666 stores as of Jun 26 and targets to have 680-690 by end-26.
- M&A to complement organic growth. AUTO is pursuing the acquisition of a majority stake in a company operating across manufacturing and trading.
- There should be continued dividend growth, with interim 2026 DPS of Rp72.52 (+22.9% yoy), and payout upside on hold until the planned M&A is completed.
Analysis
- Replacement market offers a larger and more recurring growth opportunity. Indonesia’s car population reached around 21m units in 2025, more than 25x annual new-car sales of around 800,000 units. Replacement demand is driven by the existing car parc and its maintenance needs, which makes it more recurring and more resilient through the cycle. As vehicles age and move out of warranty, owners increasingly shift to independent workshops and aftermarket parts, which widens the addressable market for Astra Otoparts’ (AUTO) trading segment. While Auto2000 accounted for 41% of Toyota sales in 2025 (over 106,000 units) and services these vehicles under warranty, AUTO aims to capture them through Astra Otoservice once warranties expire. This lets the Astra group capture the full vehicle life cycle: from new-car sales and financing, to OEM components at production, to parts and servicing through the Shop & Drive and Astra Otoservice network.
- Store network target remains on track. AUTO operated 666 stores as of Jun 26, including 420 Shop & Drive and 45 Astra Otoservice outlets, and targets to have a total of 680-690 stores by end-26. AUTO adds 30-40 stores annually, with leased sites requiring two months of renovation, while greenfield Astra Otoservice outlets take 3-6 months to develop. Astra Otoservice offers periodic servicing at prices 30-50% below those of authorised workshops, targeting vehicles whose warranties have expired. AUTO plans to convert suitable Shop & Drive locations into larger outlets offering similar services. As the Astra Otoservice brand cannot be franchised, these larger outlets will retain the Shop & Drive name to preserve franchising opportunities. Store expansion is important for margin improvement, as B2C operations generate gross margins of above 30%, compared with the trading segment average of 24%. AUTO expects a growing retail contribution to gradually lift the trading gross margin towards 25-26%.
- Organic growth complemented by M&A. AUTO is targeting a sizeable M&A transaction, potentially involving a majority stake and funded through a combination of cash and bank loans. The target operates across manufacturing and trading and is expected to create synergies through products and distribution channels.
NOT RATED
Current price:
Target price:
Upside:
Rp3,340
n.a.
n.a.
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


