Company Coverage
CSE Global (CSE SP): Positive Highlights From Meeting Reinforce Growth Outlook
BUY (Maintained)
Current price:
Target price:
Upside:
S$0.96
S$1.79
86.5%
Analyst
Analyst
Highlights
- Key takeaways from our recent meeting with management suggest that CSE’s outlook remains positive, with more DC contract wins expected by end-26 as well as strong potential for more contracts from the second hyperscaler.
- We still expect stronger 2H26 margins as start-up costs normalise and operating efficiency improves. Credit risk is low given CSE’s exposure to established hyperscalers and US government end-users.
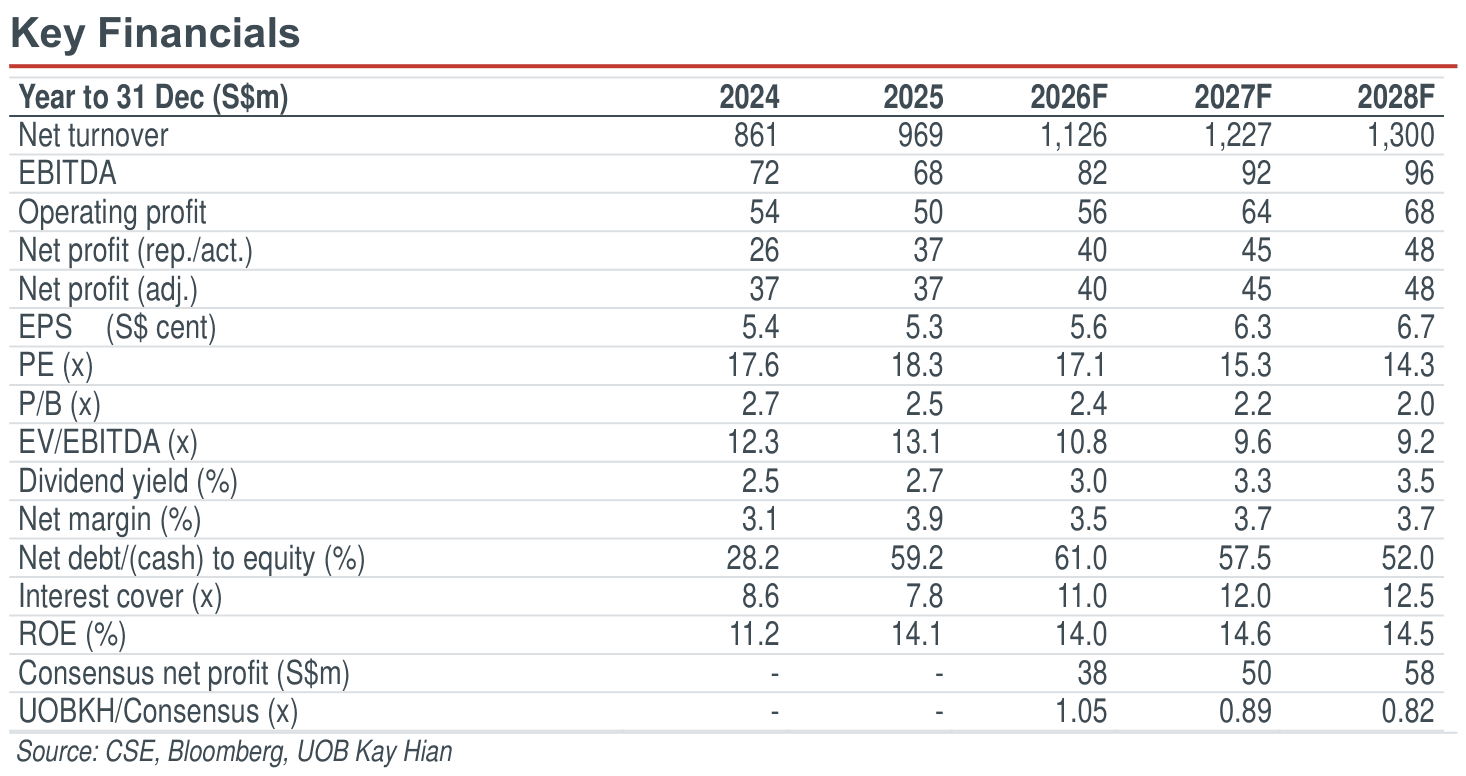
- Maintain BUY with a target price of S$1.79. CSE currently trades at 15x 2027F PE, around its long-term mean despite having commendable growth.
Analysis
- Key highlights from management meeting. CSE Global (CSE) highlighted that existing data centre (DC) contracts remain intact, with continued opportunities for new project wins. Management remains optimistic about continued order momentum, with further contract wins expected in 4Q26 as major customers finalise their projects for the following year. CSE's DC exposure to US government end-users provides some insulation against funding risks, given their relatively low credit risk and long-term project commitments. CSE has also commenced work with a second hyperscaler, presenting further growth opportunities as it expands its presence in the US DC market.
- S$254.8m in new US electrification contract wins. CSE has secured three major US electrification contracts worth a combined S$254.8m in Aug and Sep 26, comprising: a) a S$64.3m contract accounted in Aug 26 for the design and manufacture of power distribution centres (PDC), together with the integration of electrical and control systems, for the Cheyenne Power Hub project in the US, and b) two additional contracts worth S$190.5m in Sep 26 for works on the Calcasieu Pass 2 (CP2) LNG project in Louisiana and a follow-on order for the Cheyenne Power Hub project. These contracts will be executed progressively between 2026 and 2028.
- Strong contract wins support orderbook and revenue visibility. The S$254.8m in new contract wins is equivalent to approximately 41% of CSE's S$620m orderbook as at end-1H26, reflecting sustained order momentum and strong demand for its electrification solutions. Management expects further order wins in 4Q26, as major US customers typically finalise their project requirements for the following year during this period. With project deliveries extending into 2028, we expect these new contracts to provide greater medium-term revenue visibility and support CSE's growth prospects.
Highlights
- Key takeaways from our recent meeting with management suggest that CSE’s outlook remains positive, with more DC contract wins expected by end-26 as well as strong potential for more contracts from the second hyperscaler.
- We still expect stronger 2H26 margins as start-up costs normalise and operating efficiency improves. Credit risk is low given CSE’s exposure to established hyperscalers and US government end-users.
- Maintain BUY with a target price of S$1.79. CSE currently trades at 15x 2027F PE, around its long-term mean despite having commendable growth.
Analysis
- Key highlights from management meeting. CSE Global (CSE) highlighted that existing data centre (DC) contracts remain intact, with continued opportunities for new project wins. Management remains optimistic about continued order momentum, with further contract wins expected in 4Q26 as major customers finalise their projects for the following year. CSE's DC exposure to US government end-users provides some insulation against funding risks, given their relatively low credit risk and long-term project commitments. CSE has also commenced work with a second hyperscaler, presenting further growth opportunities as it expands its presence in the US DC market.
- S$254.8m in new US electrification contract wins. CSE has secured three major US electrification contracts worth a combined S$254.8m in Aug and Sep 26, comprising: a) a S$64.3m contract accounted in Aug 26 for the design and manufacture of power distribution centres (PDC), together with the integration of electrical and control systems, for the Cheyenne Power Hub project in the US, and b) two additional contracts worth S$190.5m in Sep 26 for works on the Calcasieu Pass 2 (CP2) LNG project in Louisiana and a follow-on order for the Cheyenne Power Hub project. These contracts will be executed progressively between 2026 and 2028.
- Strong contract wins support orderbook and revenue visibility. The S$254.8m in new contract wins is equivalent to approximately 41% of CSE's S$620m orderbook as at end-1H26, reflecting sustained order momentum and strong demand for its electrification solutions. Management expects further order wins in 4Q26, as major US customers typically finalise their project requirements for the following year during this period. With project deliveries extending into 2028, we expect these new contracts to provide greater medium-term revenue visibility and support CSE's growth prospects.
BUY (Maintained)
Current price:
Target price:
Upside:
S$0.96
S$1.79
86.5%
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

26 Aug 2026
Huationg Global (HUAGL SP): 1H26: Margin Pressure Expected To Ease; Recovery Ahead

28 Sept 2026
Reclaims Global (RGL SP) : 1HFY27: Healthy Results; Margins Remain Resilient

24 Sept 2026
Yangzijiang Shipbuilding (YZJSGD SP): Expect Strong 2H26 Order Win Momentum Underpinned By Active Enquiry Pipeline; Earnings Visibility Extending Into 2030
Our latest research

14 Oct 2026
NTT DC REIT (NTTDCR SP): Embracing Closer Alignment With Unitholders’ Interest

13 Oct 2026
Frasers Centrepoint Trust (FCT SP): Benefitting From Population And Job Growth In North Region

12 Oct 2026