Company Coverage
Keppel DC REIT (KDCREIT SP): 3Q26: Completes Acquisition Ahead Of AI Funding Squeeze
BUY (Maintained)
Current price:
Target price:
Upside:
S$2.13
S$2.83
40.4%
Analyst
Highlights
- KDCREIT achieved rental reversion of 16% in 3Q26, driven by lease renewal in Singapore and Australia. NPI grew 13% yoy in 9M26 due to positive reversions, rental escalations and acquisition of Tokyo DC 3.
- KDCREIT continues to build scale in hyperscale DCs. Potential acquisitions from sponsor pipeline, such as SGP9 in Singapore and a DC in Western Tokyo, are likely to materialise in 2028.
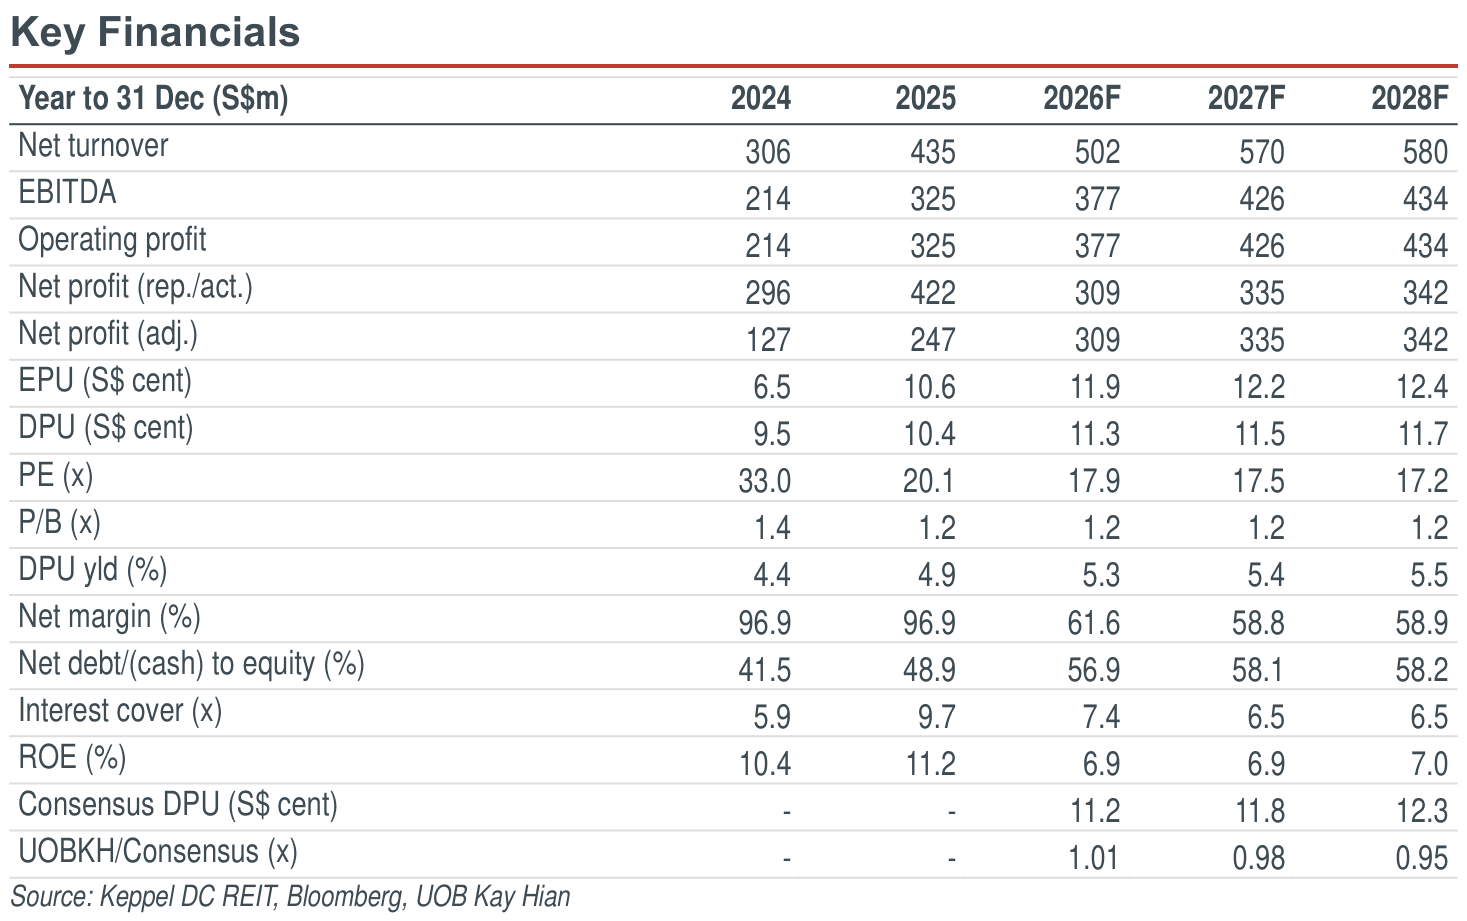
- KDCREIT has a resilient Singapore-centric portfolio and is well supported by sponsor Keppel. Maintain BUY. Target price: S$2.83.
Analysis
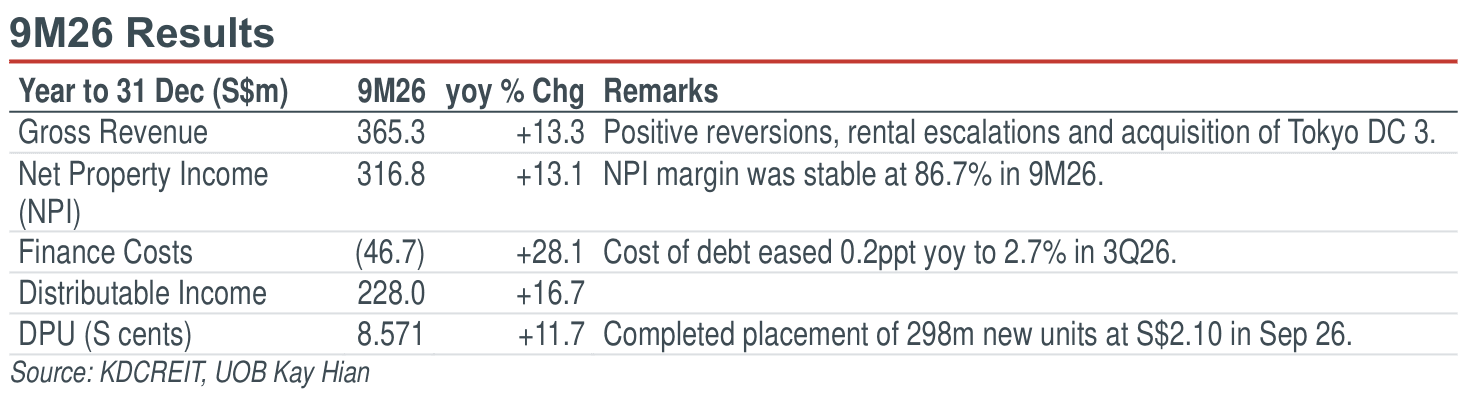
- Keppel DC REIT (KDCREIT) reported DPU of 8.571 S cents for 9M26 (+11.7% yoy), which is in line and accounted for 76% of our full-year forecast.
- Boost from Tokyo DC 3. Gross revenue and NPI grew 13.3% and 13.1% yoy respectively in 9M26, driven by positive reversions, rental escalations and acquisition of Tokyo DC 3 (completion: 19 Nov 25). NPI margin was stable at 86.7%. Higher effective interests in SGP 3 & 4 supported distributable income. Finance costs rose 28.1% yoy, reflecting additional borrowings to fund acquisitions and extension of land lease for SGP 7 & 8.
- Stronger rental reversion and occupancy. KDCREIT achieved rental reversion of 14% in 9M26 (1H26: 10%, 3Q26: 16%), based on renewed contracts that had commenced. New and renewal contracts were secured in Singapore and Australia. Contracted revenue-generating power capacity increased 1ppt qoq to 96%. WALE by lettable area was stable at 6.5 years.
Highlights
- KDCREIT achieved rental reversion of 16% in 3Q26, driven by lease renewal in Singapore and Australia. NPI grew 13% yoy in 9M26 due to positive reversions, rental escalations and acquisition of Tokyo DC 3.
- KDCREIT continues to build scale in hyperscale DCs. Potential acquisitions from sponsor pipeline, such as SGP9 in Singapore and a DC in Western Tokyo, are likely to materialise in 2028.
- KDCREIT has a resilient Singapore-centric portfolio and is well supported by sponsor Keppel. Maintain BUY. Target price: S$2.83.
Analysis
- Keppel DC REIT (KDCREIT) reported DPU of 8.571 S cents for 9M26 (+11.7% yoy), which is in line and accounted for 76% of our full-year forecast.
- Boost from Tokyo DC 3. Gross revenue and NPI grew 13.3% and 13.1% yoy respectively in 9M26, driven by positive reversions, rental escalations and acquisition of Tokyo DC 3 (completion: 19 Nov 25). NPI margin was stable at 86.7%. Higher effective interests in SGP 3 & 4 supported distributable income. Finance costs rose 28.1% yoy, reflecting additional borrowings to fund acquisitions and extension of land lease for SGP 7 & 8.
- Stronger rental reversion and occupancy. KDCREIT achieved rental reversion of 14% in 9M26 (1H26: 10%, 3Q26: 16%), based on renewed contracts that had commenced. New and renewal contracts were secured in Singapore and Australia. Contracted revenue-generating power capacity increased 1ppt qoq to 96%. WALE by lettable area was stable at 6.5 years.
BUY (Maintained)
Current price:
Target price:
Upside:
S$2.13
S$2.83
40.4%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

23 Oct 2026
Frasers Centrepoint Trust (FCT SP): 2HFY26: Positive Reversion And AEIs Underpin Sustainable Growth

26 Oct 2026
Suntec REIT (SUN SP): 3Q26: Expression Of Interest Exercise To Divest Australia Assets

29 Sept 2026
City Developments (CIT SP): Sharpening And Refreshing Its Growth Strategy
Our latest research
26 Oct 2026
Suntec REIT (SUN SP): 3Q26: Expression Of Interest Exercise To Divest Australia Assets
23 Oct 2026
Frasers Centrepoint Trust (FCT SP): 2HFY26: Positive Reversion And AEIs Underpin Sustainable Growth

22 Oct 2026