
Company Coverage
Food Empire Holdings (FEH SP): 3Q26: Healthy Growth; Expect Better Margins And Earnings hoh For 2H26
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$1.79
S$3.00
67.6%
S$3.49
Analyst
Analyst
Highlights
- FEH’s 9M26 revenue reached a record US$477m (+12% yoy), while 3Q26 revenue rose 6% yoy to US$161m. 9M26 revenue formed 79% of our full-year forecast, ahead of expectations.
- We expect 2H26 net margin and earnings to be better hoh. While 3Q26 revenue growth moderated to 6%, FEH is deliberately prioritising profitability over chasing sales, particularly in Vietnam. This will translate to higher margins.
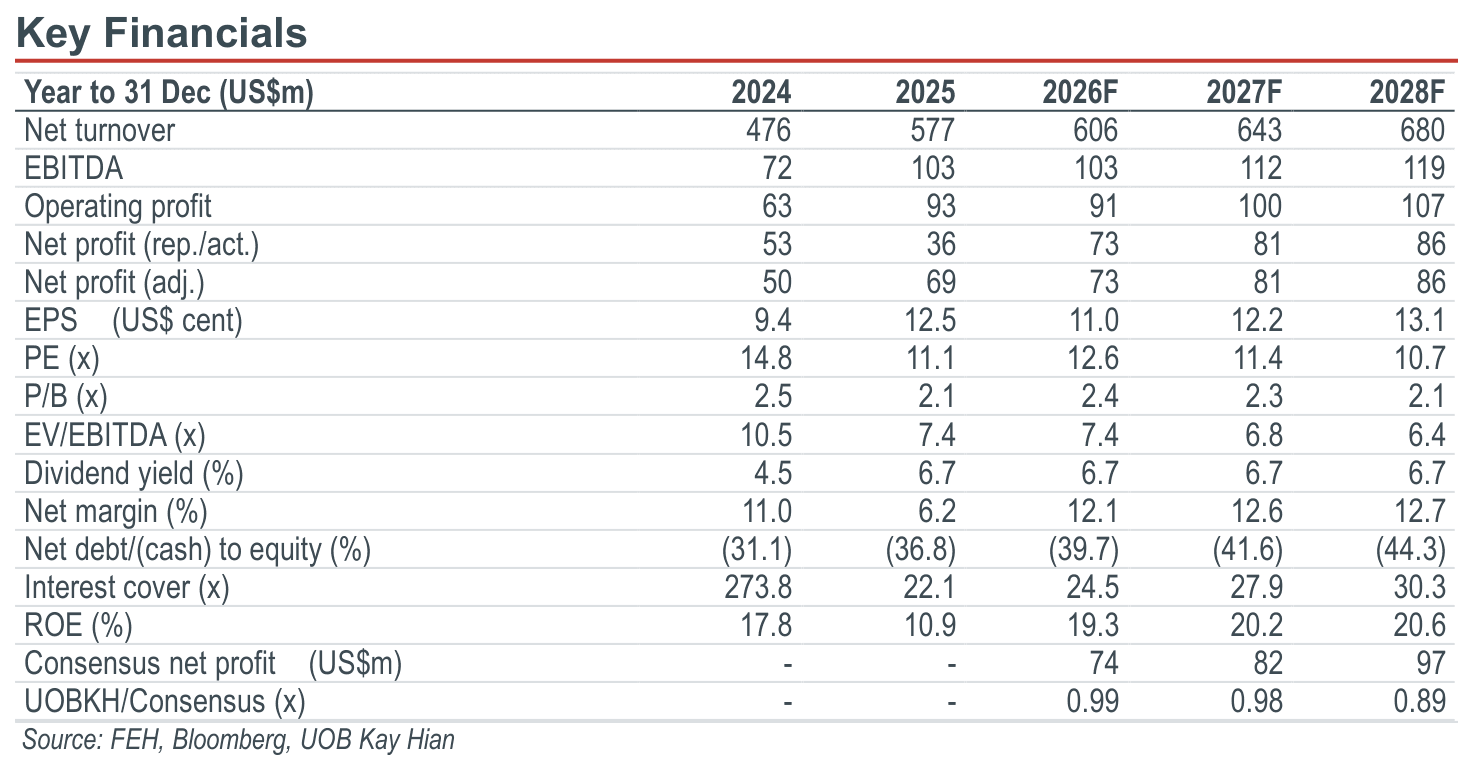
- Maintain BUY with target price of S$3.00. FEH trades at an attractive 11.4x 2027F PE, a 46% discount to peers’ 21x. Its 6.7% yield is also attractive.
Analysis
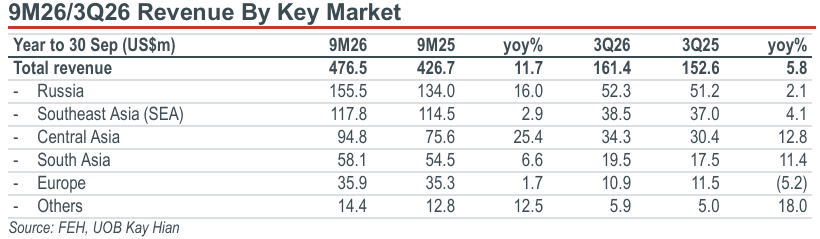
- Top-line reaches another all-time high. Food Empire Holdings’ (FEH) 9M26 revenue rose 11.7% yoy to a record US$476.5m, forming 79% of our full-year forecast and slightly ahead of expectations. 3Q26 revenue increased 5.8% yoy to US$161.4m, marking the third consecutive quarter of yoy growth. FEH remains on track for its sixth straight year of record revenue.
- Broad-based growth led by Central Asia and Russia. Central Asia delivered the strongest 9M26 growth of 25.4% yoy to US$94.8m, driven by higher volumes in Uzbekistan, Turkmenistan and Georgia, stronger Kazakhstan demand and Tenge appreciation. Russia grew 16.0% yoy to US$155.5m and remained FEH’s largest market. South Asia/SEA/Europe/Others grew 6.6%/2.9%/1.7%/12.5% yoy respectively.
- Expect better profitability hoh for 2H26 as management prioritises margins. Given higher emphasis on margins for 2H26, we expect better earnings of around 7% hoh for 2H26. 3Q26 revenue growth eased to 5.8% yoy amid geopolitical uncertainty, logistics constraints and currency volatility. Central Asia faced Middle East-related supply-chain disruption and higher production and distribution costs, while Europe revenue fell 5.2% yoy. FEH responded by placing greater emphasis on margins while continuing to invest for growth.
Highlights
- FEH’s 9M26 revenue reached a record US$477m (+12% yoy), while 3Q26 revenue rose 6% yoy to US$161m. 9M26 revenue formed 79% of our full-year forecast, ahead of expectations.
- We expect 2H26 net margin and earnings to be better hoh. While 3Q26 revenue growth moderated to 6%, FEH is deliberately prioritising profitability over chasing sales, particularly in Vietnam. This will translate to higher margins.
- Maintain BUY with target price of S$3.00. FEH trades at an attractive 11.4x 2027F PE, a 46% discount to peers’ 21x. Its 6.7% yield is also attractive.
Analysis
- Top-line reaches another all-time high. Food Empire Holdings’ (FEH) 9M26 revenue rose 11.7% yoy to a record US$476.5m, forming 79% of our full-year forecast and slightly ahead of expectations. 3Q26 revenue increased 5.8% yoy to US$161.4m, marking the third consecutive quarter of yoy growth. FEH remains on track for its sixth straight year of record revenue.
- Broad-based growth led by Central Asia and Russia. Central Asia delivered the strongest 9M26 growth of 25.4% yoy to US$94.8m, driven by higher volumes in Uzbekistan, Turkmenistan and Georgia, stronger Kazakhstan demand and Tenge appreciation. Russia grew 16.0% yoy to US$155.5m and remained FEH’s largest market. South Asia/SEA/Europe/Others grew 6.6%/2.9%/1.7%/12.5% yoy respectively.
- Expect better profitability hoh for 2H26 as management prioritises margins. Given higher emphasis on margins for 2H26, we expect better earnings of around 7% hoh for 2H26. 3Q26 revenue growth eased to 5.8% yoy amid geopolitical uncertainty, logistics constraints and currency volatility. Central Asia faced Middle East-related supply-chain disruption and higher production and distribution costs, while Europe revenue fell 5.2% yoy. FEH responded by placing greater emphasis on margins while continuing to invest for growth.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$1.79
S$3.00
67.6%
S$3.49
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

28 Oct 2026
iFAST Corporation (IFAST SP): 9M26: Earnings Beat; Record AUA And Strong Banking Growth

28 Sept 2026
Reclaims Global (RGL SP) : 1HFY27: Healthy Results; Margins Remain Resilient

12 Oct 2026
Food Empire Holdings (FEH SP) - Meeting Highlights: Strong Brand Equity Supports Inflation Resilience; Russian Risks Warrant Differentiated Assessment
Our latest research

13 Nov 2026
SATS (SATS SP): 1HFY27: Steady Headline Earnings Supported By Tax Items; Cost Pressures Peak, Margins Poised To Recover

13 Nov 2026
Genting Singapore (GENS SP): 3Q26: Dragged By Weaker Gaming Operations

13 Nov 2026