
Company Coverage
Riverstone Holdings (RSTON SP): 3Q26: Increased Capacity And Consumables To Drive Future Growth
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$0.715
S$1.080
+51.0%
S$1.210
Analyst
Analyst
Highlights
- Riverstone’s 9M26 earnings rose 15% yoy to RM177m, accounting for 81% of our full-year forecasts, ahead of expectations.
- We expect the cleanroom segment to continue benefitting from expansion of cleanroom consumable products, sustained demand from data centre and memory storage sectors.
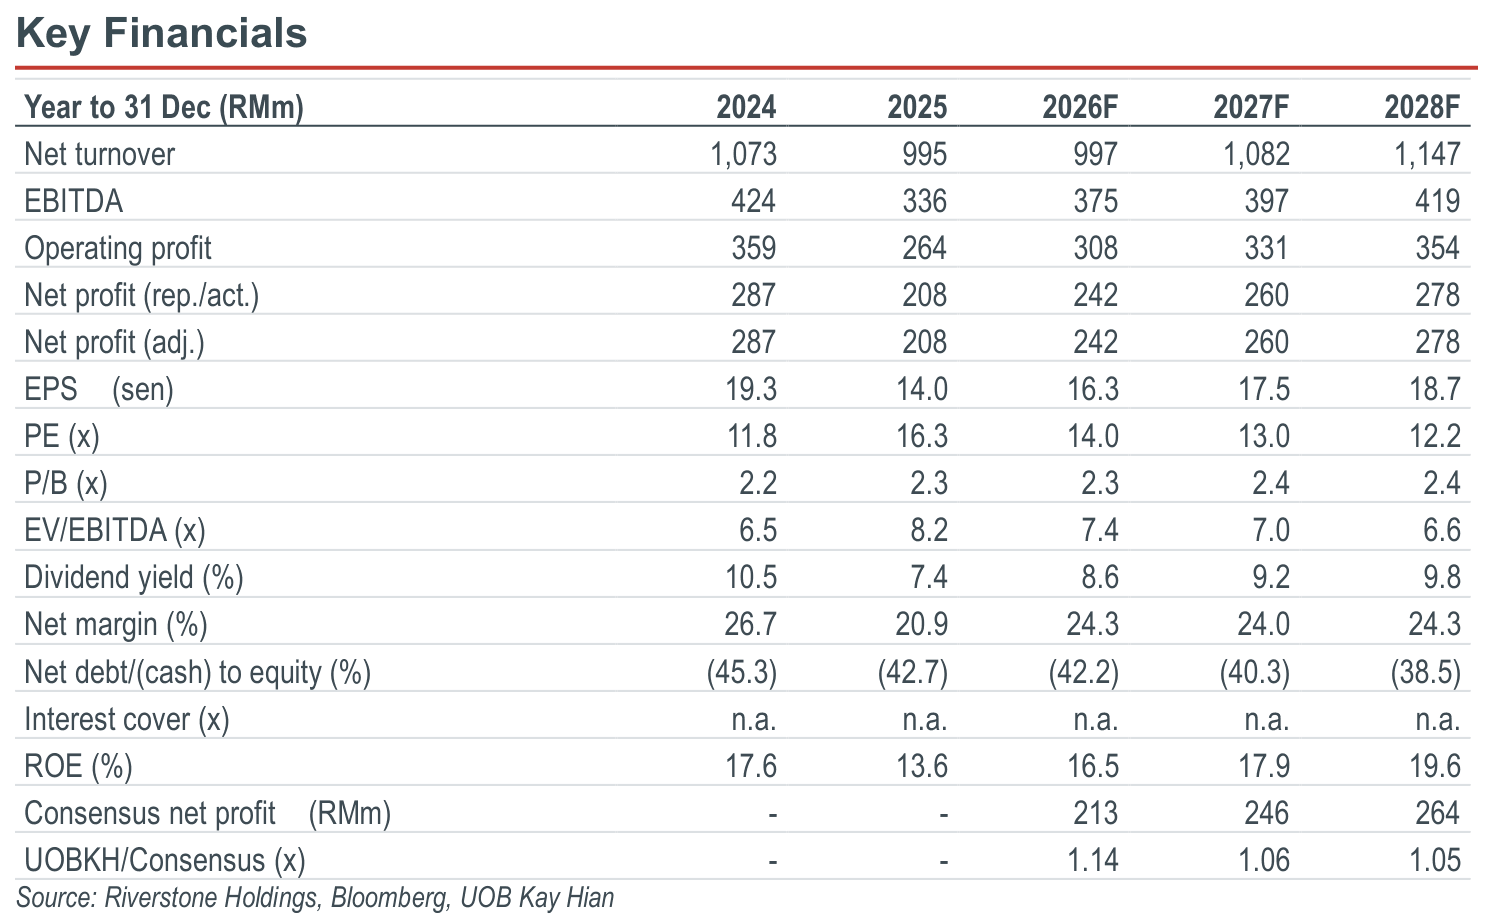
- Maintain BUY with an 11% lower target price of S$1.08, pegged to 19x 2027F PE. Riverstone currently trades at around 40% discount to peers and offers an attractive yield of above 8.5% for 2026.
Analysis
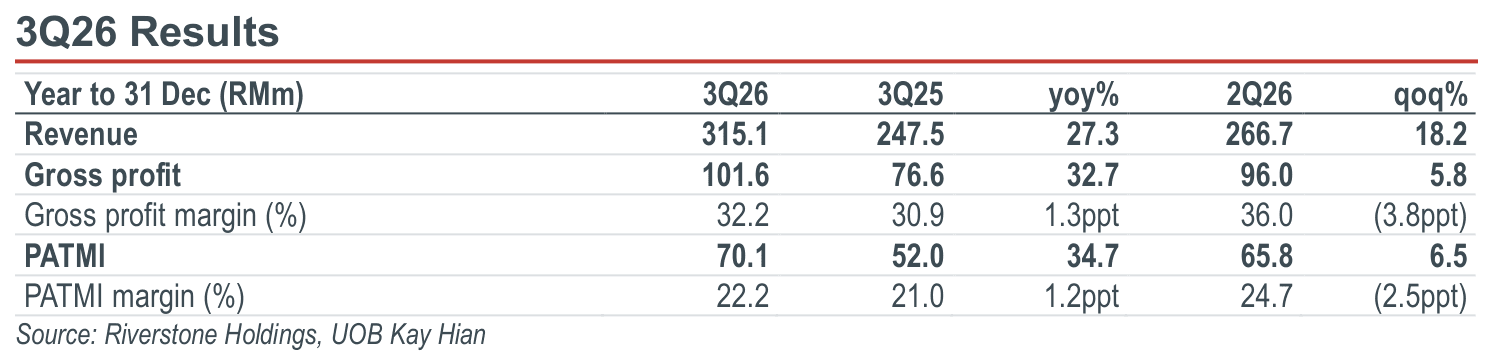
- 3Q26 earnings significantly ahead of expectations. Riverstone reported 3Q26 PATMI of RM70.1m (+34.7% yoy, +6.5% qoq), supported by stronger sales volumes across both cleanroom and healthcare segments. Revenue rose 27.3% yoy and 18.2% qoq to RM315.1m, its highest quarterly revenue in over three years. This brought 9M26 revenue to RM796.1m (+6.9% yoy) and PATMI to RM176.9m (+15.0% yoy), representing 79.9% and 81.2% of our 2026 full-year forecasts respectively, ahead of expectations.
- Cleanroom: AI-related demand drives sequential recovery. Sales volume of cleanroom gloves increased by approximately 40% yoy in 3Q26, supported by stronger demand from existing and new customers across AI-related infrastructure, data centres and memory storage applications. The cleanroom segment accounted for approximately 40% of group revenue, with gross margin remaining healthy at around 51%. ASPs remained broadly stable at US$90-92 per carton, with management expecting sustained demand from now till 1Q27. Expanded cleanroom washing and packaging capacity should also ease production constraints and support higher volumes.
Highlights
- Riverstone’s 9M26 earnings rose 15% yoy to RM177m, accounting for 81% of our full-year forecasts, ahead of expectations.
- We expect the cleanroom segment to continue benefitting from expansion of cleanroom consumable products, sustained demand from data centre and memory storage sectors.
- Maintain BUY with an 11% lower target price of S$1.08, pegged to 19x 2027F PE. Riverstone currently trades at around 40% discount to peers and offers an attractive yield of above 8.5% for 2026.
Analysis
- 3Q26 earnings significantly ahead of expectations. Riverstone reported 3Q26 PATMI of RM70.1m (+34.7% yoy, +6.5% qoq), supported by stronger sales volumes across both cleanroom and healthcare segments. Revenue rose 27.3% yoy and 18.2% qoq to RM315.1m, its highest quarterly revenue in over three years. This brought 9M26 revenue to RM796.1m (+6.9% yoy) and PATMI to RM176.9m (+15.0% yoy), representing 79.9% and 81.2% of our 2026 full-year forecasts respectively, ahead of expectations.
- Cleanroom: AI-related demand drives sequential recovery. Sales volume of cleanroom gloves increased by approximately 40% yoy in 3Q26, supported by stronger demand from existing and new customers across AI-related infrastructure, data centres and memory storage applications. The cleanroom segment accounted for approximately 40% of group revenue, with gross margin remaining healthy at around 51%. ASPs remained broadly stable at US$90-92 per carton, with management expecting sustained demand from now till 1Q27. Expanded cleanroom washing and packaging capacity should also ease production constraints and support higher volumes.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$0.715
S$1.080
+51.0%
S$1.210
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

9 Oct 2026
Riverstone Holdings (RSTON SP): AI, Forex And Pricing Tailwinds Emerging; 7% Yield Is Attractive

12 Nov 2026
UMS Integration (UMSH SP): 3Q26: Earnings In Line; New Customer Ramp-up Drives Growth

30 Oct 2026
Keppel (KEP SP): Decent Headline Earnings Growth But Slower-than-expected Core Earnings Growth In 3Q26
Our latest research

18 Nov 2026
Delfi (DELFI SP): 3Q26: Resilient Demand For Own Brands Amid Margin Pressure

17 Nov 2026
United Hampshire US REIT (UHU SP): 9M26: Resilient Retail Portfolio With Multiple Paths For Growth

17 Nov 2026