
Company Coverage
Venture Corporation (VMS SP): 3Q26: Broadening Growth Led By Portfolio B; Maintain BUY
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$14.29
S$18.30
28.1%
S$21.10
Analyst
Highlights
9M26 revenue of S$2,145.1m and PATMI of S$187.1m met 80.4% and 76.6% of our full-year forecasts respectively; earnings were broadly in line.
Portfolio B grew 38.1% yoy on production ramp-ups and market share gains; recovery in life science segment supported Portfolio A’s growth.
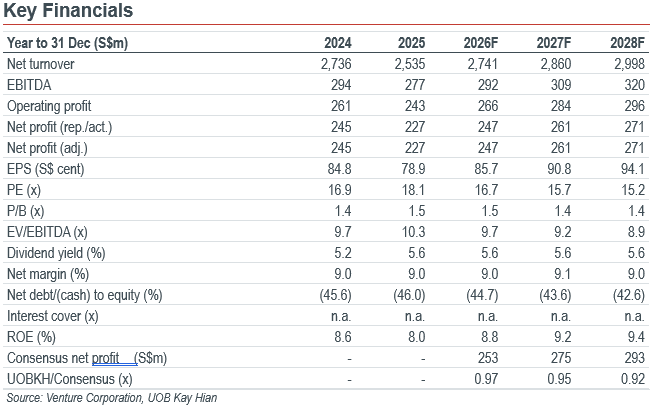
Maintain BUY with a target price of S$18.30, pegged to 20.2x 2027F PE. Broadening demand and a strong balance sheet support our view.
Analysis
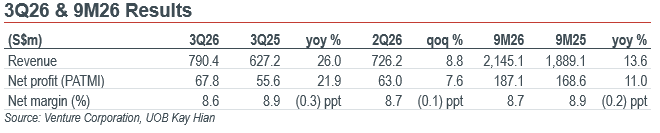
Growth accelerates into 3Q26. Venture Corporation's (VMS) revenue rose 26.0% yoy to S$790.4m, accelerating from 12.5% in 2Q26 and 1.9% in 1Q26. PATMI increased 21.9% yoy to S$67.8m, while revenue and earnings grew 8.8% and 7.6% qoq respectively. For 3Q26, revenue and profit accounted for 29.6% and 27.8% of our full-year forecasts respectively. 9M26 revenue rose 13.6% to S$2,145.1m and PATMI grew 11.0% to S$187.1m, representing 80.4% and 76.6% of our full-year forecasts respectively. Revenue was ahead of the 9M run rate, while earnings were broadly in line.
Portfolio B remains the main growth driver. Revenue grew 38.1% yoy to about S$560m, with the company reporting a S$154m increase across its technology domains. Production ramp-ups and market-share gains supported the test & measurement instrumentation, networking & communications, and semiconductor-related equipment segments. The portfolio contributed about 71% of group revenue. VMS' 1H26 presentation linked additional businesses in these domains to multiple end-markets, including AI-related infrastructure. The 3Q update points to sustained demand and deeper customer engagements, supporting our positive view on the recovery.
Highlights
9M26 revenue of S$2,145.1m and PATMI of S$187.1m met 80.4% and 76.6% of our full-year forecasts respectively; earnings were broadly in line.
Portfolio B grew 38.1% yoy on production ramp-ups and market share gains; recovery in life science segment supported Portfolio A’s growth.
Maintain BUY with a target price of S$18.30, pegged to 20.2x 2027F PE. Broadening demand and a strong balance sheet support our view.
Analysis
Growth accelerates into 3Q26. Venture Corporation's (VMS) revenue rose 26.0% yoy to S$790.4m, accelerating from 12.5% in 2Q26 and 1.9% in 1Q26. PATMI increased 21.9% yoy to S$67.8m, while revenue and earnings grew 8.8% and 7.6% qoq respectively. For 3Q26, revenue and profit accounted for 29.6% and 27.8% of our full-year forecasts respectively. 9M26 revenue rose 13.6% to S$2,145.1m and PATMI grew 11.0% to S$187.1m, representing 80.4% and 76.6% of our full-year forecasts respectively. Revenue was ahead of the 9M run rate, while earnings were broadly in line.
Portfolio B remains the main growth driver. Revenue grew 38.1% yoy to about S$560m, with the company reporting a S$154m increase across its technology domains. Production ramp-ups and market-share gains supported the test & measurement instrumentation, networking & communications, and semiconductor-related equipment segments. The portfolio contributed about 71% of group revenue. VMS' 1H26 presentation linked additional businesses in these domains to multiple end-markets, including AI-related infrastructure. The 3Q update points to sustained demand and deeper customer engagements, supporting our positive view on the recovery.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$14.29
S$18.30
28.1%
S$21.10
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

5 Nov 2026
SIA Engineering (SIE SP) - 1HFY27: Results In Line; Steady Earnings Despite Expansion-related Gestation Costs

5 Nov 2026
Beng Kuang Marine (BKM SP) - 3Q26: Higher Offshore Activities Drive Robust Growth

30 Oct 2026
Nanofilm Technologies International (NANO SP): 3Q26: Margin Expansion Cushions Softer AMBU Revenue
Our latest research

10 Nov 2026
Frasers Logistics & Commercial Trust (FLT SP): 2HFY26: Logistics Strength But Higher Gearing Limits Debt Headroom

10 Nov 2026
Oversea-Chinese Banking Corp (OCBC SP): 3Q26: Banking Strength Offsets Insurance Weakness

6 Nov 2026