Company Coverage
CapitaLand Integrated Commercial Trust (CICT SP): 3Q26: Uptick For Office Occupancy; Firmer Reversion For Retail
BUY (Maintained)
Current price:
Target price:
Upside:
S$2.28
S$3.11
34.2%
Analyst
Highlights
- Office occupancy rose 1.0ppt qoq to 95.4% with broad-based improvements in Singapore, Germany and Australia. We estimated rental reversion for retail portfolio improved from +3.5% in 2Q26 to +6.6% for 3Q26.
- Management targets mid-single-digit reversions for both office and retail in 2026. Paragon, balance 55% of CapitaSpring and Gallileo’s progressive handover to ECB would contribute fully for six months in 2H26.
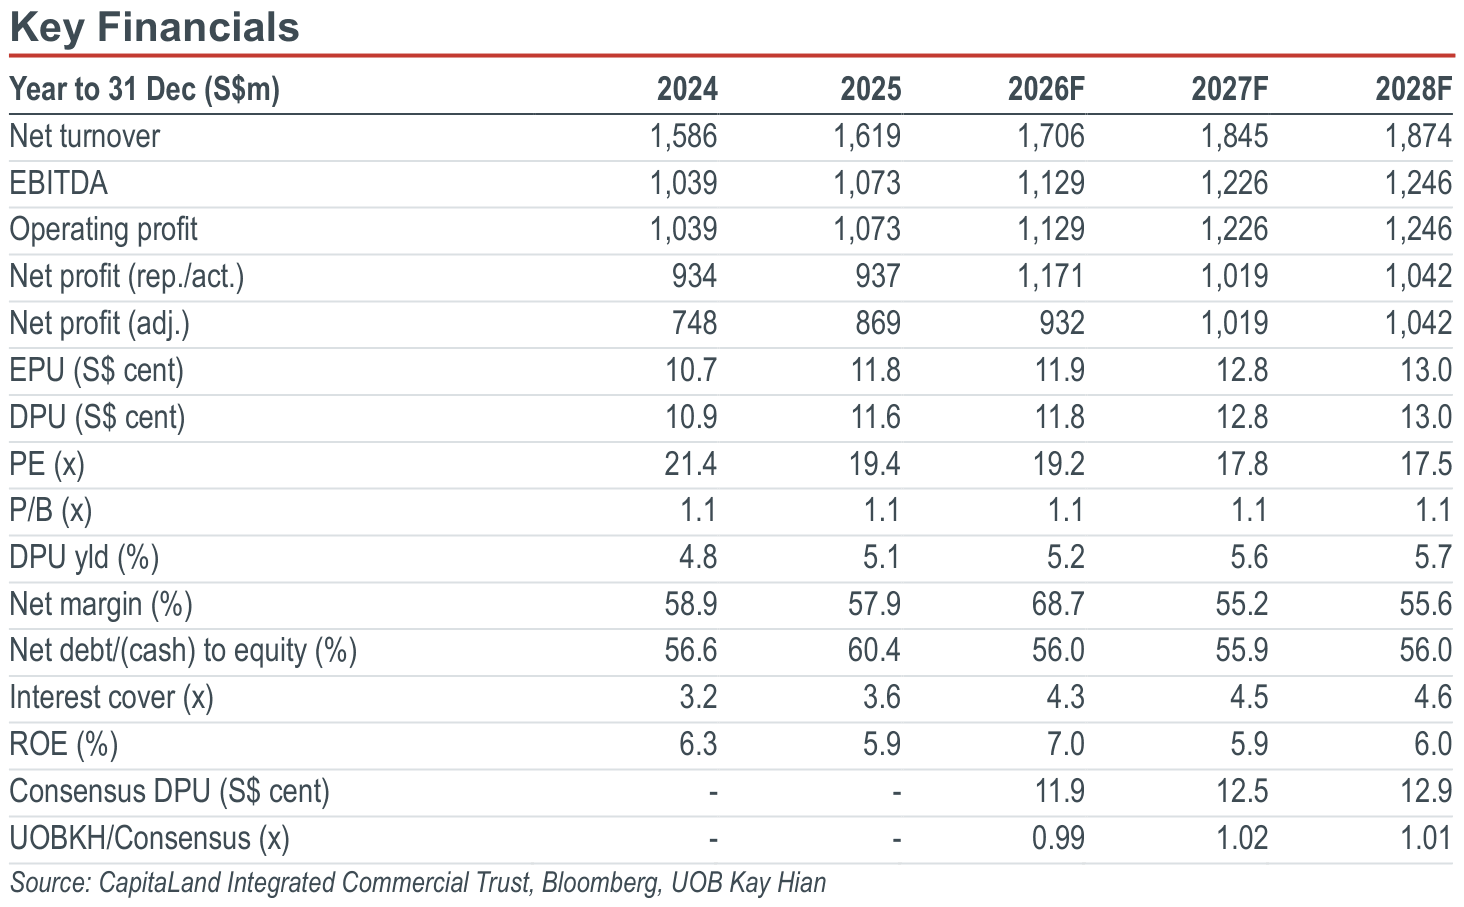
- Maintain BUY. Target price: S$3.11.
Analysis
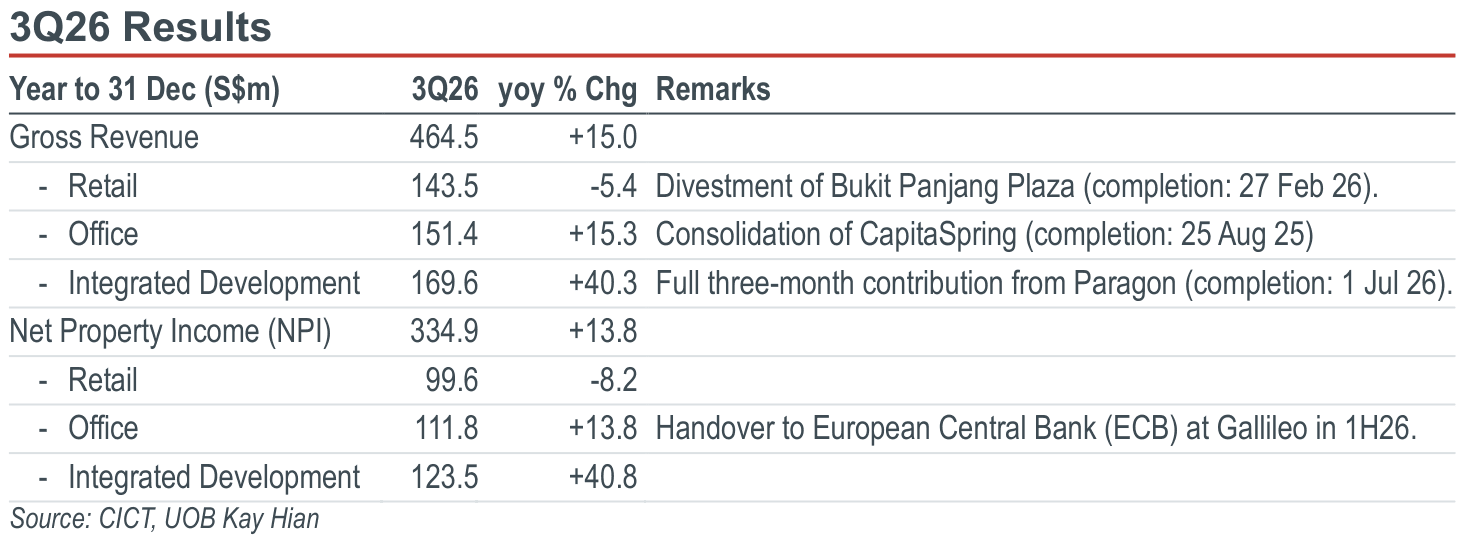
- CapitaLand Integrated Commercial Trust (CICT) report NPI of S$334.9m for 3Q26, up 13.8% yoy and quite in line with our expectation.
- Financial performance strengthened in 3Q26. Gross revenue and NPI rose 15.0% and 13.8% yoy respectively in 3Q26, driven by Paragon, Gallileo and CapitaSpring step-up acquisition, partly offset by the divestments of Bukit Panjang Plaza and Asia Square Tower 2 (AST2). NPI from integrated development grew 41% due to contribution from newly acquired Paragon.
- Retail: Uptick in rent reversion. Retail occupancy eased 0.4ppt qoq to 97.3% (suburban: 99.1% and downtown: 96.0%), excluding AEI space at Plaza Singapura and The Atrium @ Orchard. Retail rental reversion improved to +4.6% for 9M26 (suburban: +4.6% and downtown: +4.5%). Tenant retention was 83.6%. Tenant sales psf grew 2.1% yoy, supported by seasonal promotions and new openings, particularly in jewellery & watches and food & beverages. AEI for Tampines Mall was completed in 3Q26 and has added 16 new brands. Chanel, Dior and YSL, who were previously sub-tenants within Isetan, have setup standalone boutiques at Tampines Mall.
Highlights
- Office occupancy rose 1.0ppt qoq to 95.4% with broad-based improvements in Singapore, Germany and Australia. We estimated rental reversion for retail portfolio improved from +3.5% in 2Q26 to +6.6% for 3Q26.
- Management targets mid-single-digit reversions for both office and retail in 2026. Paragon, balance 55% of CapitaSpring and Gallileo’s progressive handover to ECB would contribute fully for six months in 2H26.
- Maintain BUY. Target price: S$3.11.
Analysis
- CapitaLand Integrated Commercial Trust (CICT) report NPI of S$334.9m for 3Q26, up 13.8% yoy and quite in line with our expectation.
- Financial performance strengthened in 3Q26. Gross revenue and NPI rose 15.0% and 13.8% yoy respectively in 3Q26, driven by Paragon, Gallileo and CapitaSpring step-up acquisition, partly offset by the divestments of Bukit Panjang Plaza and Asia Square Tower 2 (AST2). NPI from integrated development grew 41% due to contribution from newly acquired Paragon.
- Retail: Uptick in rent reversion. Retail occupancy eased 0.4ppt qoq to 97.3% (suburban: 99.1% and downtown: 96.0%), excluding AEI space at Plaza Singapura and The Atrium @ Orchard. Retail rental reversion improved to +4.6% for 9M26 (suburban: +4.6% and downtown: +4.5%). Tenant retention was 83.6%. Tenant sales psf grew 2.1% yoy, supported by seasonal promotions and new openings, particularly in jewellery & watches and food & beverages. AEI for Tampines Mall was completed in 3Q26 and has added 16 new brands. Chanel, Dior and YSL, who were previously sub-tenants within Isetan, have setup standalone boutiques at Tampines Mall.
BUY (Maintained)
Current price:
Target price:
Upside:
S$2.28
S$3.11
34.2%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

28 Oct 2026
CapitaLand Ascott Trust (CLAS SP): Sturdy Recovery From Student Accommodation In 3Q26; Strong Reversion From Rental Housing

26 Oct 2026
Keppel DC REIT (KDCREIT SP): 3Q26: Completes Acquisition Ahead Of AI Funding Squeeze

23 Oct 2026
Frasers Centrepoint Trust (FCT SP): 2HFY26: Positive Reversion And AEIs Underpin Sustainable Growth
Our latest research

30 Oct 2026
Keppel (KEP SP): Decent Headline Earnings Growth But Slower-than-expected Core Earnings Growth In 3Q26

30 Oct 2026
Nanofilm Technologies International (NANO SP): 3Q26: Margin Expansion Cushions Softer AMBU Revenue

29 Oct 2026