Company Coverage
Nanofilm Technologies International (NANO SP): 3Q26: Margin Expansion Cushions Softer AMBU Revenue
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$0.805
S$1.090
35.4%
S$1.680
Analyst
Highlights
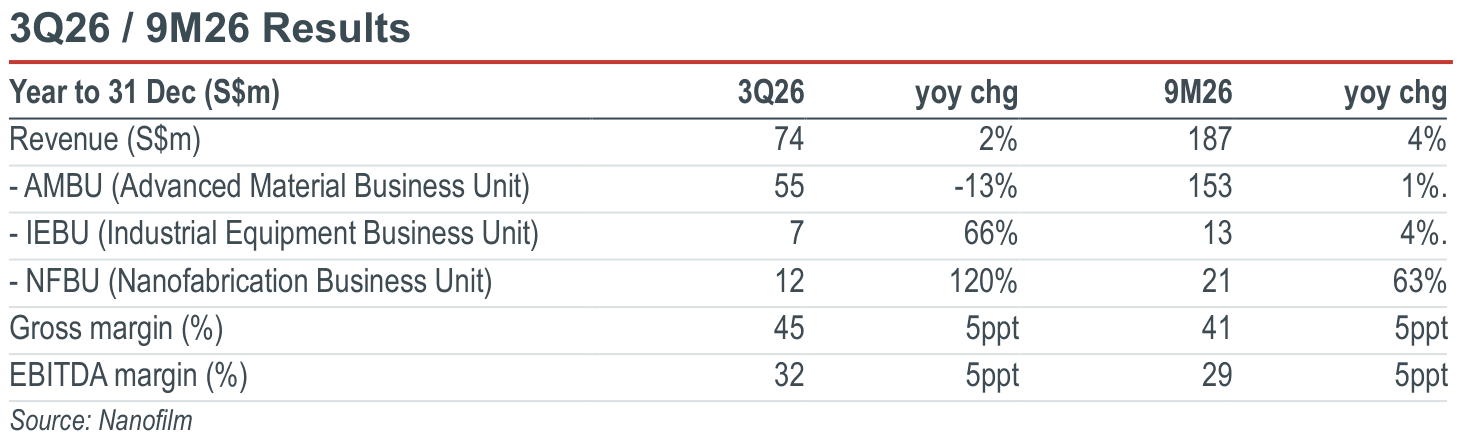
- 3Q26 revenue grew 2% yoy to S$74m, bringing 9M26 revenue to S$187m (+4% yoy), or 68% of our full-year forecast, which we deem in line given a delayed production ramp-up which will see fulfilment in 4Q26.
- Gross and EBITDA margins each rose 5ppt yoy to 45% and 32% respectively. Strong NFBU and IEBU growth offset weaker AMBU sales.
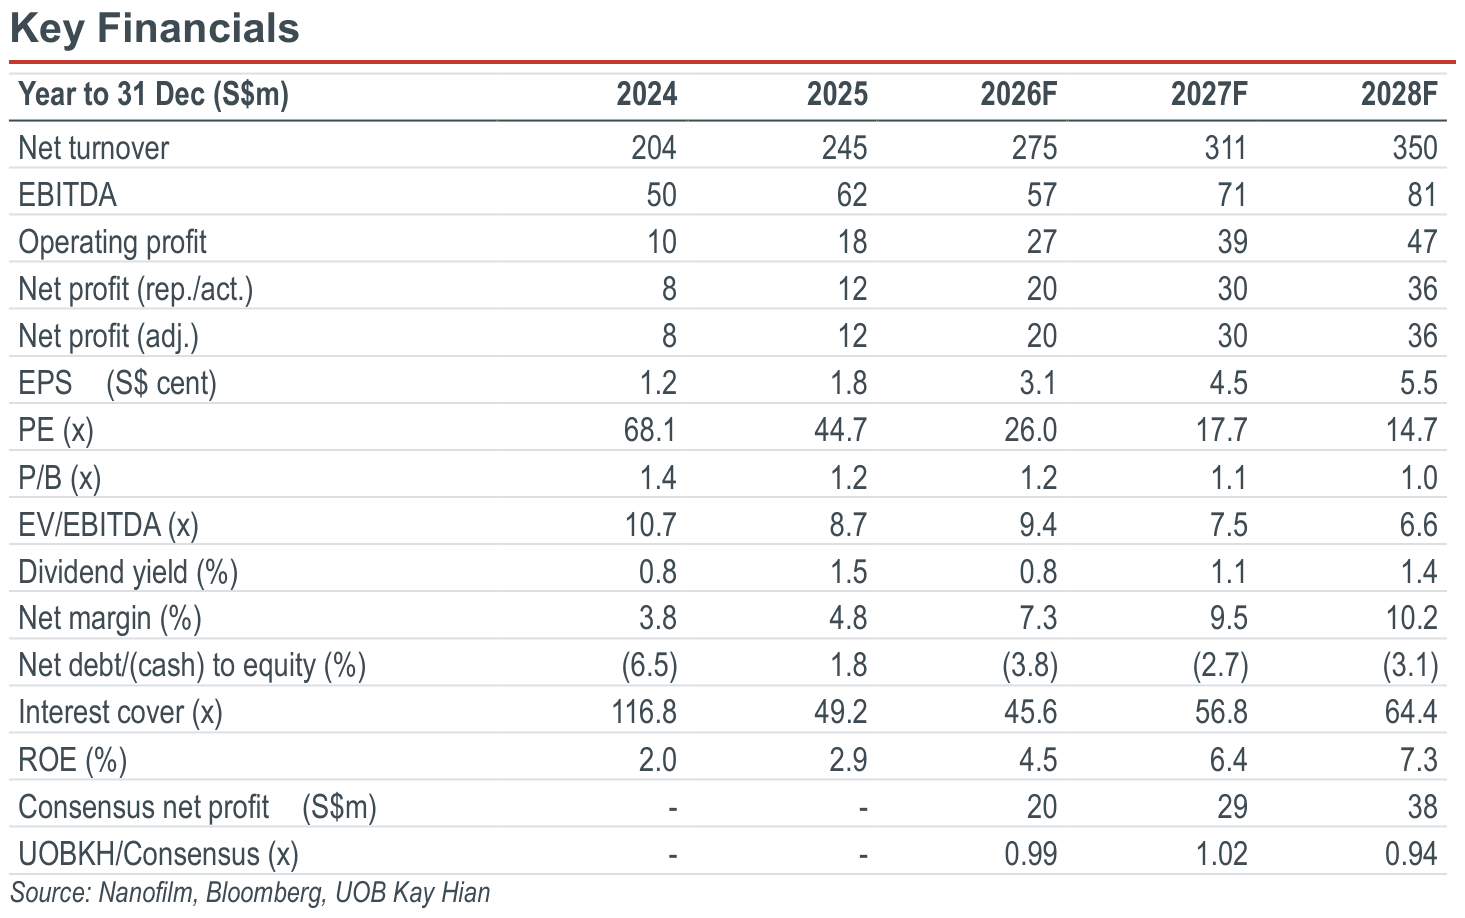
- The flagship coating programme is now at full capacity, supporting 4Q26. Maintain BUY with a 27% lower target price of S$1.09 (24x 2027F EPS).
Analysis
- Margins growth. Nanofilm improved despite modest revenue Technologies International (Nanofilm) reported a 3Q26 revenue of S$74m (+2% yoy). Gross and EBITDA margins rose 5ppt yoy to 45% and 32% respectively, supported by automation and operational optimisation. For 9M26, revenue rose 4% yoy to S$187m, while gross and EBITDA margins improved to 41% and 29%. Management indicated improved profitability, although PATMI was not disclosed.
- AMBU weakness partly offset by industrial growth; expect catching up in 4Q26. AMBU accounted for 82% of 9M26 revenue. The consumer subsegment’s revenue fell 19% yoy to S$39m in 3Q26 amid smartphone substrate changes and a supply-chain-related delay in a flagship programme ramp-up until late-3Q26. The industrial subsegment’s revenue grew 8% yoy to S$16m, driven by Europe. The flagship functional coating project has now reached full capacity, supporting a stronger contribution in 4Q26.
Highlights
- 3Q26 revenue grew 2% yoy to S$74m, bringing 9M26 revenue to S$187m (+4% yoy), or 68% of our full-year forecast, which we deem in line given a delayed production ramp-up which will see fulfilment in 4Q26.
- Gross and EBITDA margins each rose 5ppt yoy to 45% and 32% respectively. Strong NFBU and IEBU growth offset weaker AMBU sales.
- The flagship coating programme is now at full capacity, supporting 4Q26. Maintain BUY with a 27% lower target price of S$1.09 (24x 2027F EPS).
Analysis
- Margins growth. Nanofilm improved despite modest revenue Technologies International (Nanofilm) reported a 3Q26 revenue of S$74m (+2% yoy). Gross and EBITDA margins rose 5ppt yoy to 45% and 32% respectively, supported by automation and operational optimisation. For 9M26, revenue rose 4% yoy to S$187m, while gross and EBITDA margins improved to 41% and 29%. Management indicated improved profitability, although PATMI was not disclosed.
- AMBU weakness partly offset by industrial growth; expect catching up in 4Q26. AMBU accounted for 82% of 9M26 revenue. The consumer subsegment’s revenue fell 19% yoy to S$39m in 3Q26 amid smartphone substrate changes and a supply-chain-related delay in a flagship programme ramp-up until late-3Q26. The industrial subsegment’s revenue grew 8% yoy to S$16m, driven by Europe. The flagship functional coating project has now reached full capacity, supporting a stronger contribution in 4Q26.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$0.805
S$1.090
35.4%
S$1.680
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

28 Oct 2026
iFAST Corporation (IFAST SP): 9M26: Earnings Beat; Record AUA And Strong Banking Growth

28 Oct 2026
CapitaLand Ascott Trust (CLAS SP): Sturdy Recovery From Student Accommodation In 3Q26; Strong Reversion From Rental Housing

30 Oct 2026
Keppel (KEP SP): Decent Headline Earnings Growth But Slower-than-expected Core Earnings Growth In 3Q26
Our latest research
30 Oct 2026
Keppel (KEP SP): Decent Headline Earnings Growth But Slower-than-expected Core Earnings Growth In 3Q26

30 Oct 2026
CapitaLand Integrated Commercial Trust (CICT SP): 3Q26: Uptick For Office Occupancy; Firmer Reversion For Retail

29 Oct 2026