
Company Coverage
NetLink NBN Trust (NETLINK SP) - 1HFY27: EBITDA In Line; Higher Depreciation A Drag To Earnings
HOLD (Maintained)
Current price:
Target price:
Upside:
S$0.935
S$1.01
+8.0%
Analyst
Highlights
- 1HFY27 revenue moderated by 2% yoy but good cost discipline and lower O&M help shore up EBITDA of S$145m (EBITDA margin 71%). That said, net profit fell 7% yoy, dragged by higher depreciation and came in below expectations.
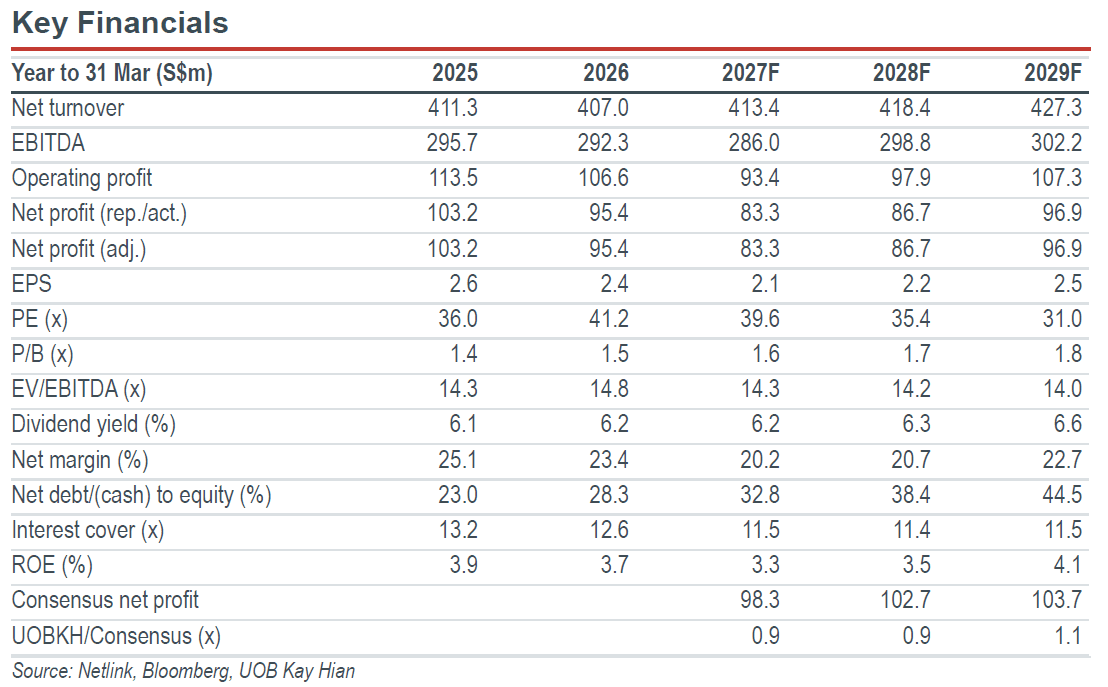
- The discrepancy on our end is due to higher-than-expected depreciation charges, leading us to cut FY27-28 earnings estimates by 10-15%. Netlink declared an interim dividend of 2.74 S cents/share (1HFY26: 2.71 S cents/share). This implies an annualised dividend yield of 6.2%.
- Maintain HOLD with a DCF-based target price of S$1.01.
Analysis
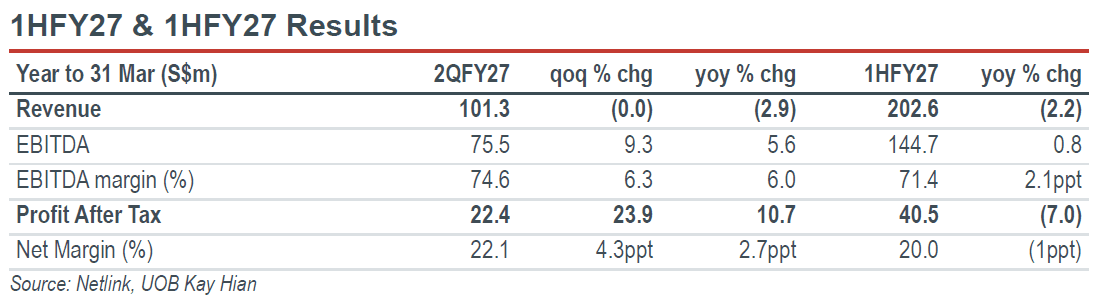
- 1HFY27: Earnings below expectations. NetLink NBN Trust (Netlink) reported a weaker 1HFY27 revenue (-2% yoy), but managed to deliver stable EBITDA (+1% yoy) with healthy margin expansion (+2.1 ppt) from lower operations and maintenance (O&M) expenses. 1HFY27 net profit, however, fell 10% yoy due to elevated depreciation from the Nationwide Broadband Network (NBN) upgrade and internal IT system upgrades. Accounting for 40% of our full-year forecasts, we deem the results to be below expectations.
- For 2QFY27, revenue was flat qoq, but fell 2% yoy given lower ancillary project revenue (-32% qoq, -37% yoy) as projects were delayed. This was cushioned by a sequential pickup in installation (+17% qoq) and co-location segment (+7% qoq) revenue contribution. 2QFY27 net profit improved to RM22.1m (+24% qoq, +11% yoy), driven by healthy EBITDA growth (+9% qoq, +6% yoy) from lower PPE write-off and easing lease expenses, coupled with a higher income tax credit during the quarter.
Highlights
- 1HFY27 revenue moderated by 2% yoy but good cost discipline and lower O&M help shore up EBITDA of S$145m (EBITDA margin 71%). That said, net profit fell 7% yoy, dragged by higher depreciation and came in below expectations.
- The discrepancy on our end is due to higher-than-expected depreciation charges, leading us to cut FY27-28 earnings estimates by 10-15%. Netlink declared an interim dividend of 2.74 S cents/share (1HFY26: 2.71 S cents/share). This implies an annualised dividend yield of 6.2%.
- Maintain HOLD with a DCF-based target price of S$1.01.
Analysis
- 1HFY27: Earnings below expectations. NetLink NBN Trust (Netlink) reported a weaker 1HFY27 revenue (-2% yoy), but managed to deliver stable EBITDA (+1% yoy) with healthy margin expansion (+2.1 ppt) from lower operations and maintenance (O&M) expenses. 1HFY27 net profit, however, fell 10% yoy due to elevated depreciation from the Nationwide Broadband Network (NBN) upgrade and internal IT system upgrades. Accounting for 40% of our full-year forecasts, we deem the results to be below expectations.
- For 2QFY27, revenue was flat qoq, but fell 2% yoy given lower ancillary project revenue (-32% qoq, -37% yoy) as projects were delayed. This was cushioned by a sequential pickup in installation (+17% qoq) and co-location segment (+7% qoq) revenue contribution. 2QFY27 net profit improved to RM22.1m (+24% qoq, +11% yoy), driven by healthy EBITDA growth (+9% qoq, +6% yoy) from lower PPE write-off and easing lease expenses, coupled with a higher income tax credit during the quarter.
HOLD (Maintained)
Current price:
Target price:
Upside:
S$0.935
S$1.01
+8.0%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

30 Oct 2026
Nanofilm Technologies International (NANO SP): 3Q26: Margin Expansion Cushions Softer AMBU Revenue

29 Oct 2026
Aztech Global (AZTECH SP): 3Q26: Earnings In Line; Competition Remains Intense

16 Sept 2026
Singapore Airlines (SIA SP): Near-term Outlook Clouded By Elevated Jet Fuel Prices Amid Middle East Tensions
Our latest research

2 Nov 2026
CapitaLand Ascendas REIT (CLAR SP) - 3Q26: Uptick In Occupancy From Singapore And The US

30 Oct 2026
Keppel (KEP SP): Decent Headline Earnings Growth But Slower-than-expected Core Earnings Growth In 3Q26

30 Oct 2026