
Company Coverage
City Developments (CIT SP): Sharpening And Refreshing Its Growth Strategy
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$7.59
S$11.85
56.1%
S$11.85
Analyst
Highlights
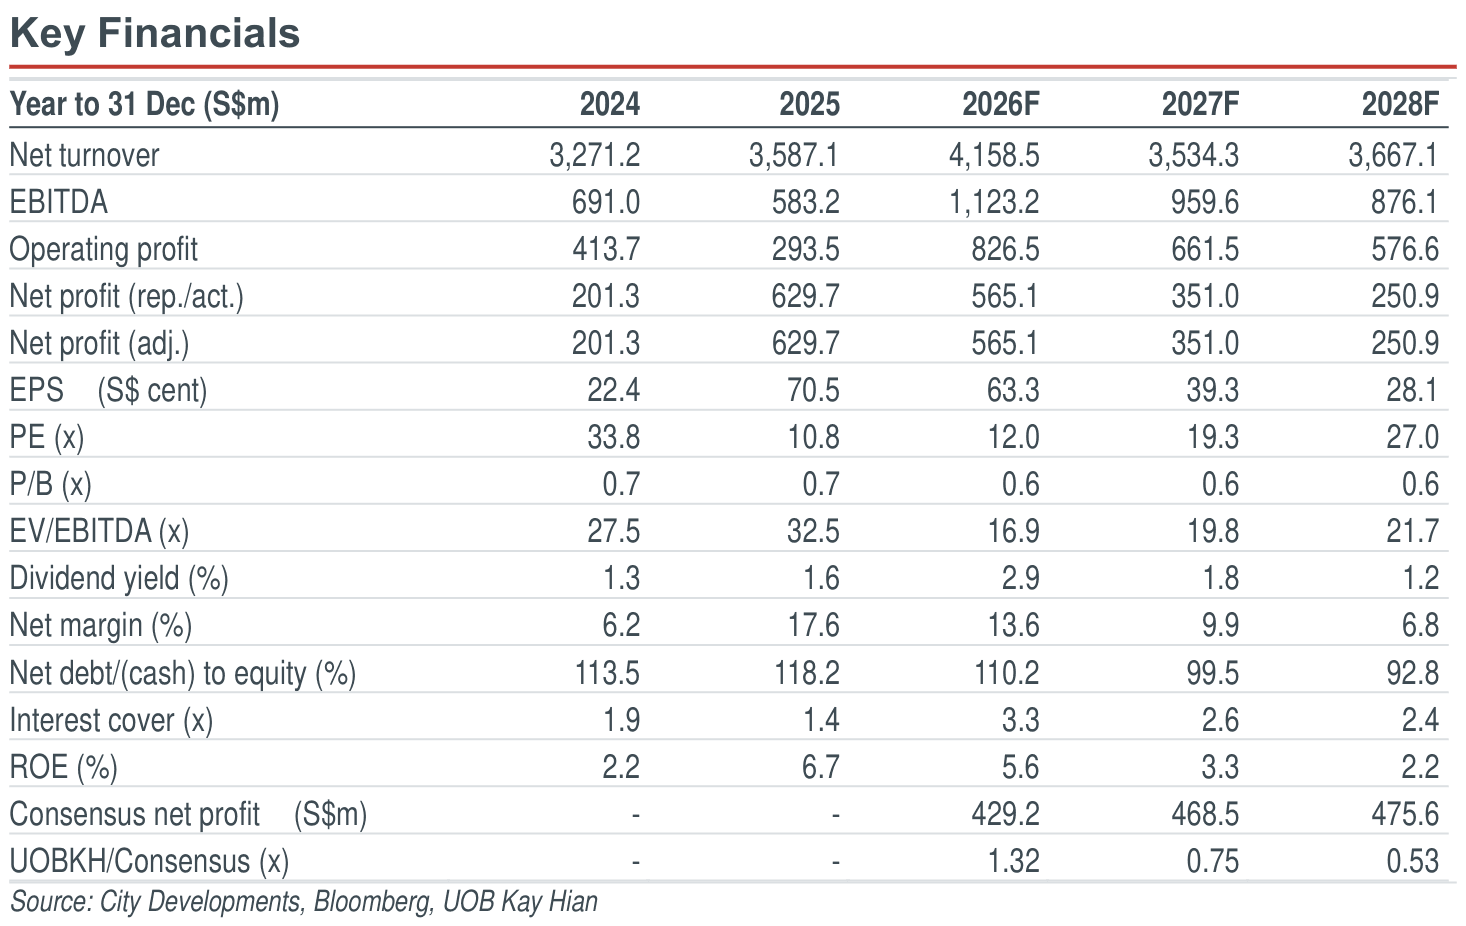
- Sharpening strategic focus, enhancing shareholder returns. In its strategic review, CIT detailed a three-year plan to optimise its balance sheet and reinvest for growth, between 2027-29. When executed successfully, this should enable the group to unlock a total of about S$1b of net profit from divestment gains. Together, with a projected S$6b of future cash inflow from its development projects, gearing is expected to dip to about 55% by end-29.
- S$6b of assets earmarked to be recycled… The commercial segment will form the bulk (45%) of the S$6b assets to be sold, while hotels will make up a further 30% (S$1.8b) with living portfolio (5%) and the remaining 20% from legacy residential and other assets.
- …and S$5b to be reinvested for future growth. An estimated 60% of the S$5b investment target is allocated to Singapore (including residential development sites), 30% in China and 10% in other geographies. It plans to pace its exit from Australia, citing challenging market conditions. Core sectors for reinvestment include Singapore and China residential, Singapore commercial, hospitality properties in key gateway cities and the Singapore and Japan living sectors. That said, management is cognisant that the China residential market remains challenging and it would be very selective when assessing new opportunities.
Analysis
- What does S$1b of net divestment gains mean for shareholders? City Developments (CIT) reaffirmed its intention to pay at least 35% in dividend payout ratio on reported net profit annually, which includes divestment gains. A total of S$1b of asset-sale gains would imply a potential dividend payout of at least S$350m or an additional DPS of about S$0.39/share, when the assets are monetised. While this is likely to be spread over the next few years, we believe investors can look forward to a bump-up in DPS when these transactions occur.
Highlights
- Sharpening strategic focus, enhancing shareholder returns. In its strategic review, CIT detailed a three-year plan to optimise its balance sheet and reinvest for growth, between 2027-29. When executed successfully, this should enable the group to unlock a total of about S$1b of net profit from divestment gains. Together, with a projected S$6b of future cash inflow from its development projects, gearing is expected to dip to about 55% by end-29.
- S$6b of assets earmarked to be recycled… The commercial segment will form the bulk (45%) of the S$6b assets to be sold, while hotels will make up a further 30% (S$1.8b) with living portfolio (5%) and the remaining 20% from legacy residential and other assets.
- …and S$5b to be reinvested for future growth. An estimated 60% of the S$5b investment target is allocated to Singapore (including residential development sites), 30% in China and 10% in other geographies. It plans to pace its exit from Australia, citing challenging market conditions. Core sectors for reinvestment include Singapore and China residential, Singapore commercial, hospitality properties in key gateway cities and the Singapore and Japan living sectors. That said, management is cognisant that the China residential market remains challenging and it would be very selective when assessing new opportunities.
Analysis
- What does S$1b of net divestment gains mean for shareholders? City Developments (CIT) reaffirmed its intention to pay at least 35% in dividend payout ratio on reported net profit annually, which includes divestment gains. A total of S$1b of asset-sale gains would imply a potential dividend payout of at least S$350m or an additional DPS of about S$0.39/share, when the assets are monetised. While this is likely to be spread over the next few years, we believe investors can look forward to a bump-up in DPS when these transactions occur.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$7.59
S$11.85
56.1%
S$11.85
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

5 Nov 2026
CapitaLand Investment (CLI SP) - 9M26: Growth Driven By Fee Income

23 Oct 2026
Frasers Centrepoint Trust (FCT SP): 2HFY26: Positive Reversion And AEIs Underpin Sustainable Growth

26 Oct 2026
Suntec REIT (SUN SP): 3Q26: Expression Of Interest Exercise To Divest Australia Assets
Our latest research

16 Nov 2026
CSE Global (CSE SP): 3Q26: Strong Order Momentum; Margin Recovery Expected In 2H26

16 Nov 2026
First Resources (FR SP): 3Q26: Above Expectations On Strong Output; Consensus Looks Too Low For 4Q

16 Nov 2026