
Company Coverage
United Overseas Bank (UOB SP) - 3Q26: Earnings Shortfall From Other Non-Interest Income
NOT RATED
Current price:
Target price:
Upside:
S$38.44
n.a.
n.a.
Analyst
Highlights
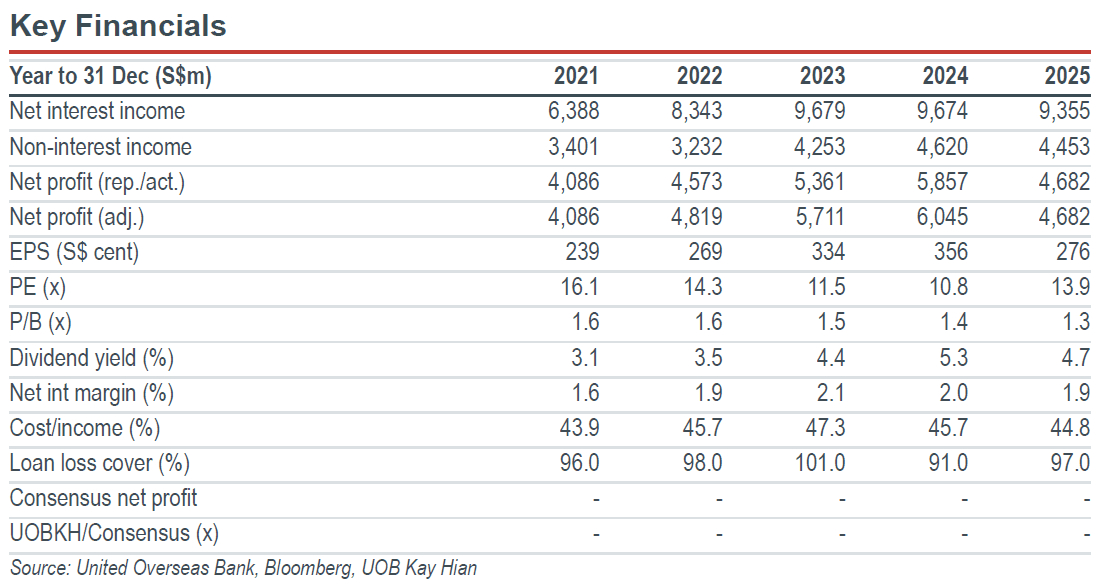
- UOB’s 3Q26 net profit fell 15% qoq to S$1,250m, below consensus estimate of S$1,376m, as margin compression and weaker trading income weighed on earnings. Loan growth of 6% yoy cushioned the decline in NIM to 1.68%.
- Asset quality improved, with new NPL formation declining to S$500m, NPL ratio easing to 1.5% and credit costs falling to 24bp in 3Q26. However, NPL coverage declined 14ppt yoy and 2ppt qoq to 86%.
- Management expects mid-single-digit loan growth and a recovery in net interest income in 2027. Operating costs are expected to rise by mid to high single digits as UOB invests to build new revenue streams.
Analysis
- United Overseas Bank (UOB) reported 3Q26 net profit of S$1,250m (-15% qoq), vs S$443m in 3Q25 when pre-emptive provisioning of S$615m depressed earnings. Earnings were below consensus estimate of S$1,376m.
- Loan growth cushioned margin compression. NIM fell 14bp yoy and 6bp qoq to 1.68% in 3Q26, due to higher deposit costs. Gross customer loans grew 6% yoy and 3% qoq, supporting net interest income of S$2,278m (+1% yoy, -1% qoq). Trade loans grew 31% yoy. Funding costs reduced NIM by 7bp qoq and asset repricing by 1bp, offset by the 2bp benefit from volume.
- Record fees supported by wealth management and lending activities. Net fee income increased 19% yoy and 10% qoq to S$733m. Wealth fees rose to S$258m (+18% yoy, +6% qoq) and loan & trade-related fees increased to S$293m (+4% yoy, +19% qoq). Wealth AUM was S$204b, up 3% yoy and unchanged qoq. Net new money totalled S$5b in 9M26.
- Other non-interest income weakened. Other non-interest income fell 29% yoy and 41% qoq to S$370m, reflecting the absence of prior-quarter divestment gains and softer trading and investment income. Trading and investment income declined 33% yoy and 15% qoq to S$322m.
- Cost discipline partly offset lower income. Operating expenses fell 4% qoq but rose 2% yoy to S$1,570m. Staff costs declined 10% qoq to S$851m, while IT-related expenses rose 5% qoq to S$310m. The cost-to-income ratio increased 1.1ppt qoq to 46.4%.
- Credit costs eased as NPL formation moderated. New NPLs fell to S$500m from S$902m in 2Q26. NPL ratio eased 0.1ppt qoq to 1.5%. Total allowances rose 23% qoq to S$258m. Total credit costs fell to 24bp from 28bp in 2Q26. NPL coverage dipped 14ppt yoy and 2ppt qoq to 86%.
Highlights
- UOB’s 3Q26 net profit fell 15% qoq to S$1,250m, below consensus estimate of S$1,376m, as margin compression and weaker trading income weighed on earnings. Loan growth of 6% yoy cushioned the decline in NIM to 1.68%.
- Asset quality improved, with new NPL formation declining to S$500m, NPL ratio easing to 1.5% and credit costs falling to 24bp in 3Q26. However, NPL coverage declined 14ppt yoy and 2ppt qoq to 86%.
- Management expects mid-single-digit loan growth and a recovery in net interest income in 2027. Operating costs are expected to rise by mid to high single digits as UOB invests to build new revenue streams.
Analysis
- United Overseas Bank (UOB) reported 3Q26 net profit of S$1,250m (-15% qoq), vs S$443m in 3Q25 when pre-emptive provisioning of S$615m depressed earnings. Earnings were below consensus estimate of S$1,376m.
- Loan growth cushioned margin compression. NIM fell 14bp yoy and 6bp qoq to 1.68% in 3Q26, due to higher deposit costs. Gross customer loans grew 6% yoy and 3% qoq, supporting net interest income of S$2,278m (+1% yoy, -1% qoq). Trade loans grew 31% yoy. Funding costs reduced NIM by 7bp qoq and asset repricing by 1bp, offset by the 2bp benefit from volume.
- Record fees supported by wealth management and lending activities. Net fee income increased 19% yoy and 10% qoq to S$733m. Wealth fees rose to S$258m (+18% yoy, +6% qoq) and loan & trade-related fees increased to S$293m (+4% yoy, +19% qoq). Wealth AUM was S$204b, up 3% yoy and unchanged qoq. Net new money totalled S$5b in 9M26.
- Other non-interest income weakened. Other non-interest income fell 29% yoy and 41% qoq to S$370m, reflecting the absence of prior-quarter divestment gains and softer trading and investment income. Trading and investment income declined 33% yoy and 15% qoq to S$322m.
- Cost discipline partly offset lower income. Operating expenses fell 4% qoq but rose 2% yoy to S$1,570m. Staff costs declined 10% qoq to S$851m, while IT-related expenses rose 5% qoq to S$310m. The cost-to-income ratio increased 1.1ppt qoq to 46.4%.
- Credit costs eased as NPL formation moderated. New NPLs fell to S$500m from S$902m in 2Q26. NPL ratio eased 0.1ppt qoq to 1.5%. Total allowances rose 23% qoq to S$258m. Total credit costs fell to 24bp from 28bp in 2Q26. NPL coverage dipped 14ppt yoy and 2ppt qoq to 86%.
NOT RATED
Current price:
Target price:
Upside:
S$38.44
n.a.
n.a.
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

5 Nov 2026
SIA Engineering (SIE SP) - 1HFY27: Results In Line; Steady Earnings Despite Expansion-related Gestation Costs

5 Nov 2026
Beng Kuang Marine (BKM SP) - 3Q26: Higher Offshore Activities Drive Robust Growth

16 Sept 2026
Singapore Airlines (SIA SP): Near-term Outlook Clouded By Elevated Jet Fuel Prices Amid Middle East Tensions
Our latest research
5 Nov 2026
Beng Kuang Marine (BKM SP) - 3Q26: Higher Offshore Activities Drive Robust Growth

5 Nov 2026
CapitaLand Investment (CLI SP) - 9M26: Growth Driven By Fee Income
5 Nov 2026